
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Tsuruha Holdings (TSE:3391) Fully Valued On Mixed Half Year Earnings And Dividend News?
Tsuruha Holdings earnings and dividend reset
Tsuruha Holdings (TSE:3391) just posted half year results to August 31, 2026, reporting higher sales and net income but lower earnings per share, and sharply reduced its interim dividend following a 5 for 1 stock split.
The latest half year update lands after a tough stretch for Tsuruha Holdings’ share price, with a 1-year total shareholder return decline of 11.47% and the stock down 24.35% on a year-to-date basis. However, the 3-year total shareholder return gain of 12.59% suggests the longer-run story has been more resilient than recent momentum indicates.
Scan how Tsuruha Holdings compares with other retailers under pressure by screening for 15 high quality undervalued stocks that combine solid cash generation with sturdier balance sheets.
Bulls argue Tsuruha Holdings now offers solid earnings and cash flow at a cheaper entry point after the split and sell off. Bears focus on softer EPS and a reset dividend. Which side do the current valuation markers support?
Price-to-earnings of 18.8x for Tsuruha Holdings: Is it justified?
On traditional valuation metrics, Tsuruha Holdings is not cheap. The stock trades on a P/E of 18.8x, which sits above both peer and sector averages despite a share price that has already pulled back.
The P/E ratio compares what investors are willing to pay today for each unit of current earnings. For a retailer like Tsuruha Holdings, this measure often reflects how confident the market feels about the durability of profits and the trajectory of future earnings growth rather than just the latest half year result.
Here, the market is assigning Tsuruha Holdings a richer tag. The current P/E of 18.8x is higher than the peer average of 15.6x and also above the broader JP Consumer Retailing industry on 12.8x. The estimated fair P/E sits slightly lower at 18.3x. That gap suggests investors are already pricing in a reasonable portion of the forecast 12.33% annual earnings growth, and the valuation could move closer to the fair ratio if those expectations change.
Explore the SWS fair ratio for Tsuruha Holdings.
Result: Price-to-earnings of 18.8x (OVERVALUED)
Still, the reset dividend and softer earnings per share leave Tsuruha Holdings exposed if consumer demand weakens further or if execution on cost control disappoints.
Find out about the key risks to this Tsuruha Holdings narrative.
Another view on Tsuruha Holdings’ value
While the P/E of 18.8x paints Tsuruha Holdings as expensive, the SWS DCF model points in the opposite direction. On that cash flow view, the shares at ¥2,175 trade around 68.3% below an estimated value of ¥6,851.28. This raises a simple question: Is the market being cautious or impatient?
Look into how the SWS DCF model arrives at its fair value.
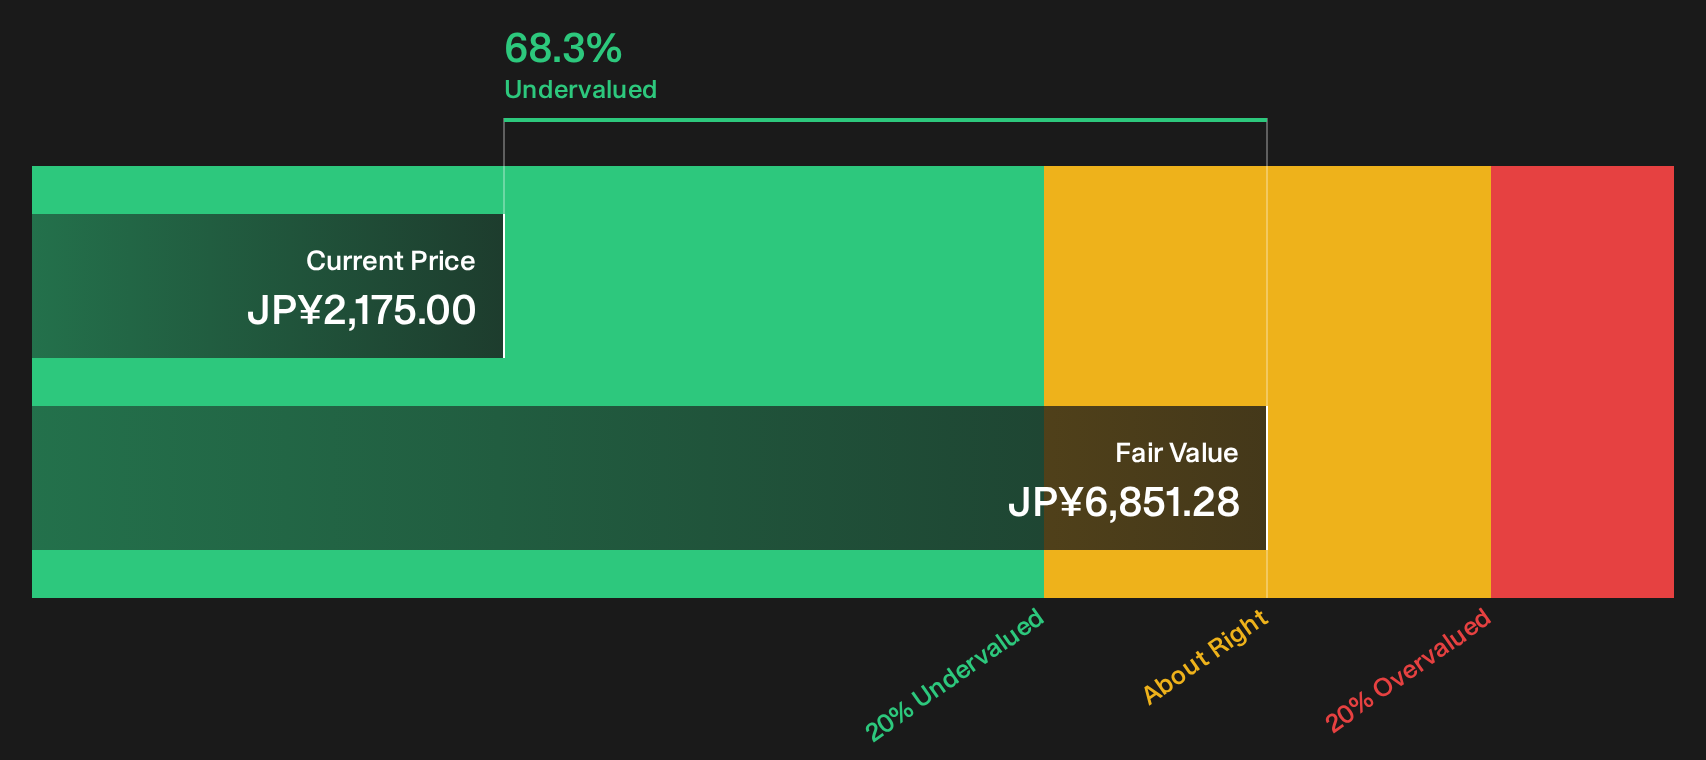
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tsuruha Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Tsuruha Holdings can easily pull you in either direction, so move quickly, sift through the data, and decide where you stand using the 4 key rewards and 2 important warning signs.
Looking for more Tsuruha Holdings style investment ideas?
If Tsuruha Holdings has your attention, do not stop there. Use these focused filters to quickly surface more stocks that match the kind of profile you want.
- Target resilience by scanning a 21 resilient stocks with low risk scores that highlights businesses with steadier risk scores and fewer financial red flags.
- Hunt for value by running a 72 high quality undiscovered gems that surfaces under-followed companies with solid underlying fundamentals.
- Prioritise balance sheet strength by reviewing a list of solid balance sheet and fundamentals (21 results) that points you toward financially sturdier opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com