
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
M/I Homes (MHO) Faces Earnings Pressure, Is The Stock Undervalued?
M/I Homes (MHO) is back in focus after its stock lagged both its sector and the broader market, as investors brace for the October 21 earnings report and anticipated pressure on earnings and revenue.
M/I Homes has seen momentum cool, with the 30-day share price return down 11.46% and the 90-day share price return down 15.72%, even after a 2.06% gain over the last session to US$126.02. That softer trend contrasts with a much stronger 3-year total shareholder return of 66.76% and a 5-year total shareholder return of 103.55%. This suggests that recent weakness may be more about fading near term confidence as investors react to expectations for lower earnings and revenue, rather than a clear verdict on the longer term story.
Scan beyond M/I Homes and stress test your thesis against a curated 32 high quality undervalued stocks list that includes companies with stronger recent momentum or more resilient sentiment profiles.
The question now is whether M/I Homes’ recent slide reflects cracks in the underlying business or simply a reset in sentiment that could leave the valuation out of sync.
Preferred P/E of 10x: Is it justified?
On current numbers, M/I Homes changes hands at a P/E of 10x, which puts the recent $126.02 share price in a zone that screens as good value against several benchmarks.
The P/E ratio compares what you pay for each share to the company’s earnings per share. For a homebuilder like M/I Homes, that lens focuses squarely on how the market is pricing its profit stream rather than its land bank or headline revenue.
Against that backdrop, the stock trades at a lower P/E than both the US Consumer Durables industry average of 12.4x and a peer average of 13.9x, which points to investors applying a clear discount to M/I Homes’ earnings. At the same time, the estimated fair P/E of 15x suggests the current 10x multiple sits well below a level the market could plausibly move toward if sentiment or earnings expectations shifted.
Explore the SWS fair ratio for M/I Homes.
Result: Price-to-earnings of 10x (UNDERVALUED)
Still, a softer 1-year total return and the recent share price slide could signal investor concern if revenue or net income growth fails to hold up.
Find out about the key risks to this M/I Homes narrative.
Another view on M/I Homes’ value
The P/E argument for M/I Homes points to value, yet the Simply Wall St DCF model sketches an even starker gap. With the shares at $126.02 and the model indicating a future cash flow value of $207.04, the stock screens as materially undervalued on this lens.
Those projected cash flows rely on assumptions about margins and demand that can shift quickly, so it is worth understanding how sensitive that $207.04 figure is to changes in the inputs and your own expectations. Look into how the SWS DCF model arrives at its fair value.
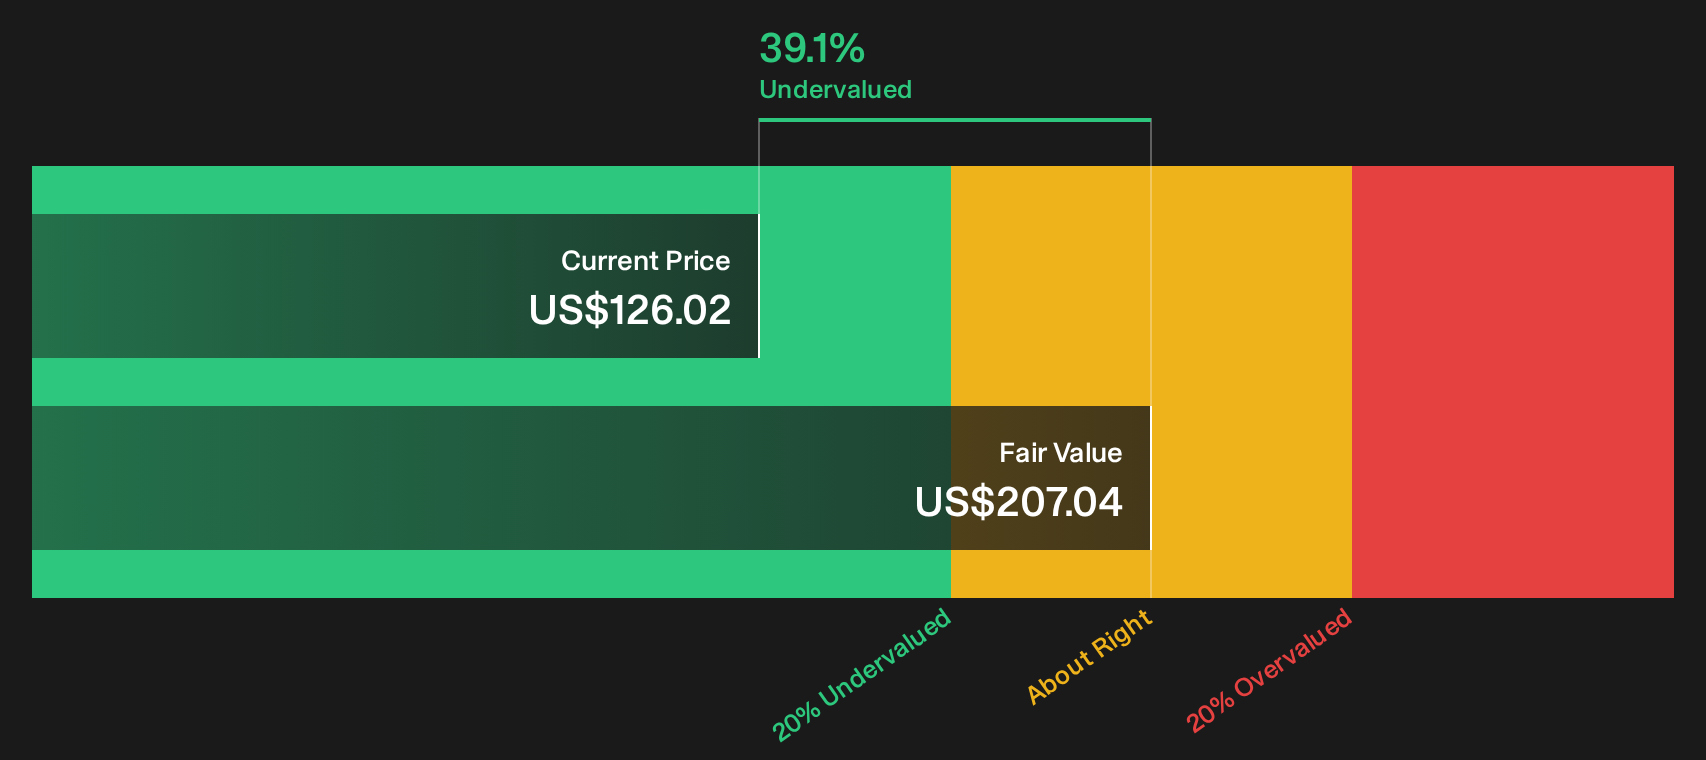
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out M/I Homes for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views about whether M/I Homes is being mispriced or fairly marked down on risk. Act while the data is fresh and pressure test the story for yourself by weighing the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond M/I Homes?
Do not stop your research at M/I Homes. Use the Simply Wall St Screener to spot fresh opportunities that fit your risk tolerance and return goals.
- Target stability first and stress test your watchlist against a 32 resilient stocks with low risk scores that highlights companies with more resilient risk profiles.
- Hunt for quality at a discount by scanning a curated 32 high quality undervalued stocks that filters for stronger fundamentals and more appealing pricing.
- Strengthen your income stream by focusing on a 8 dividend fortresses built around higher yields with the potential for more durable payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com