
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Indigenous Nuclear Project Selection Will Impact BWX Technologies Stock
- Prodigy Clean Energy, Pabineau First Nation and Eel River Bar First Nation selected BWX Technologies' BANR microreactor for an Indigenous-led transportable nuclear power plant in Belledune, New Brunswick, backed by a New Brunswick government Letter of Intent to purchase electricity.
- The Belledune project uses BWX Technologies’ factory-built, modular BANR units and draws on its Canadian manufacturing base and large multi-year backlog. It links microreactor deployment to the firm's broader commercial, industrial and defense pipeline.
- We will look at how BWX Technologies' investment narrative is shaped by this Indigenous-led microreactor project and its growing backlog.
What Is BWX Technologies' Investment Narrative?
To own BWX Technologies, you need to buy into a pretty specific thesis. The business is built around long duration, highly specialized nuclear work, anchored by government operations and supported by commercial projects such as the BANR microreactor. The Belledune TNPP news fits that story. It links BWX Technologies’ existing Canadian footprint and $8.4b backlog to a potential new line of modular, factory built units, but the initial project is relatively small next to the overall order book.
The near term swing factors still look operational. Management has guided to higher 2026 revenue, earnings and free cash flow, with roughly 55% of second half earnings expected to land in the fourth quarter, which increases execution sensitivity. Margin pressure, high capital demands for complex nuclear builds and a leveraged balance sheet all sit in the background. The Belledune project may help long run demand and pricing power, yet it does not remove the fact that BWX Technologies is already priced on a premium P/E and depends heavily on hitting that late year delivery curve.
That said, one trait in BWX Technologies’ setup could quickly turn from manageable to uncomfortable if the timing breaks just a little...
There's only one way to know the right time to buy, sell or hold BWX Technologies. Head to Simply Wall St's company report for the latest analysis of BWX Technologies's Fair Value.
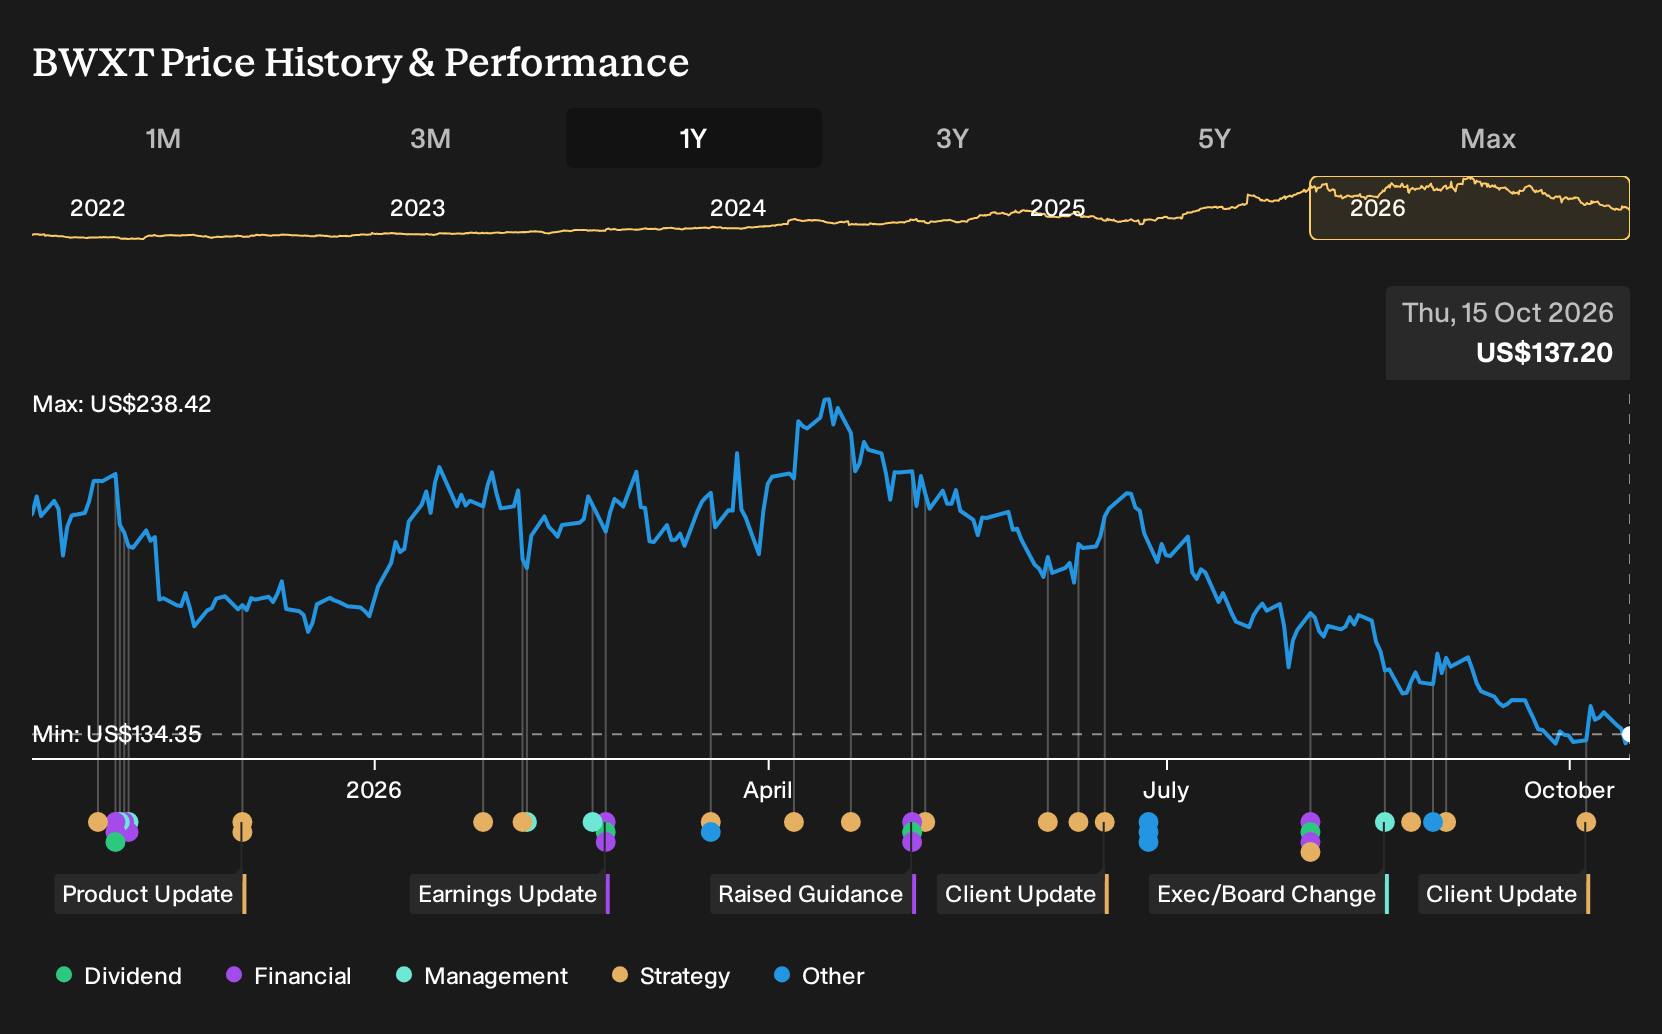
Exploring Other Perspectives
Some of the most optimistic analysts frame this Belledune news against a different catalyst. They already expected BWX Technologies to lift revenue by about 17.6% a year and grow earnings from roughly US$355.2 million to around US$603.7 million by 2029. That is a far brighter story than consensus, and your own view might shift as this project evolves.
Explore 5 other BWX Technologies fair value estimates, including one that suggests as much as 103% potential increase from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your BWX Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BWX Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BWX Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond BWX Technologies?
Once you have formed a view on BWX Technologies, it can help to stack that thesis against other opportunities using the Simply Wall St Screener. That way you can see how this nuclear specialist compares with different types of companies on quality, value and income.
- For investors hunting for resilient businesses with steadier risk profiles, start with a focused set of 32 resilient stocks with low risk scores that score well on volatility and balance sheet checks.
- If dependable income matters most to you, narrow the field to 8 dividend fortresses that combine higher yields with detailed payout and coverage metrics.
- To widen the opportunity set beyond well known tickers, scan through 20 high quality undiscovered gems that pair stronger fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com