
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Ivanhoe Electric (IE) Be A Bargain After Its Santa Cruz Feasibility Study?
Santa Cruz study puts Ivanhoe Electric in focus
Ivanhoe Electric (IE) has moved into the spotlight after publishing a preliminary feasibility study for its Santa Cruz Copper Project in Arizona, outlining project economics that immediately sharpen investor attention.
The preliminary feasibility study has arrived after a tough run for Ivanhoe Electric, with the share price down 46.61% year to date and the 1 year total shareholder return declining 45.78%, even though the 90 day share price return of 7.38% hints at improving momentum.
Scan 16 top copper producer stocks to see how other copper producers compare with Ivanhoe Electric as the market weighs long term demand and project execution risks.
Santa Cruz now carries a US$1.5b after tax NPV against US$1.43b of upfront spend, yet Ivanhoe Electric shares remain well below past levels. Does that equation still tilt the risk reward toward buyers after the recent bounce?
Most Popular Narrative: 59% Undervalued
Against a last close of $8.73, the most followed narrative puts Ivanhoe Electric’s fair value near $21.42, which frames Santa Cruz as the key swing factor for where the stock goes from here.
Santa Cruz is planned as a high grade, first quartile cost copper operation with life of mine cash operating costs of about US$1.47 per pound and an all in sustaining cost of US$2.28 per pound, which could support future net margin potential if copper cathode production and cost targets are met.
See why 1 investors see Ivanhoe Electric as 59% undervalued.
Result: Fair Value of $21.42 (UNDERVALUED)
Still, the Santa Cruz story carries real pressure points, including ongoing losses and the risk that further cost inflation or project delays could upset Ivanhoe Electric’s funding balance.
Find out about the key risks to this Ivanhoe Electric narrative.
Another View on Ivanhoe Electric’s Value
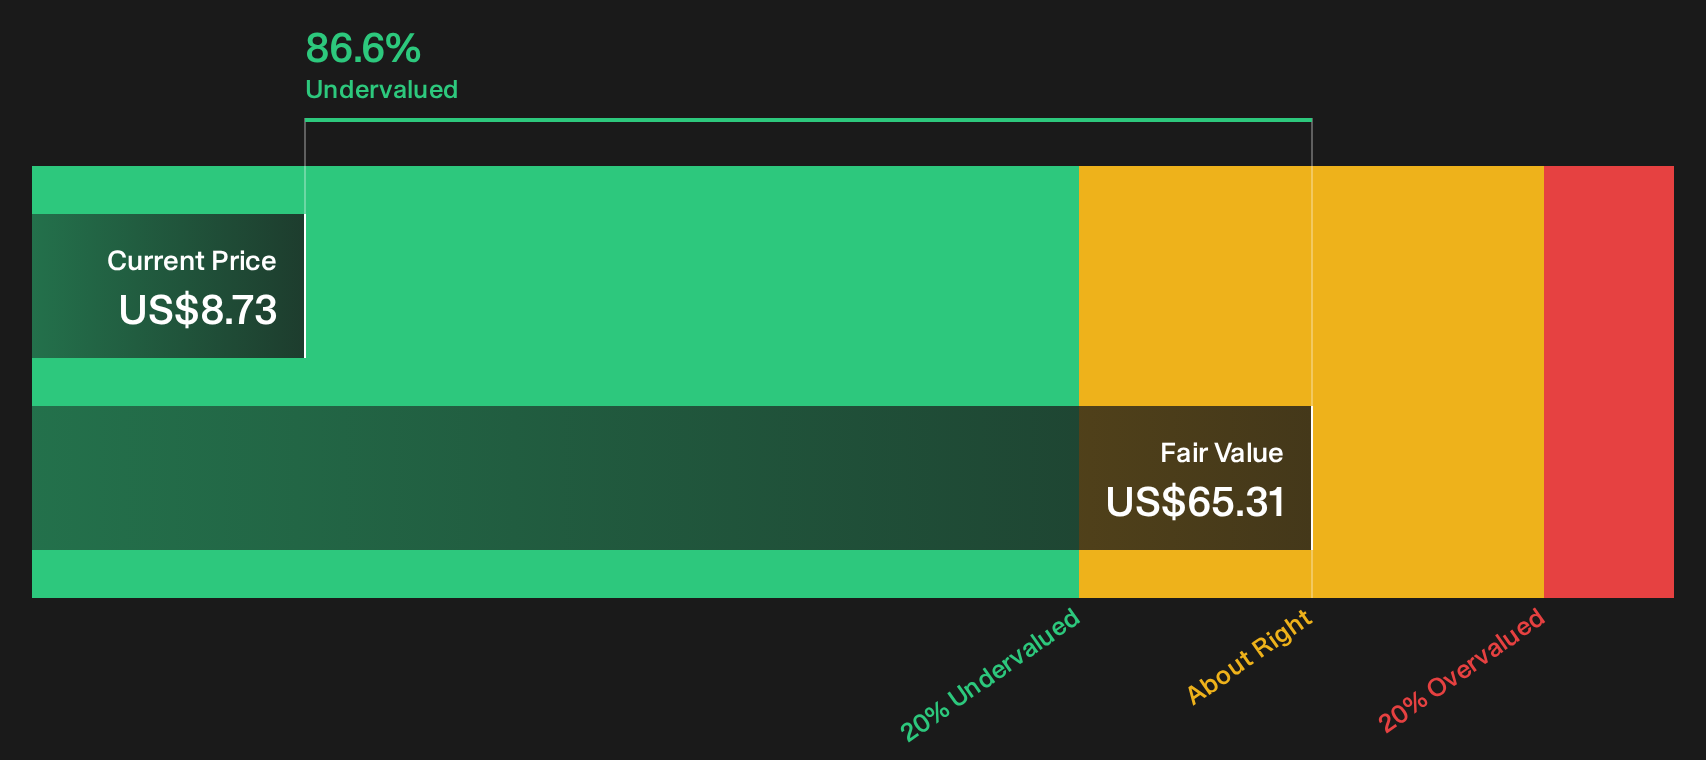
The narrative around Ivanhoe Electric leans heavily on that $21.42 fair value, yet the SWS DCF model paints a far more aggressive picture. On this approach, the future cash flow value sits at $65.31, which flags the stock as deeply undervalued. How comfortable are you with a gap that wide between story and spreadsheet?
To unpack how that cash flow number is built and what would need to go right for it to hold up, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages in the data so far, with both pressure points and bright spots in Ivanhoe Electric’s story, mean speed matters and your own judgment does too. To weigh that balance for yourself, start with the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Ivanhoe Electric?
If Ivanhoe Electric has your attention, do not stop there. Broaden your watchlist with other clear setups that fit different risk, income, and quality preferences.
- Target deep value opportunities by scanning the 32 high quality undervalued stocks that combine strong fundamentals with prices that sit well below intrinsic estimates.
- Secure potential income streams by focusing on the 8 dividend fortresses that offer high yields backed by robust financial profiles.
- Dial down risk while staying invested by shortlisting the 32 resilient stocks with low risk scores that aim for resilience when conditions get choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com