
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nebius Group (NBIS), Why Is The Market Looking Closer Now?
Nebius Group (NasdaqGS:NBIS) has been hit by a sharp repricing, with worries over rising borrowing costs, heavy sector debt and Gartner’s overcapacity warning weighing on AI-focused infrastructure providers.
Nebius Group’s share price has whipsawed, with a 1-day share price return of 1.29% after a 7-day decline of 14.25% and a 30-day fall of 9.14%. However, the year-to-date share price return of 109.46% and 1-year total shareholder return of 53.13% show that longer term momentum is still positive, even as recent sector news and debt concerns have cooled enthusiasm.
Spot opportunities across AI infrastructure by scanning the 70 AI infrastructure stocks that share key themes with Nebius Group’s latest pullback and sector-wide funding pressures.For Nebius Group, bulls point to strong AI cloud contracts and a sharp pullback, while bears focus on heavy debt and overcapacity risk. Which side does the current valuation actually support next?
Most Popular Narrative: 28% Undervalued
Nebius Group last closed at $188.41, while the most followed narrative pegs fair value around $260. That gap is what bulls and bears are really arguing about.
The $260 fair value represents our working estimate of what NBIS could be worth if the company delivers strong AI-cloud growth and improves profitability. It should be treated as an upside target rather than evidence that the shares are clearly cheap, because NBIS trades at approximately 42.3 times sales, compared with a peer average of approximately 9.8 times.
See why 17 investors see Nebius Group as 28% undervalued.
Result: Fair Value of $259.97 (UNDERVALUED)
Still, the story around Nebius Group can flip quickly if AI Cloud utilisation lags capacity build outs or if fresh dilution from funding overwhelms any revenue traction.
Find out about the key risks to this Nebius Group narrative.
Another View On Nebius Group’s Rich Valuation
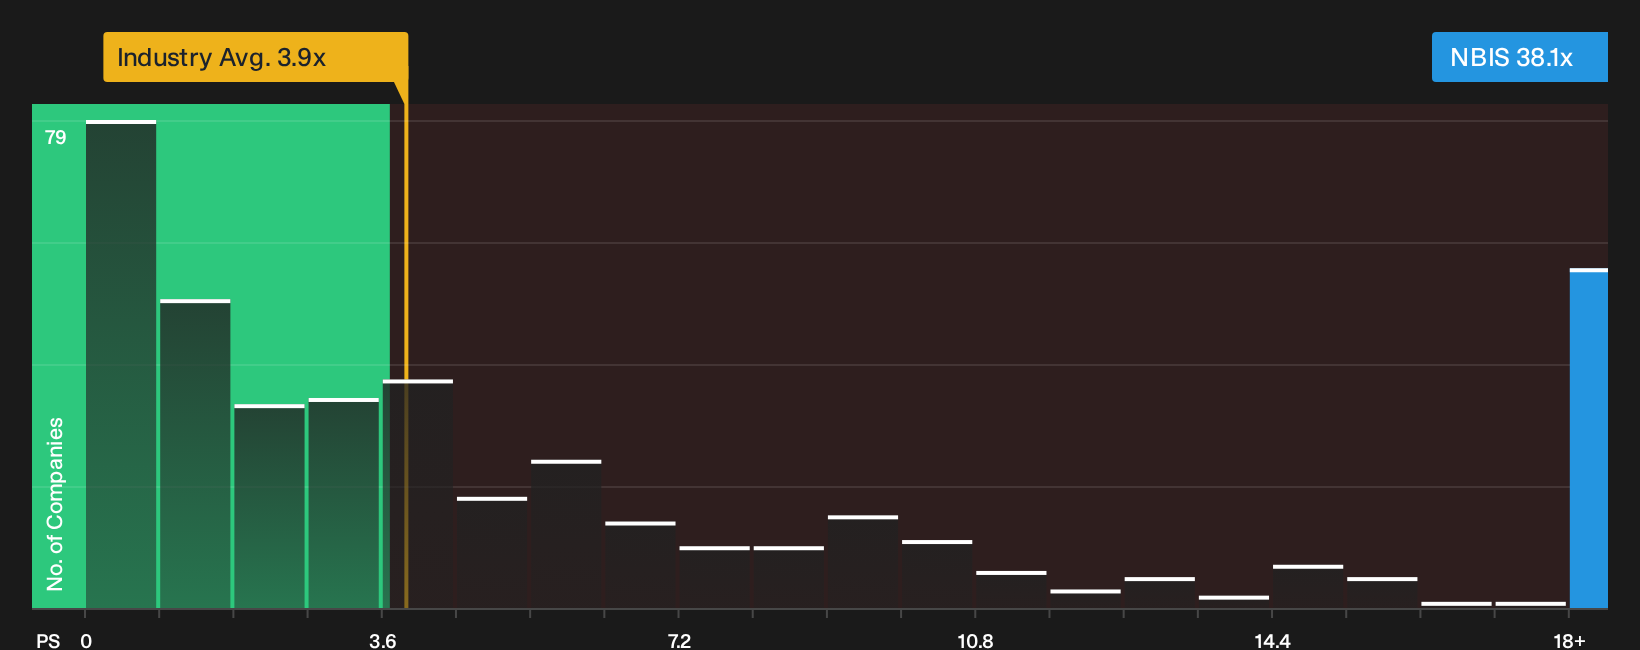
The fair value narrative points to upside for Nebius Group, yet the price tag tells a different story. The stock trades on a P/S of 38.1x, compared with 3.9x for the wider US Software industry and 11.7x for closer peers, while the fair ratio model suggests 36.8x. That kind of premium narrows the margin for error and raises the question of how much good news is already in the price.
To see how that gap between current pricing, peers and the fair ratio could evolve, and what it means for valuation risk, check the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
With sentiment this split around Nebius Group, pricing and risk, you are better off testing the numbers yourself and forming a clear view. To frame that decision with both caution and optimism, weigh the 1 key reward and 4 important warning signs.
Looking for more Nebius Group style investment ideas?
If Nebius Group has sharpened your focus on pricing, risk and upside, do not stop here. Broaden your watchlist with targeted stock ideas built from clear financial criteria.
- Target resilience first and hunt for companies that prioritise balance sheet strength through the list of solid balance sheet and fundamentals (25 results).
- Spot value on your terms and sift through potential bargains with the 32 high quality undervalued stocks.
- Build a steadier income stream and focus on payout strength and durability using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com