
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Behind Altus Group (TSX:AIF) Shares Climbing Today?
Altus Group (TSX:AIF) moved into focus after management lifted its 2026 margin outlook following a strong second quarter, supported by recurring software revenue and a higher adjusted EBITDA margin.
Altus Group’s recent update comes after a sharp swing in sentiment, with the share price up 8.2% over the past month and 5.7% across 90 days, yet still down 12.4% on a year-to-date share price return and showing a 1-year total shareholder return decline of 11.9%, a mixed picture that reflects improving momentum in the short term while longer term holders remain under water.
See how Altus Group compares with other commercial real estate and data-focused plays by reviewing our curated list of list of solid balance sheet and fundamentals (8 results).
Altus Group now trades higher after the guidance reset and margin lift; however, longer term holders still sit on losses. Does the current valuation still skew the risk and reward toward new buyers, or has that window narrowed?
Most Popular Narrative: 4% Undervalued
The most followed narrative puts Altus Group’s fair value at CA$51.33, slightly above the last close of CA$49.44. This frames the stock as modestly discounted rather than deeply mispriced.
Ongoing operational efficiency initiatives (portfolio optimization, offshore global service center, G&A focus) are translating into multi-year margin expansion, with the company targeting approximately 35% segment-level EBITDA margins by 2026. This directly affects profitability and long-term earnings power. A strong balance sheet and a disciplined approach to M&A position Altus to participate in industry consolidation, which may support potential shareholder value creation through strategic acquisitions, scale, and further revenue and earnings growth.
See why 1 investors see Altus Group as 4% undervalued.
Result: Fair Value of CA$51.33 (UNDERVALUED)
Still, subdued transaction activity in commercial real estate and slower uptake of new ARGUS products could pressure Altus Group’s revenue mix and challenge the current margin story.
Find out about the key risks to this Altus Group narrative.
Another View: Altus Group On Sales-Based Valuation
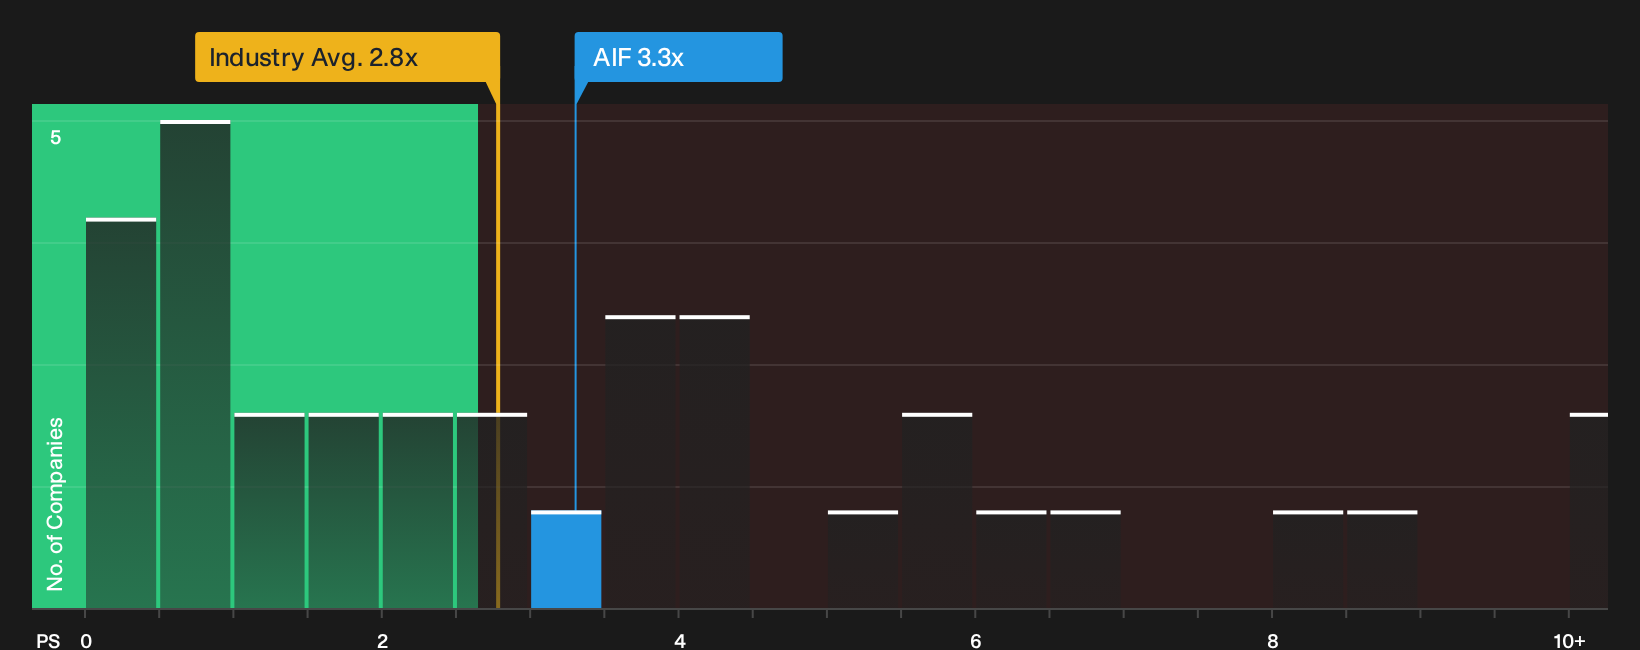
Altus Group screens as undervalued on fair value estimates, yet its current P/S of 3.3x sits above both the Canadian real estate industry average of 2.8x and a fair ratio of 2.8x that the market could move toward over time. That gap points to valuation risk if sentiment cools.
Investors who lean more on comparative pricing than cash flow models may want to see how these numbers stack up against peers in detail before deciding which signal carries more weight for them. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Altus Group leaves you undecided, review the full data set and determine your position based on 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Altus Group?
If Altus Group has sharpened your thinking, broaden your watchlist with fresh ideas that match your risk profile, return goals, and preferred business quality.
- Target resilient balance sheets and steady fundamentals by scanning our curated list of solid balance sheet and fundamentals (8 results).
- Hunt for potential value opportunities by focusing on companies flagged as 6 high quality undervalued stocks.
- Spot potential future winners early by reviewing a focused group of 10 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com