
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ScanSource (SCSC) Stock May Be Reasonable Given Its Cash Flow Outlook
ScanSource has delivered a strong share price run in recent years, which naturally raises a tougher question for you as an investor: Is the current US$60.44 price adequately supported by the cash flows the business is expected to generate?
- The stock has returned 89.8% over the past 3 years, which puts real weight on whether that gain is grounded in the underlying cash generation of the business.
- The company’s model as a technology distributor depends heavily on converting earnings into dependable free cash flow, which can shape how sustainable its reinvestment plans and shareholder returns may be.
- What if you looked at ScanSource through its earnings instead? See what ScanSource's 15.4x P/E says about the price.
The issue now is whether ScanSource’s recent share price level lines up with what its cash flows suggest the intrinsic value should be.
If you are weighing whether ScanSource’s US$60.44 price lines up with its cash flows, it can help to sanity check that logic against 32 high quality undervalued stocks
Is ScanSource a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash ScanSource can return to shareholders over time. Latest twelve month free cash flow sits at about $114.3 million, which gives the DCF a cash rich starting point rather than a turnaround story built on losses.
Looking ahead, the projections factor in free cash flow that is expected to grow into the medium term, then settle into relatively modest declines before stabilising. On those assumptions, the DCF output comes in modestly above the current US$60.44 share price. This suggests the market price may not fully reflect the projected cash generation based on these inputs. That gap and the cash profile are what you are really comparing when you weigh ScanSource against alternatives. Find out what ScanSource could be worth using our Discounted Cash Flow (DCF) estimate.
The ScanSource Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where the ScanSource valuation puzzle leaves off by mapping out which combinations of future growth, margins and earnings would need to hold for the shares to be worth materially more or less than today’s price. Rather than stopping at a single DCF output or valuation ratio, Narratives shows the future path that figure rests on so you can watch ScanSource's actual progress against those conditions over time on the Community page.
One of the top community narratives on ScanSource: roughly fairly valued
"Growing demand for cloud compute, connectivity and CX solutions, together with ScanSource's focus on helping partners sell more cloud recurring revenue…"
Discover why this Narrative puts ScanSource at roughly fairly valued.
One more ScanSource question that could change how you see this valuation
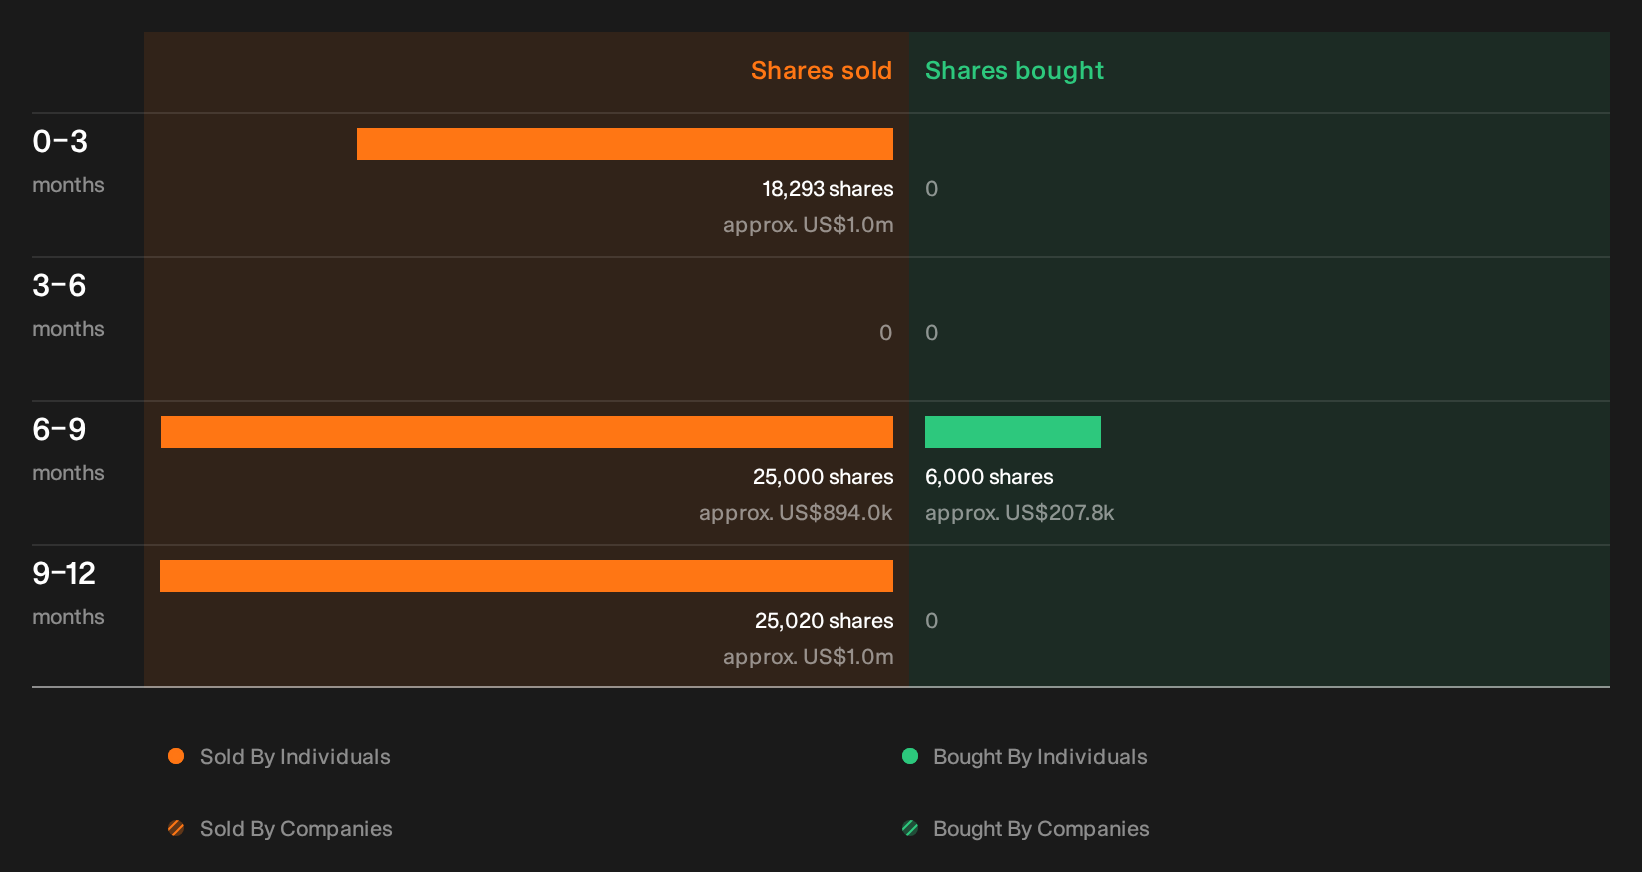
Our checks have picked up recent selling by people on the inside. The real story sits in who sold, how much, and what that might signal for you to weigh. See the recent insider selling flagged for ScanSource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com