
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Barratt Redrow (LSE:BTRW) Rises On Rate Relief But Is The Recovery Already Priced In
Barratt Redrow (LSE:BTRW) climbed after investors responded to falling gilt yields and more cautious Bank of England commentary on future rate moves, which supported interest rate sensitive housebuilder and wider property shares.
Recent trading has turned more positive for Barratt Redrow, with a 1-day share price return of 1.94%, a 7-day gain of 6.38% and a 30-day increase of 12.16%. However, the year-to-date share price return is down 18.21% and the 1-year total shareholder return has declined 18.79%, indicating improving short-term momentum against a still weak longer-term record.
Spot fresh momentum across rate sensitive builders by scanning the hand picked list of solid balance sheet and fundamentals (9 results).Barratt Redrow appears to be a solid UK housebuilding group with growing revenue and profit, yet the share price has only just bounced after a weak multi year run. Is that recent optimism already reflected in the valuation?
Most Popular Narrative: 6.5% Undervalued
Barratt Redrow last closed at £3.10, while the most followed narrative pegs fair value around £3.32. The current move still sits below that reference point and leans on execution of the merger story.
The combination of Barratt and Redrow has created opportunities for cost and revenue synergies, with cost synergies upgraded from £90 million to £100 million. This is expected to positively impact net margins in the future.
See why 67 investors see Barratt Redrow as 7% undervalued.
Result: Fair Value of £3.32 (UNDERVALUED)
Still, integration hurdles and planning delays around Barratt Redrow's enlarged land bank could squeeze margins and slow outlet growth, which may put that 6.5% undervaluation thesis under pressure.
Find out about the key risks to this Barratt Redrow narrative.
Another View: Barratt Redrow Through A Cash Flow Lens
The analyst narrative points to around 6.5% upside to £3.32, yet the SWS DCF model paints a much cooler picture. On that cash flow based view, Barratt Redrow looks overvalued, with a future cash flow value of about £2.09 against a £3.10 share price. Which framework feels closer to how you judge risk and reward?
Look into how the SWS DCF model arrives at its fair value.
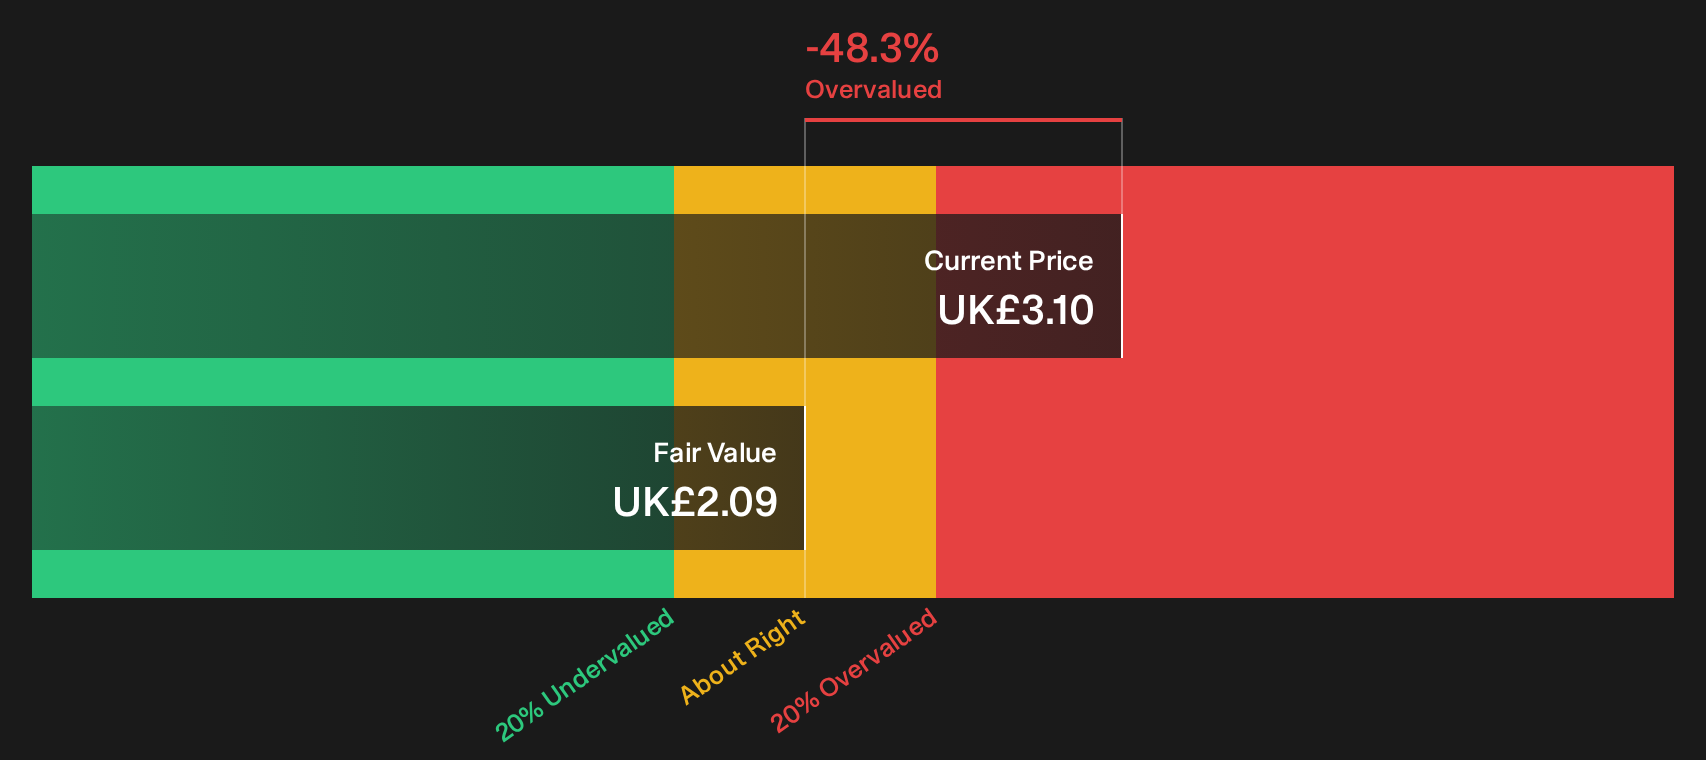
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barratt Redrow for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 9 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Barratt Redrow can be useful if you turn them into your own framework. Move quickly from reading to testing your thesis with 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Barratt Redrow?
Once you have a view on Barratt Redrow, the next smart move is widening your watchlist with a few focused hunting grounds for opportunities.
- Target potential mispriced opportunities by scanning our hand picked 9 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- Strengthen your income stream by checking out a curated set of high yield payers inside the 4 dividend fortresses that still emphasise balance sheet support.
- Dial down portfolio stress by focusing on companies with steadier profiles through the 4 resilient stocks with low risk scores that filters for more resilient risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com