
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Biohaven (BHVN) Could Be 70% Undervalued Following The Ono Licensing Deal
Biohaven (BHVN) is back in focus after the company signed a licensing and collaboration deal with Ono Pharmaceutical covering its MoDE IgG degrader portfolio across key Asian markets.
Biohaven’s licensing announcement landed alongside a sharp 1 day share price gain of 4.57% to US$11.43, following a far weaker patch in which the 90 day share price return fell 25.97% and the 1 year total shareholder return declined 30.64%. Recent momentum is therefore picking up from a low base.
See how Biohaven’s move compares with other under-the-radar biopharma plays by reviewing our curated list of 20 high quality undiscovered gems that are also reacting to fresh catalysts.
Biohaven now pairs a broad late stage pipeline and fresh Ono cash inflow with a share price that has been weak over 1 and 3 years. Does that disconnect point to a bargain or a value trap?
Most Popular Narrative: 70% Undervalued
The most followed narrative values Biohaven at $38.35 per share, well above the last close at $11.43. This frames the Ono deal inside a much bigger late stage story.
The up to US$795m global licensing agreement for the Kv7 ion channel platform with SK Biopharmaceuticals, which includes tiered U.S. sales royalties, introduces an external commercialization route that can add milestone income and capital efficient revenue without fully burdening Biohaven’s own operating costs.
See why 0 investors see Biohaven as 70% undervalued.
Result: Fair Value of $38.35 (UNDERVALUED)
Still, the bullish Biohaven story can unravel if the partial clinical hold on opakalim tightens or if heavier than expected cash burn forces more dilution.
Find out about the key risks to this Biohaven narrative.
Another View: Biohaven Looks Expensive On P/B
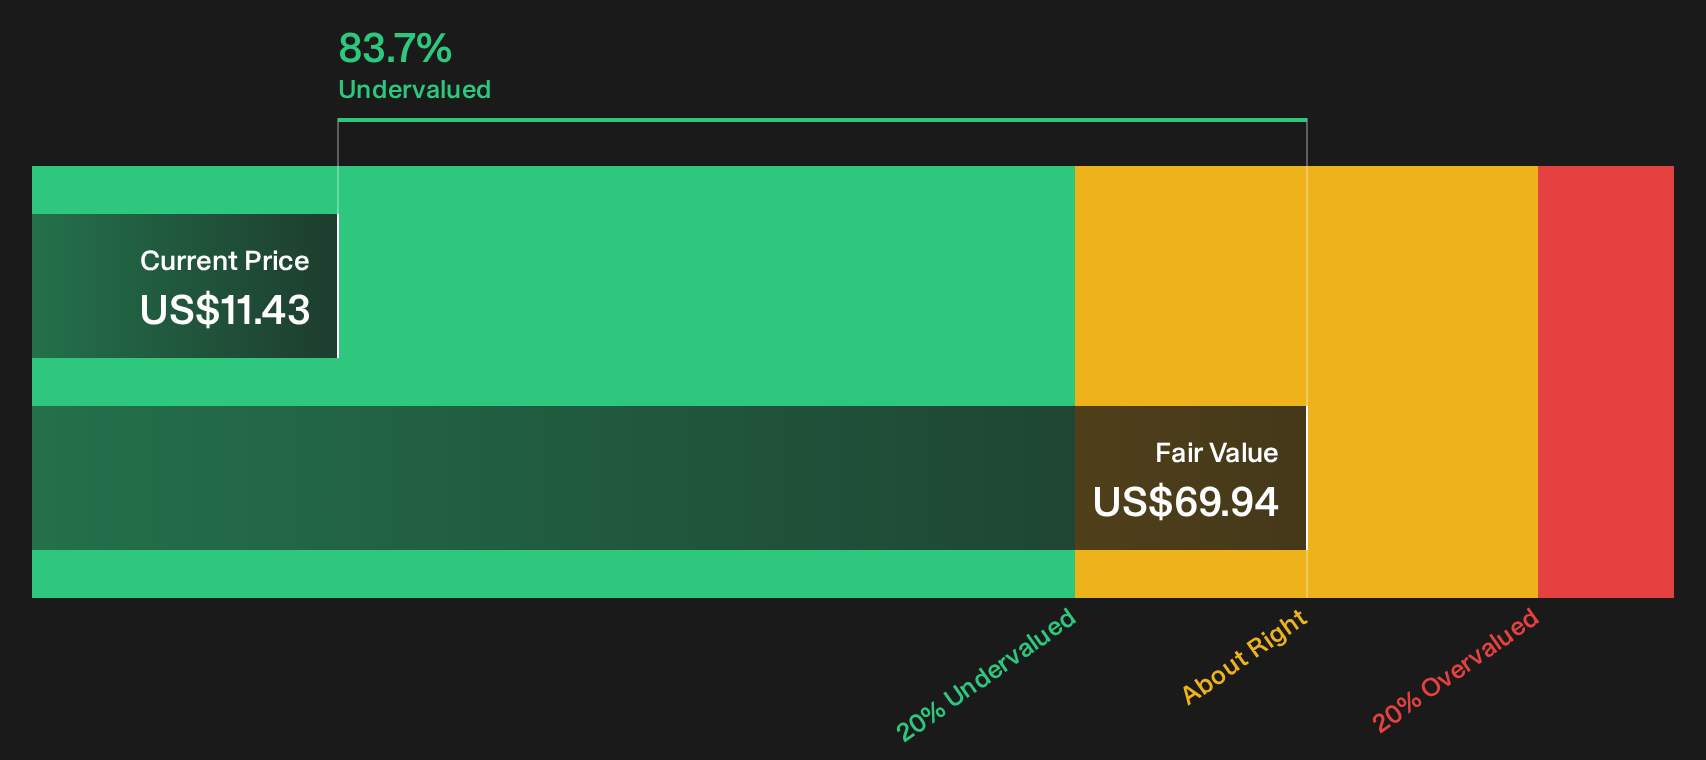
While our DCF model flags Biohaven as trading well below an estimated future cash flow value of $69.94 per share, the simpler P/B snapshot paints a very different picture. The stock trades on a P/B of 141.3x versus 1.9x for the US Biotechs industry and 8x for peers, which points to a lot of expectation already in the price. Which yardstick do you trust more for a pre-revenue pipeline story like this?
To understand how this kind of disconnect can appear when earnings are still negative, and what the current multiple might be implying about long term outcomes, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Biohaven’s value story can be confusing. Consider reviewing the data for yourself, then weigh the 2 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Biohaven?
If Biohaven’s story has you thinking about what else might be hiding in plain sight, you can use that curiosity to widen your opportunity set with a few focused screens.
- Target resilient balance sheets and solid fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) to identify companies with stronger financial footing.
- Explore potential value gaps by running through the 32 high quality undervalued stocks that combines quality metrics with prices that may not yet fully reflect them.
- Evaluate potential income streams by reviewing a curated 8 dividend fortresses that already clears a 5% yield hurdle and focuses on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com