
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Corpay (CPAY) Earnings Track Record Keeps Valuation In Focus After Client Deal Extension
Client deal extension and earnings track record put Corpay in focus
Corpay (CPAY) recently extended its exclusive role as the World Baseball Softball Confederation’s foreign exchange payments provider, while fresh analyst commentary highlights the group’s history of topping earnings estimates.
Recent moves in Corpay’s share price have been strong, with a 1-day share price return of 3.35% and a year-to-date share price gain of 35.13% at a last close of US$406.20. The 1-year total shareholder return of 46.38% and 3-year total shareholder return of 67.87% point to momentum that investors appear to be linking to both deal wins and consistent delivery against earnings expectations.
Scan for other payment and financial platforms showing similar momentum and earnings delivery traits by reviewing the curated 32 high quality undervalued stocks in comparison with Corpay.
Corpay now trades near US$406 while the published analyst target and one intrinsic value estimate sit meaningfully higher. How much of that gap reflects genuine upside versus optimism after a strong run?
Most Popular Narrative: 12% Undervalued
Corpay’s most followed narrative anchors on a fair value of $461 per share, which sits above the recent $406.20 close and frames the current rally as only part of the story.
Corpay's continued expansion of its international cross-border platform, now supported by the migration of most Alpha volume onto a single global system and the addition of tokenized settlement rails through partners such as JPMorgan's Kinexys and BVNK, is expected to widen addressable payment flows and support future revenue and margin growth.
See why 14 investors see Corpay as 12% undervalued.
Result: Fair Value of $461 (UNDERVALUED)
Still, the Corpay story carries real pressure points, including the proposed US$100 million U.S. Vehicle Payments settlement and any shortfall versus the analysts’ ambitious margin targets.
Find out about the key risks to this Corpay narrative.
Another View: Corpay through the earnings multiple lens
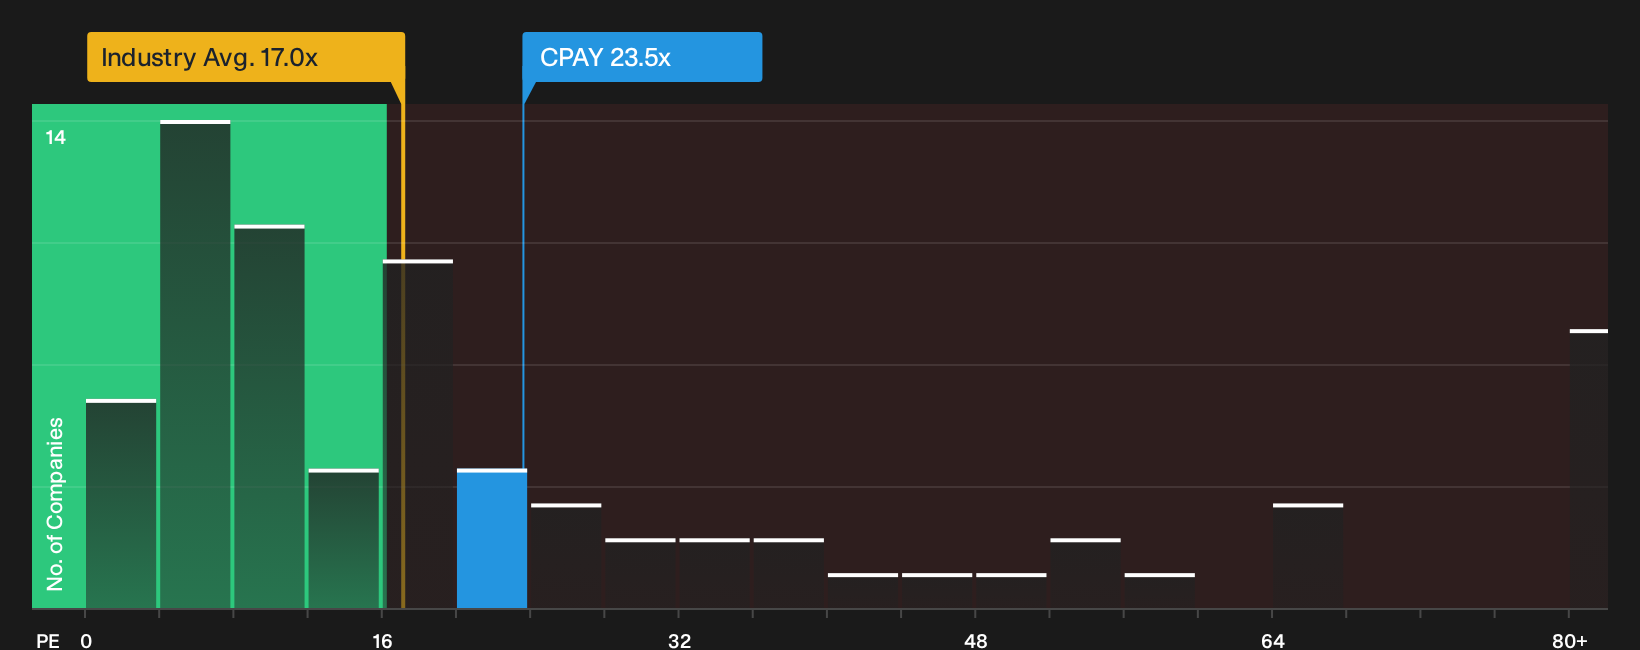
Corpay may appear inexpensive relative to one fair value estimate of $699.95 based on future cash flows, yet the current P/E of 23.5x suggests a different perspective. That valuation is higher than the US Diversified Financial industry at 17x and above an estimated fair ratio of 16.8x, which indicates there may be less margin for error if sentiment cools.
Anyone weighing these mixed signals might ask which yardstick should carry more weight when expectations reset.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Corpay leaves you undecided, review the underlying numbers quickly and form your own stance with 3 key rewards and 2 important warning signs.
Looking for more Corpay-like investment ideas?
Corpay might already be on your radar, but limiting yourself to a single opportunity can mean missing other strong setups that fit your approach just as well.
- Target value with quality by scanning a focused pool of strong fundamentals and potential mispricing through the 20 high quality undiscovered gems.
- Shield your portfolio from heavy shocks by filtering for companies with sturdier finances using the list of solid balance sheet and fundamentals (25 results).
- Prioritise resilience and sleep-better-at-night holdings by zeroing in on stocks screened for stability with the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com