
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Orora (ASX:ORA) Flags Saverglass Impairment, Is It Still Below Fair Value?
AGM spotlight on Saverglass and FY27 earnings guidance
Orora (ASX:ORA) put the troubled Saverglass acquisition at the centre of its recent AGM, flagging a substantial impairment and guiding investors to lower Group EBIT for FY27, despite firmer expectations for the Cans division.
At A$1.35, Orora’s recent AGM commentary on Saverglass and the FY27 earnings guidance arrived after a difficult run, with the share price down 39.19% year to date and the 1 year total shareholder return declining 30.06% as investors reassess both execution risk and longer term earnings quality.
Spot opportunities across the packaging sector by comparing Orora’s setup with our hand picked 4 high quality undervalued stocks, which combine earnings power with balance sheet strength.Orora still owns solid packaging assets across cans and glass, yet the share price reset after Saverglass raises a harder question. Are investors now getting that underlying business strength at a sensible entry point?
Most Popular Narrative: 20% Undervalued
On the most widely followed view, Orora’s A$1.35 share price sits below an estimated fair value of A$1.69. That gap is explained largely by how investors weigh Saverglass risk against the earning power of the Cans and Global Glass operations.
Orora is leveraging sustainability trends and operational efficiency to enhance pricing power, support margin expansion, and strengthen its competitive position in packaging markets. The acceleration of e-commerce and direct-to-consumer trends is driving heightened demand for transit and protective packaging, underpinning continued strong volume growth in Orora's Cans division and supporting incremental EBIT from newly commissioned and upcoming capacity expansions.
See why 26 investors see Orora as 20% undervalued.
Result: Fair Value of A$1.69 (UNDERVALUED)
Still, this narrative can break quickly if Saverglass faces prolonged demand softness, or if higher glass and can capacity ends up underused and drags on returns.
Find out about the key risks to this Orora narrative.
Another view on Orora’s valuation
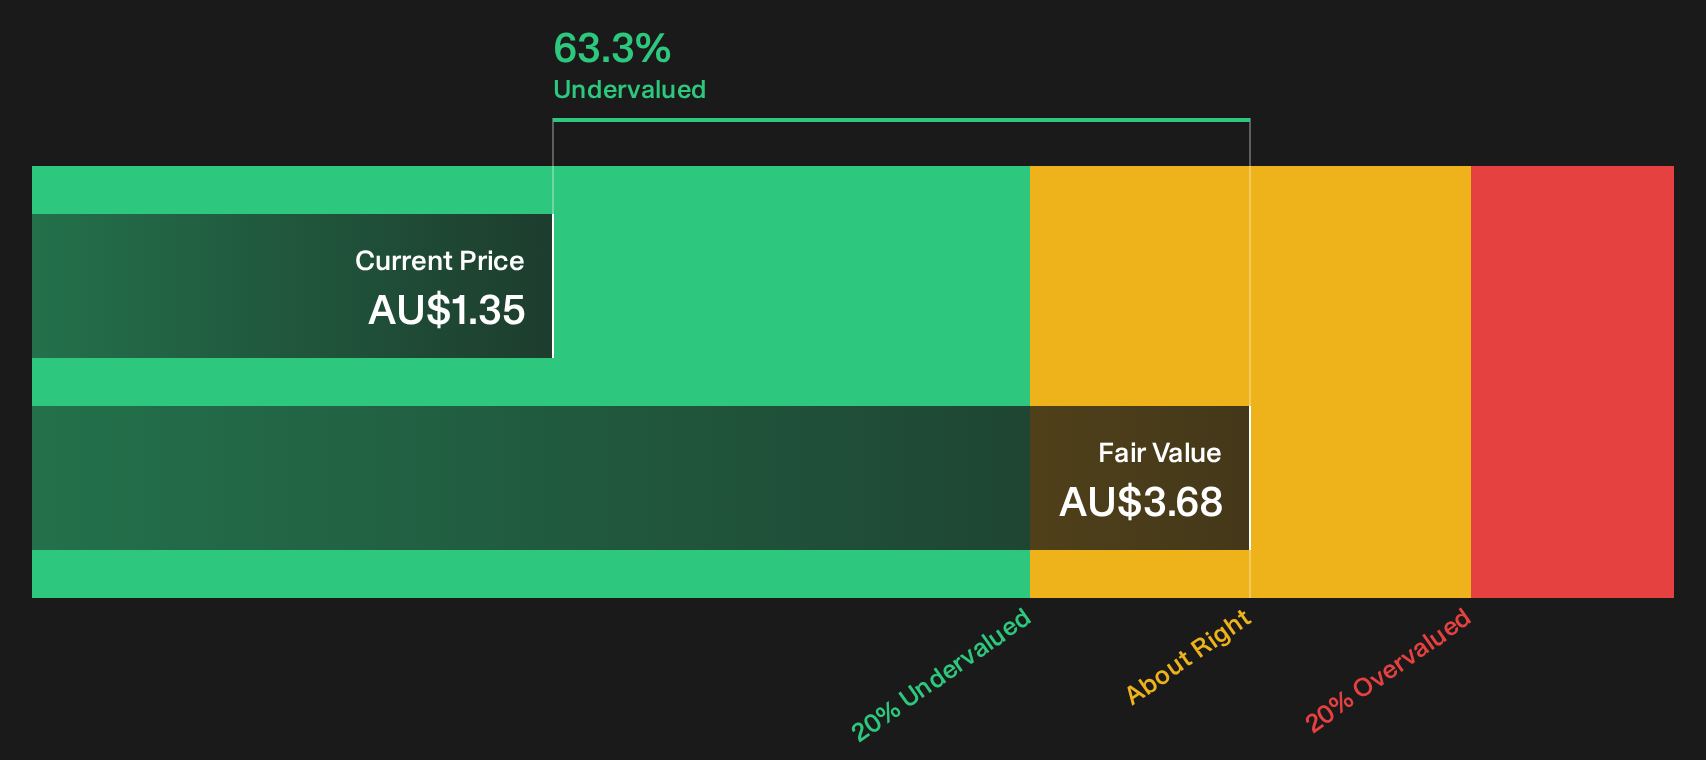
The earlier narrative leans on analyst targets and earnings expectations. A different lens comes from the SWS DCF model, which puts Orora’s future cash flow value at A$3.68 per share versus the current A$1.35 price. That is a much deeper undervaluation signal. What if the cash flow math is closer to reality than the sentiment hit from Saverglass?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Orora’s valuation, risks, and rewards can feel messy. Move fast, review the data yourself, and weigh up the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Orora?
Orora is only one packaging story on your radar. Use this as a benchmark, then broaden your opportunity set with a few focused stock lists.
- Target resilience first by scanning a 6 resilient stocks with low risk scores that filters for businesses with lower overall risk scores and more durable profiles.
- Hunt for pricing power by reviewing a 15 high quality undiscovered gems that highlights under-the-radar companies with strong fundamentals that many investors overlook.
- Strengthen your core holdings by working through a list of solid balance sheet and fundamentals (12 results) that focuses on stocks with healthier financial foundations.
Skip the noise, run these screeners now, and review a clearer set of ideas before the next round of headlines reaches your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com