
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Nevada Buildout Progress Require Action From i-80 Gold (TSX:IAU) Investors?
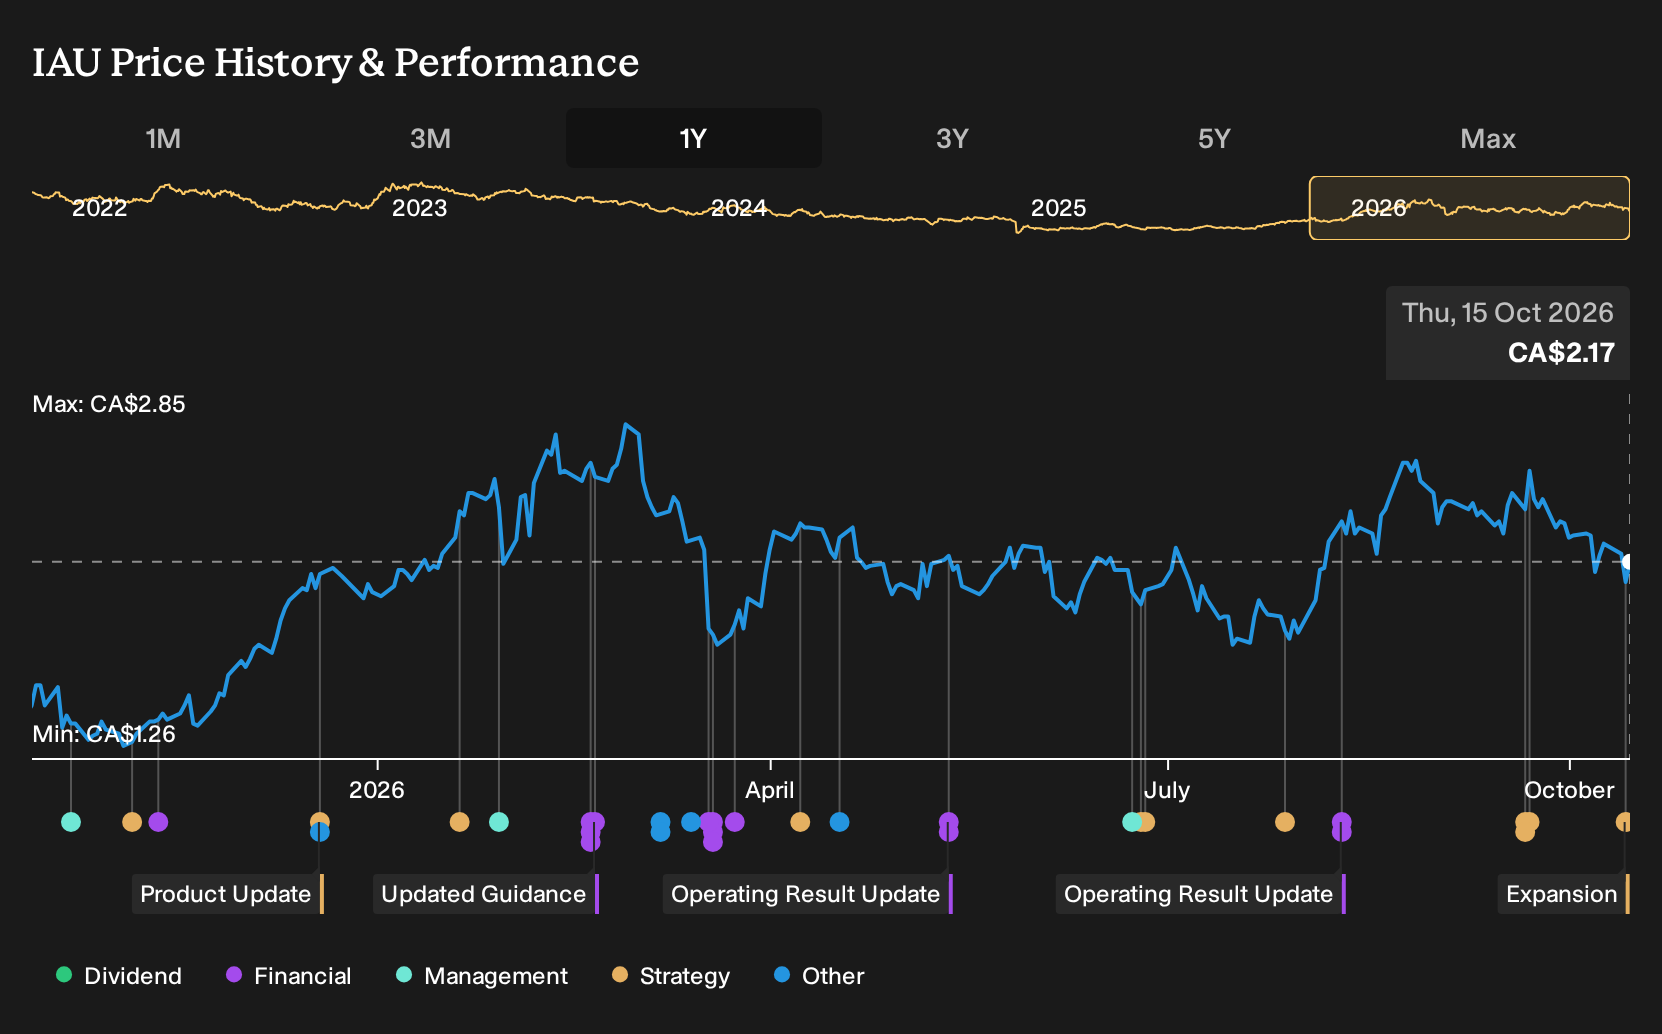
- i-80 Gold updated its Nevada development plan, confirming progress at Archimedes underground and the Lone Tree processing plant while prioritizing the large Mineral Point open pit as the next major build after its hub and spoke platform is in place.
- The company reports Lone Tree refurbishment costs and timing tracking its December 2025 engineering study, with contingencies absorbing higher labor expenses and roughly 44% of the planned US$430 million capital already committed.
- We will now examine how i-80 Gold's investment narrative could be influenced by prioritizing Mineral Point as the next large project.
i-80 Gold Investment Narrative Recap
To own i-80 Gold, you need to believe the Nevada hub and spoke buildout can move from construction story to operating portfolio without major disruption. The latest update keeps that belief intact. Lone Tree refurbishment is tracking its December 2025 study, Archimedes underground is still pointed at first mining in late 2026, and Mineral Point is now firmly framed as the next large build.
The main near term catalyst remains clear progress at Lone Tree and the underground mines, because that is what underpins a shift away from toll milling and persistent losses. Execution risk on multiple high capex projects stays the biggest threat. Cost control, permitting discipline and schedule stability matter more than this specific sequencing tweak.
The most relevant fresh detail is the confirmation that Lone Tree refurbishment costs and timing remain in line with the US$430 million engineering study, with around 44% of that capital already committed and only about 10% of contingency used. For you, that speaks directly to whether this processing hub can be delivered without a material capital surprise.
Those project metrics feed straight into the catalyst timeline investors watch. A functioning Lone Tree plant processing Granite Creek and Archimedes material is what could change i-80 Gold from a high spend developer to an integrated producer. Any slippage in construction, labor inflation beyond contingency or slower ramp could weigh on that transition and keep financing and dilution risk front and center.
i-80 Gold's narrative projects $752.0 million revenue and $268.7 million earnings by 2029. This implies 79.5% yearly revenue growth and an earnings swing of about $527.3 million, from a loss of $258.6 million today to the 2029 consensus level.
Uncover why i-80 Gold's fair value indicates a 90% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative view focuses on upside from Mineral Point rather than execution risk. The most optimistic analysts were already pencilling in revenue of about $1.3b and earnings near $512.4 million by 2029 for i-80 Gold. That is far above the $752.0 million and $268.7 million consensus, and this development plan update could eventually shift those narratives again.
Explore 3 other i-80 Gold fair value estimates, including one that suggests as much as 153% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your i-80 Gold research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for i-80 Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate i-80 Gold's overall financial health at a glance.
Looking for more ideas beyond i-80 Gold?
If you want to stress test your thesis on i-80 Gold against other opportunities, it helps to scan a wider universe of companies using the Simply Wall St Screener.
- If you care most about valuation and quality together, compare i-80 Gold with a wider set of businesses trading on what you judge to be attractive terms by running your filters through 6 high quality undervalued stocks.
- If capital preservation comes first for you, focus on companies with steadier risk profiles by scanning our universe for 8 resilient stocks with low risk scores.
- If balance sheet strength is non negotiable, set your bar high and sort through a list of solid balance sheet and fundamentals (8 results) to see which ones deserve a place on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com