
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Centerra Gold (TSX:CG) Quebec Exploration Deal
- Azimut Exploration reported that Centerra Gold can earn up to a 70% interest in the Corvet and Kaanaayaa gold copper properties in Quebec by funding US$16,000,000 of exploration and up to US$850,000 in cash payments tied to a staged work program and a future PEA.
- The agreement gives Centerra Gold partner-funded access to a large, underexplored 556.3 km² land package, which could influence how investors view its long-run exploration pipeline and resource replacement options beyond existing projects.
- We will now look at how Centerra Gold's broader investment narrative might be affected by this large Quebec exploration option agreement.
Centerra Gold Investment Narrative Recap
To own Centerra Gold, you effectively need to believe current mines like Mount Milligan and Öksüt can support the project pipeline long enough for new assets to matter. The Azimut option fits that view as long term exploration optionality, but it does not change the near term focus on execution at existing operations and cost control.
The key near term swing factor still sits with production stability, ore grade predictability and all in sustaining costs across the portfolio. Major risks remain concentrated in Mount Milligan geology, Turkish royalty exposure at Öksüt and the capital and execution burden of bringing projects like Goldfield, Kemess and Thompson Creek through studies and eventual restart decisions.
The Azimut agreement fits alongside Centerra Gold’s multi year growth projects rather than replacing them. Management already has a full queue with the Mount Milligan life extension and throughput work, the Goldfield District build out plans and studies at Kemess and Thompson Creek, all backed by a debt free balance sheet and cash on hand.
Quebec exploration exposure through Corvet and Kaanaayaa adds early stage gold and copper potential, but the real operational catalysts remain closer to the plant. Investors still tend to focus on how reliably Mount Milligan can turn resources into feed, how Öksüt’s royalty burden affects margins and whether upcoming project studies justify the capital needed for the next phase of growth.
Centerra Gold's current analyst story points to revenues of $2.3b and earnings of $503.9m by 2029, built on 10.3% yearly top line growth and an earnings decline of about $132.6m from $636.5m today.
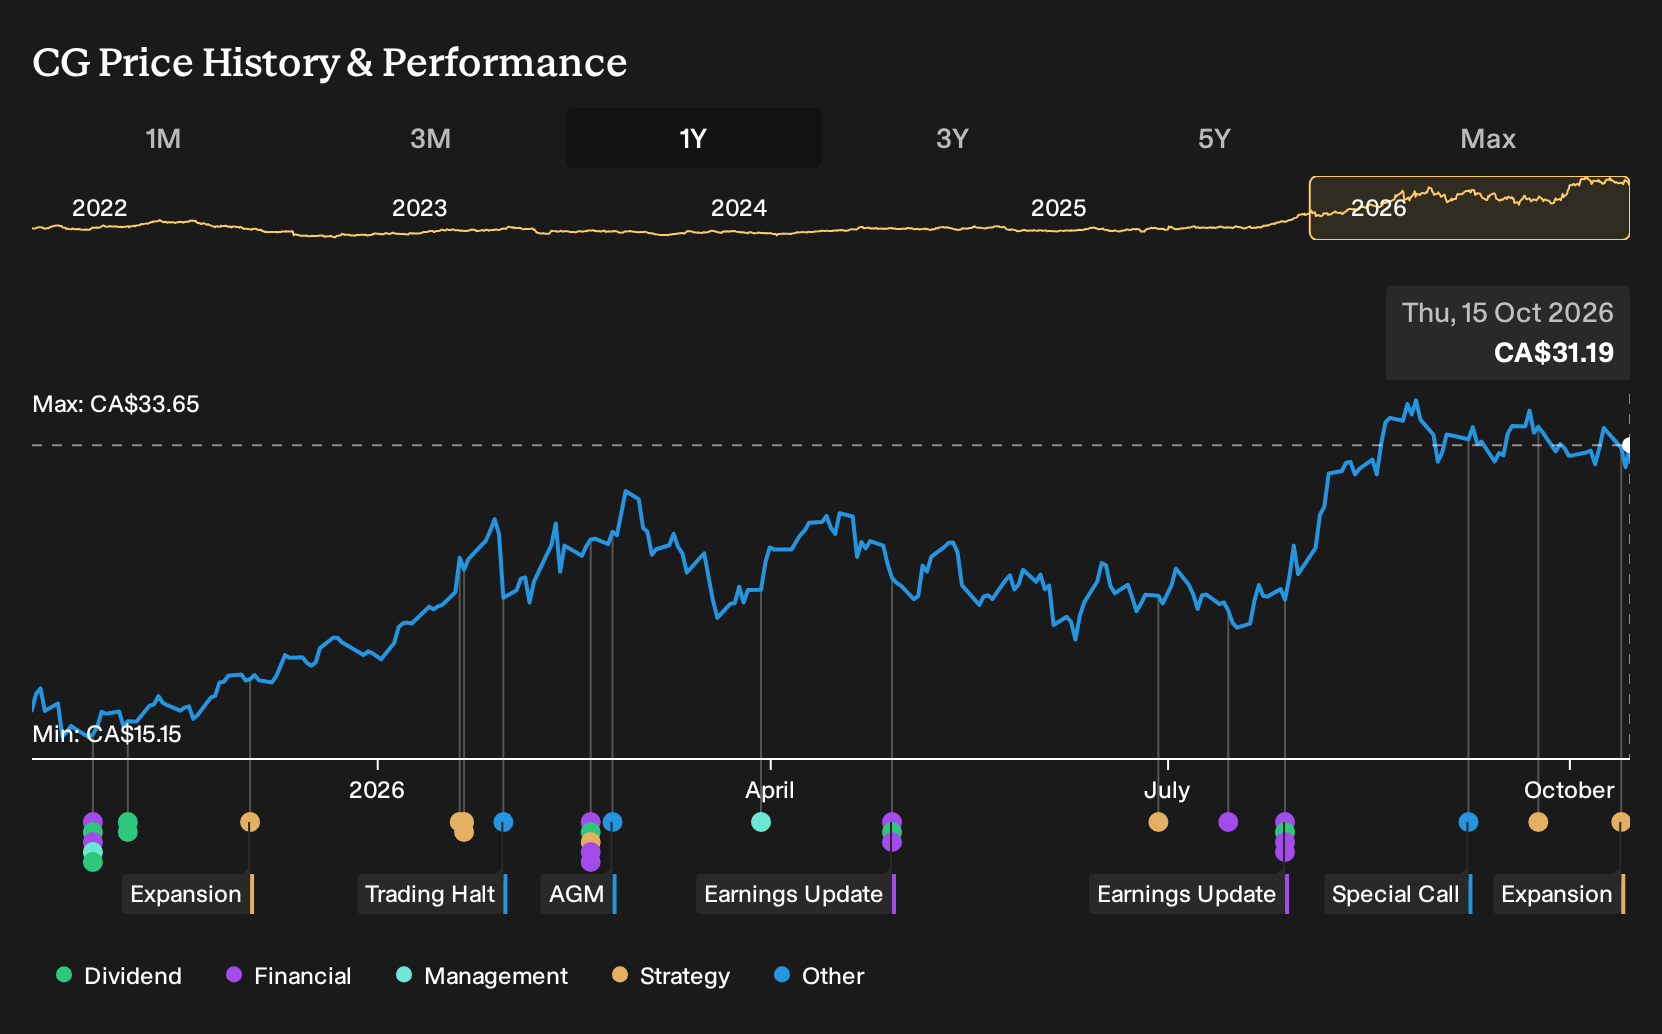
Uncover why Centerra Gold's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Centerra Gold puts funding risk front and center. The most bearish analysts were working off 2029 earnings of about $421.0 million and still assuming roughly $2.3b of revenue before this Quebec deal. You can see how that tighter cash story might shift once the new exploration spend and options are fully reflected.
Explore 3 other Centerra Gold fair value estimates, including one that suggests as much as 58% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Centerra Gold research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Centerra Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Centerra Gold's overall financial health at a glance.
Looking for more investment ideas beyond Centerra Gold?
If you want to put Centerra Gold in context and see how it compares with other opportunities, the Simply Wall St Screener can help you quickly find stocks that fit the kind of risk and return profile you care about most.
- If you want potential value with quality behind it, scan through a hand picked 6 high quality undervalued stocks and see which businesses match your checklist on cash flows and balance sheet strength.
- If capital preservation matters just as much as upside, focus on a 8 resilient stocks with low risk scores that highlights companies with more resilient fundamentals and lower risk scores.
- If you are looking for less crowded opportunities, work through a 10 high quality undiscovered gems that surfaces smaller stocks with solid underlying metrics and less attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com