
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
STERIS (STE) Is Back In The Spotlight, But What Is Driving It?
STERIS (STE) has moved back into focus after agreeing to buy Xodus Medical for about US$2.1b. The deal expands its surgical consumables footprint and adds performance-based earnout terms through 2028.
Recent headlines have come thick and fast for STERIS, from the US$2.1b Xodus Medical deal to plans for a 600,000 square foot facility in North Carolina. However, the share price return tells a more muted story, with the stock up 3.62% over the past week but down 13.11% year to date and the 1 year total shareholder return lower by 7.22%. This suggests investors are still recalibrating expectations around growth potential and acquisition risk.
Capitalize on the renewed focus on STERIS by scanning for other healthcare equipment and services stocks showing resilient fundamentals and potential re-rating setups in our curated list of solid balance sheet and fundamentals (25 results).SterIS has rallied on the Xodus deal news, yet the share price is still down on the year. Is this the start of a re-rating, or has most of the easy upside already passed?
Most Popular Narrative: 17% Undervalued
The most followed narrative on STERIS pegs fair value at $263.13, which sits above the last close of $217.26. This suggests the market is treating the stock with some caution despite solid fundamentals and capacity projects under way.
Continued mix shift toward recurring chemistries and services, which now account for roughly 80% of STERIS revenue versus about 20% a decade ago, can add stability to organic revenue and support operating leverage into earnings.
Execution on the US$600 million Formulated Chemistries Center of Excellence in North Carolina and the US$60 million sterility assurance plant in Ohio, both designed to consolidate production and add automation, can support higher volume in high margin consumables and improve net margins once the facilities are fully utilized.
See why 7 investors see STERIS as 17% undervalued.
Result: Fair Value of $263.13 (UNDERVALUED)
Still, the STERIS narrative hinges on tariff costs remaining manageable and on the North Carolina chemistries build out avoiding prolonged disruption to cash flow and margins.
Find out about the key risks to this STERIS narrative.
Another View On STERIS Valuation
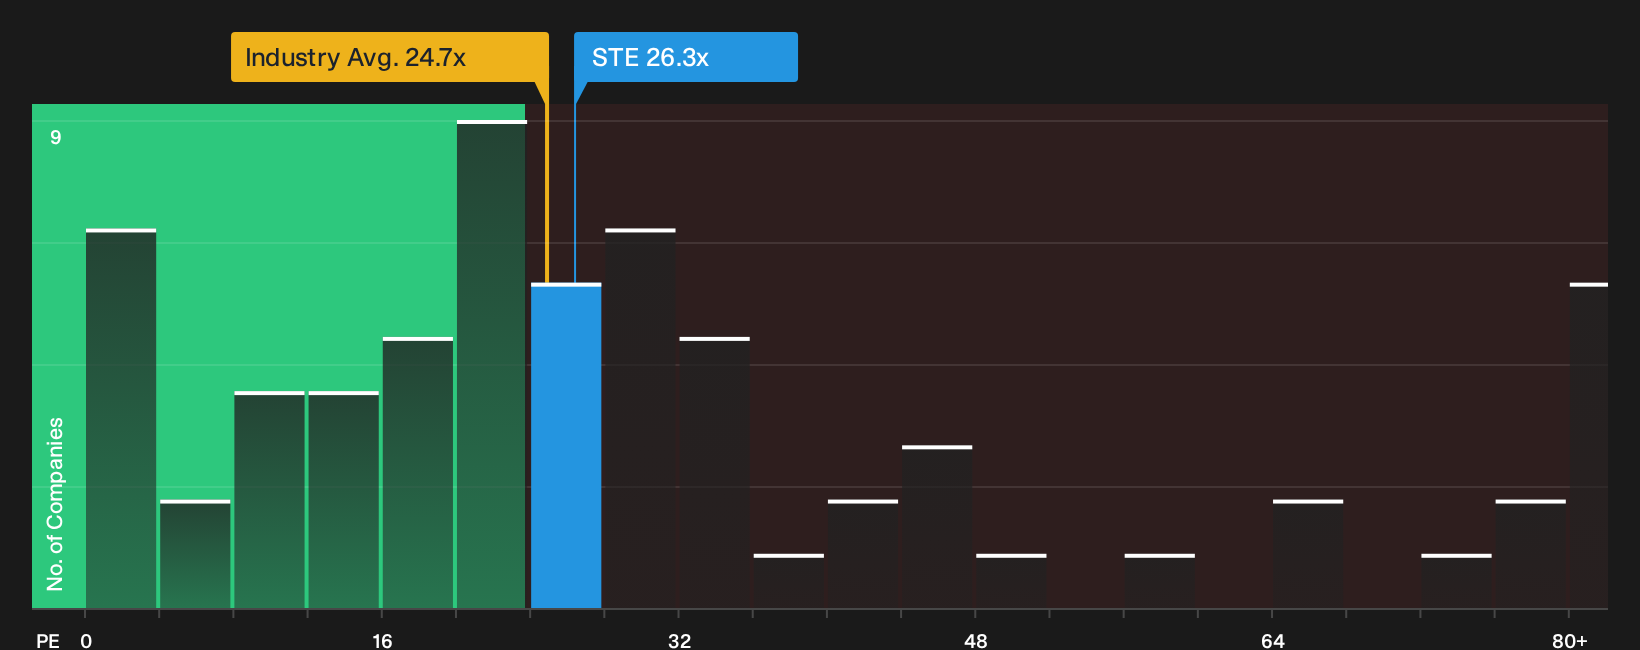
The most popular narrative frames STERIS as undervalued at a fair value of $263.13. A different lens tells a cooler story. On a P/E of 26.3x, the stock trades above the fair ratio of 25.8x and above both peers at 22.6x and the US Medical Equipment sector at 24.5x. That richer multiple points to less valuation cushion if sentiment weakens. How much premium are you comfortable paying for STE's quality and growth profile?
For a closer look at how this earnings multiple stacks up against fundamentals over time, have a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed sentiment around STERIS really holds up against the underlying numbers? Move quickly, stress test the thesis yourself, and then weigh what the market might be missing by checking the 3 key rewards.
Looking for more investment ideas beyond STERIS?
If STERIS has your attention, do not stop at a single stock. Use the tools available, line up alternatives, and keep upgrading your opportunity set.
- Target reliable compounding by reviewing companies with strong balance sheets and healthy fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispricings by scanning the 31 high quality undervalued stocks where quality and pricing strength line up more attractively than the headline suggests.
- Build a watchlist of potential future winners by running through the 20 high quality undiscovered gems before they land on every investor's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com