
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Brandywine Realty Trust Bears Were Right Before The Drop
Brandywine Realty Trust just reported that its Q2 2026 revenue reached US$120.139 million, with the quarterly loss narrowing to US$31.658 million on a net margin of 26.4% in the red. For Brandywine Realty Trust shareholders, the loss over the past year was 24.1%, including dividends. If you had bought in expecting Philadelphia and Austin projects to reshape the story, you may now be assessing how to view a business that is still loss making but reporting a less severe hit to earnings.
If the move has made Brandywine Realty Trust harder to judge, start where the gap is still open and scan 32 high quality undervalued stocks.
The Argument Brandywine Investors Were Really Weighing
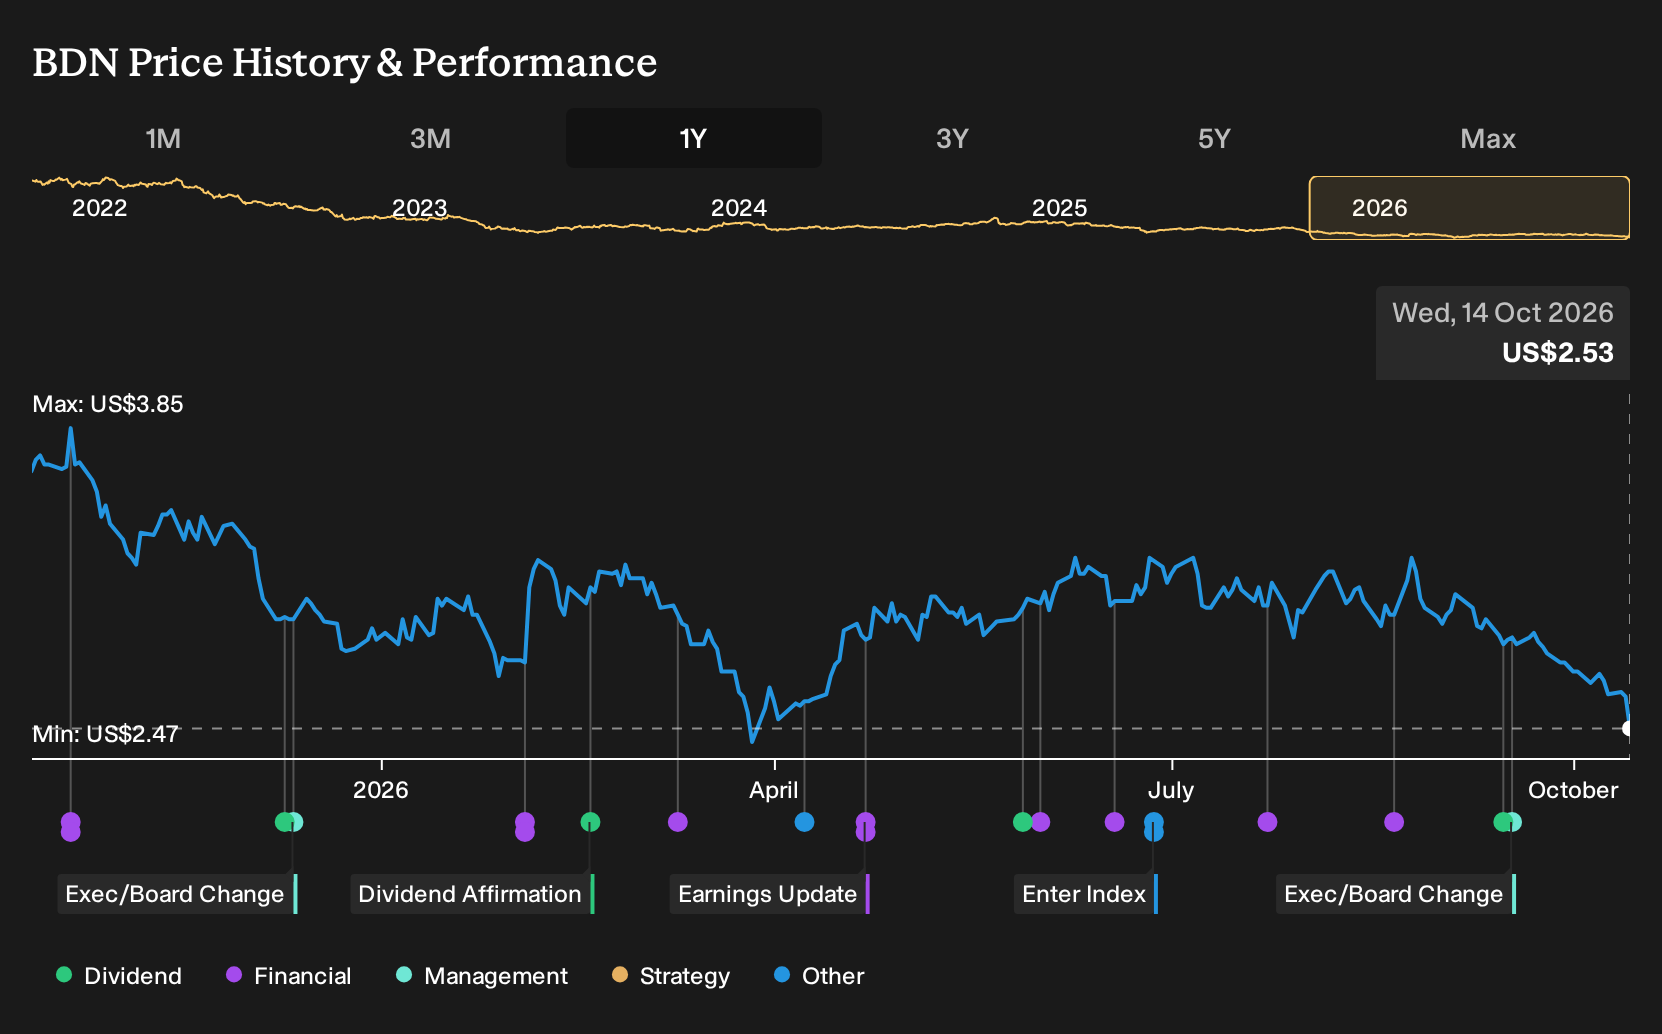
The shares cost US$3.71 at the start of the period, and Brandywine Realty Trust sat between two very different scripts about what Philadelphia and Austin could mean for holders.
On the optimistic side, the bullish narrative saw a Fair Value of US$4.83, a price level those assumptions implied if big urban projects such as Schuylkill Yards and Uptown ATX matured and helped support higher occupancy and new income streams.
The cautious view carried a Fair Value of US$3.5, a level tied to worries that concentrated exposure to office markets in Philadelphia and Austin, along with elevated leverage and refinancing risk, could keep pressure on occupancy, cash generation, and dividend resilience.
What The Results Changed For Brandywine Realty Trust
Brandywine Realty Trust reported Q2 2026 revenue of US$120.139 million and a quarterly loss of US$31.658 million, which was a smaller loss than Q2 2025. That combination supported the optimistic script about improving cash generation but still left profitability unproven. The net margin moved from 84.5% in the red to 26.4% in the red, so the evidence cut both ways.
The key assumption investors can lift to other REITs is whether margin recovery is actually showing up in filings. When evaluating a bullish story about major projects, it can be useful to track the trend in losses and net margin quarter by quarter to see if it lines up with the narrative.
What Brandywine’s Share Price Drop Now Asks You To Believe
Brandywine Realty Trust trades at US$2.53 today, and the selected Narrative’s Fair Value sits above that level based on its own assumptions rather than a settled truth. The stock is down 24.1% over the past year, so the question has shifted from survival to whether the plan can translate into steadier cash flow.
The Narrative highlights leasing progress, planned asset disposals, and debt reduction as the levers that could reshape outcomes. For the fall to look like an opportunity rather than a warning, a buyer today would need confidence that leasing in Austin and life science projects plus planned property sales and refinancing actually materialize as outlined.
"The main factor that has to go right is the execution of the balance sheet plan, which pairs over US$300m of asset sales at around 8% cap rates with debt reduction and high coupon bond repurchases, while Austin occupancy and life science leasing gradually improve."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond Brandywine’s Buildings
Brandywine Realty Trust is all about where people work and live. You could also look at what keeps those places powered.
Growing demand for electricity is tied to data centers, electrification, and grid upgrades. One industrial player focuses on the hardware and software that move that power reliably.
This business designs equipment that helps generate, convert, and route electricity across long distances. It also supports installed machines for decades through maintenance, upgrades, and digital tools.
That mix can turn one-off projects into long relationships with utilities and industrial customers. If power demand keeps shifting, the role of that kind of provider may shift with it.
Could this be another way into the opportunity? → Explore the power-grid opportunity and its 26% discount to one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com