
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Stryker (SYK) Wins FDA Clearance, Is The 9% Undervaluation Enough?
Stryker (SYK) has just received 510(k) clearance from the U.S. Food and Drug Administration for Sonopet 3, its latest ultrasonic bone and soft tissue removal platform, putting product development in focus for investors.
Stryker shares trade at US$281.62, and the stock has slipped over the year with the year to date share price return down 19.12% and the 1 year total shareholder return down 22.99%. The 3 and 5 year total shareholder returns of 7.37% and 8.44% signal a more modest long run profile and suggest recent momentum has faded despite product launches, CEO succession plans and the CMR Surgical alliance reshaping the story.
Scan how Stryker stacks up against other medical technology players by reviewing our curated list of list of solid balance sheet and fundamentals (25 results)
Stryker’s recent share price decline, despite new products and a CEO transition, is dividing opinion. Are you seeing signs of a business issue emerging, or a sentiment reset that makes the current valuation more interesting to evaluate?
Most Popular Narrative: 9.5% Undervalued
Stryker is trading at $281.62 against a widely followed fair value estimate of about $311, which points to a modest valuation gap that investors are now weighing against weaker recent share price performance.
Stryker is my defensive-growth anchor, a high-quality medtech leader in orthopaedics, surgical equipment and MedSurg. It is riding the durable tailwind of an ageing population. Demographics, not hype, drive this thesis.
See why 5 investors see Stryker as 10% undervalued.
Result: Fair Value of $311 (UNDERVALUED)
Still, two pressure points could unsettle that Stryker thesis: a sharper pullback in hospital capital spending and any stumble integrating acquired product lines.
Find out about the key risks to this Stryker narrative.
Another View: Multiples Put Stryker’s Price In Context
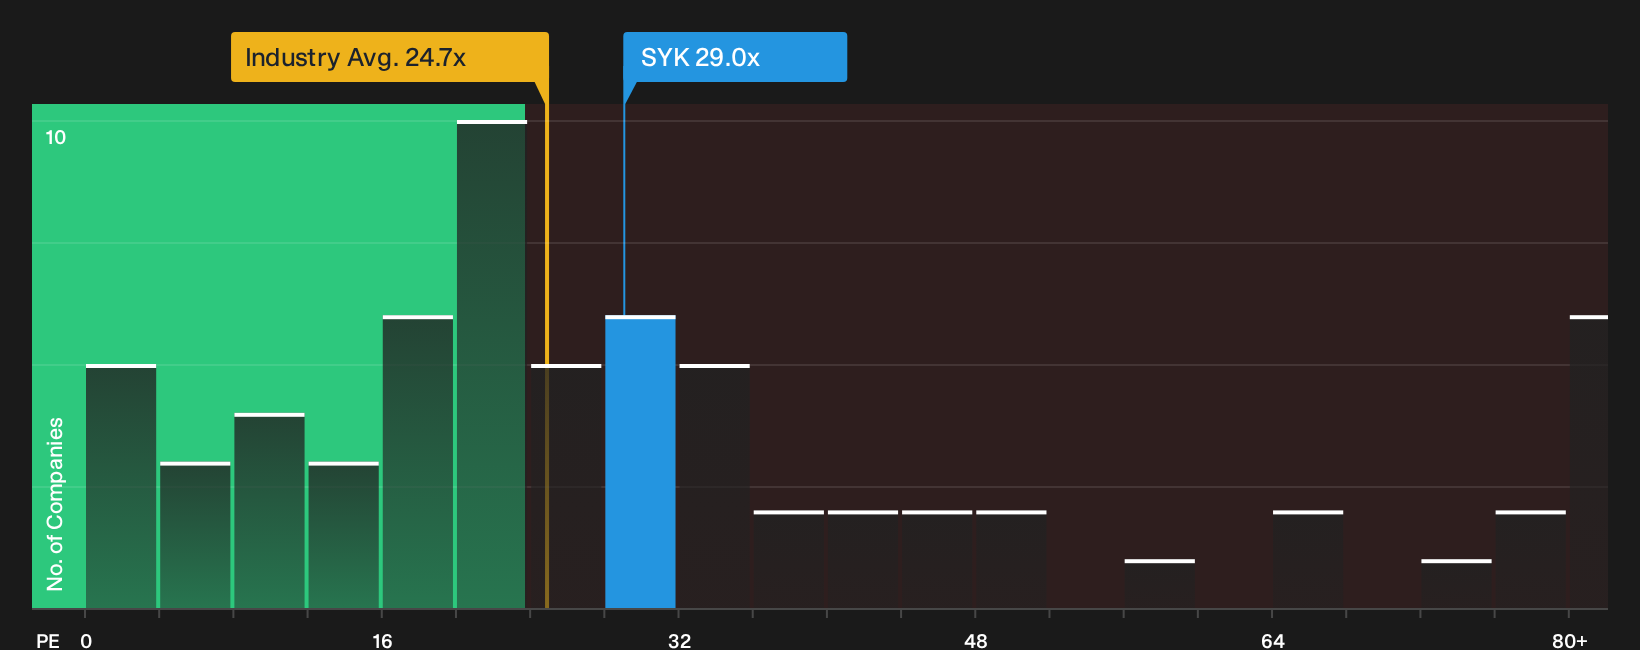
A second lens says something different about Stryker. On a P/E of 29x, the stock trades above the US Medical Equipment industry at 24.7x. It sits roughly in line with peers at 30.1x, yet below an estimated fair ratio of 33.2x, which points to some valuation cushion but also less room for error if sentiment weakens.
To pressure test that picture against the earnings multiple and see what the numbers imply for risk, valuation and expectations, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on the story so far, or starting to see a clearer picture around Stryker’s risks and rewards? Act quickly, review the underlying data, and weigh both sides for yourself with the 4 key rewards and 2 important warning signs
Looking for more Stryker sized investment ideas?
If you want to stress test your thinking beyond Stryker, use the Simply Wall Street Screener to surface fresh opportunities that fit your own risk and return preferences.
- Target potential value opportunities by scanning companies that combine quality fundamentals with appealing pricing through the 32 high quality undervalued stocks.
- Protect your downside by focusing on resilient businesses and filter for sturdier balance sheets and steadier profiles using the 32 resilient stocks with low risk scores.
- Get ahead of the crowd by surfacing underfollowed stocks with strong fundamentals through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com