
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IREN Shares Rose on Reports of a Multiyear Deal With Anthropic. How Investors Should View the News.
Winning artificial intelligence (AI) customers is one thing. Turning their demand into shareholder returns is another. Iren Limited (IREN), which operates data centers for Bitcoin (BTCUSD) mining, is expanding into AI cloud services by supplying GPU computing capacity for demanding workloads.
That expansion gained momentum as IREN secured a $2.8 billion financing facility covering roughly 90% of associated GPU spending, helping fund its AI expansion. These commitments show the appetite for computing capacity and the size of the opportunity investors are trying to value.
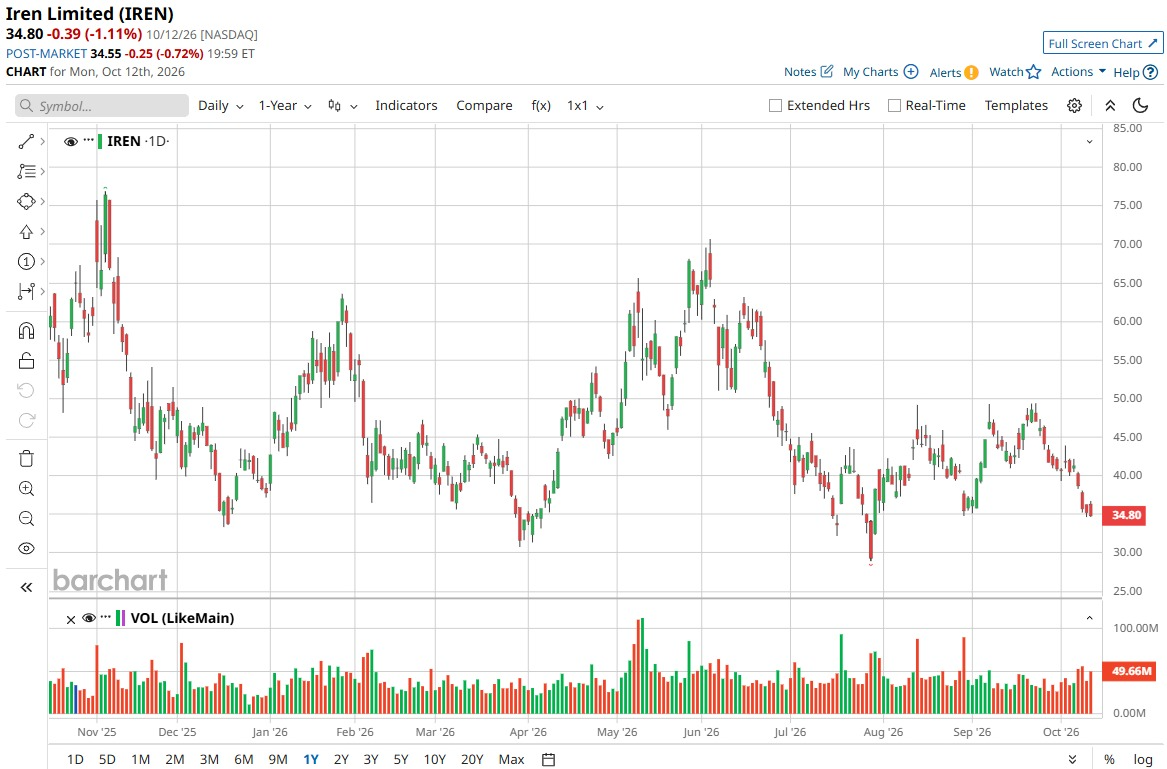
Now, reports of a multiyear cloud agreement with Anthropic have put IREN stock back in focus. But the excitement of a 5% premarket rise on Oct. 12 came after a difficult stretch for shareholders. At around $29 as of Oct. 15, IREN stock is down 22% year-to-date (YTD) and 57% over the past 52 weeks.
Could the reported Anthropic agreement give investors a stronger reason to buy IREN? Let’s take a closer look.
What the Reported Anthropic Deal Could Add
The potential Anthropic agreement puts IREN’s customer relationships in focus. On Oct. 12, reporting linked IREN to an unannounced multiyear cloud agreement with Anthropic. Neither company had commented, and the coverage did not establish when the agreement was signed. Its value, computing capacity, deployment location, and revenue start date also remain unresolved questions.
The central question is whether Anthropic represents additional business or an existing customer. During the August earnings call, co-CEO Daniel Roberts disclosed contracts with Cohere, Perplexity, and an unnamed leading frontier AI laboratory. IREN has not confirmed whether Anthropic is that AI lab. If it is, the report would reveal customer identity without necessarily increasing existing revenue commitments.
While Anthropic’s reported terms remain unclear, IREN’s other customer deployments offer a clearer measure of its execution. Microsoft (MSFT) accepted Horizon 1 after a five-day testing window, enabling monthly invoicing under its five-year $9.7 billion agreement. Nvidia (NVDA) also awarded the GB300 deployment with Exemplar Cloud status following performance and reliability testing.
IREN has nevertheless secured substantial funding for expansion. On Aug. 28, Blue Owl (OWL) announced $2.4 billion in equipment financing for the company, comprised of a $1.2 billion senior secured term loan and $1.2 billion in senior secured notes. These proceeds will fund Nvidia computing infrastructure, including Blackwell Ultra GPUs, at IREN’s Mackenzie campus in British Columbia. The financing announcement does not establish that Mackenzie would serve Anthropic.
Investors should view the news as potential validation of IREN’s customer base, rather than an automatic boost to its financial outlook. If Anthropic is the previously unnamed customer, the report may identify business already included in existing commitments. A separate agreement could offer additional growth, but its value would still depend on pricing, deployment costs, and revenue timing.
IREN’s Overall Financial Performance
IREN's financial results show a business changing faster than its total revenue suggests. Fiscal fourth-quarter figures put revenue at $137.2 million, down from $187 million a year earlier. That 27% decline, alongside a wider net loss, shows AI expansion has not yet translated into stronger overall financial performance.
However, AI cloud revenue more than doubled sequentially to $70.5 million, accounting for approximately 51% of quarterly sales. Across the full fiscal year, the segment generated $128.8 million, roughly eight times its previous annual revenue.
IREN’s approximately $12 billion market capitalization places considerable weight on continued expansion. Management expects contracted annualized recurring revenue (ARR) to exceed $4 billion by December, with $1 billion already operating. This measures revenue at an annual operating pace rather than sales already booked or profit available to shareholders.
Supporting those deployments requires power and infrastructure. On Sept. 8, IREN announced conditional Base Load inclusion for its 2 gigawatt Sweetwater Hub in ERCOT’s Batch Zero process. Both Sweetwater 1 and Sweetwater 2 were included, marking progress toward supporting future computing demand. Conditional inclusion does not mean the full capacity is operational or already generating revenue.
Wall Street Looks Beyond Near-Term Losses
IREN is set to report results on Nov. 5 for the quarter ended September 2026, with analysts projecting a loss of $0.46 per share compared to a $0.34 loss in the same period last year. That represents a 35% deterioration, with the projected loss widening by $0.12 per share.
Even so, JPMorgan’s changing stance shows how quickly the investment case has evolved. In August, analyst Richard Choe reiterated a “Sell” rating before earnings, citing uncontracted GPU capacity and elevated debt as key risks while maintaining a $46 price target. However, Choe turned considerably more optimistic on Sept. 14, double-upgrading IREN stock to “Overweight” from “Underweight” and raising his target to $65. Stronger customer signings, firmer AI cloud pricing, and IREN’s Nvidia relationship helped support the change. His assessment also identified potential to contract about 0.5 GW of additional capacity in 2027.
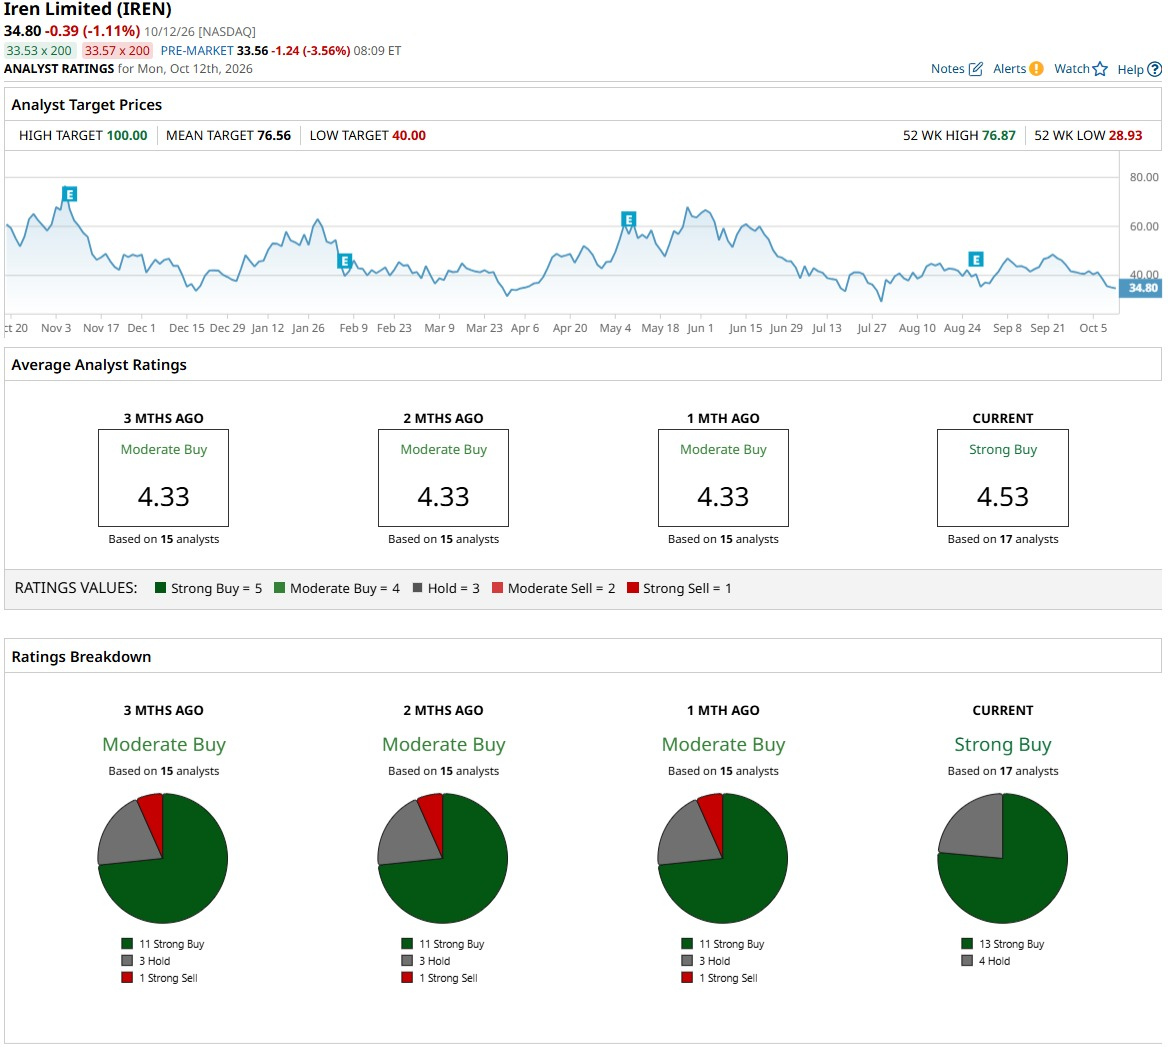
Based on 17 analysts, IREN stock carries a consensus “Strong Buy” rating, although that does not mean every analyst recommends buying shares. The average price target of $76.56 implies potential upside of 159% from current levels. That substantial gap suggests expectations for improvement, but a price target remains a forecast rather than a promised return.
Conclusion
The Anthropic report deserves cautious optimism, not an automatic buy. It could strengthen confidence in IREN’s customer base without adding business beyond existing commitments. The likelier near-term effect is greater attention to its AI expansion, rather than an immediate improvement in earnings. A stronger investment case would require confirmed contract terms and evidence that deployments generate attractive returns. Until then, the sensible move is to watch execution closely and let revenue delivery, not another customer name, guide the decision.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.