
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Steve Madden (SHOO) Azzy Milan Shoe Line
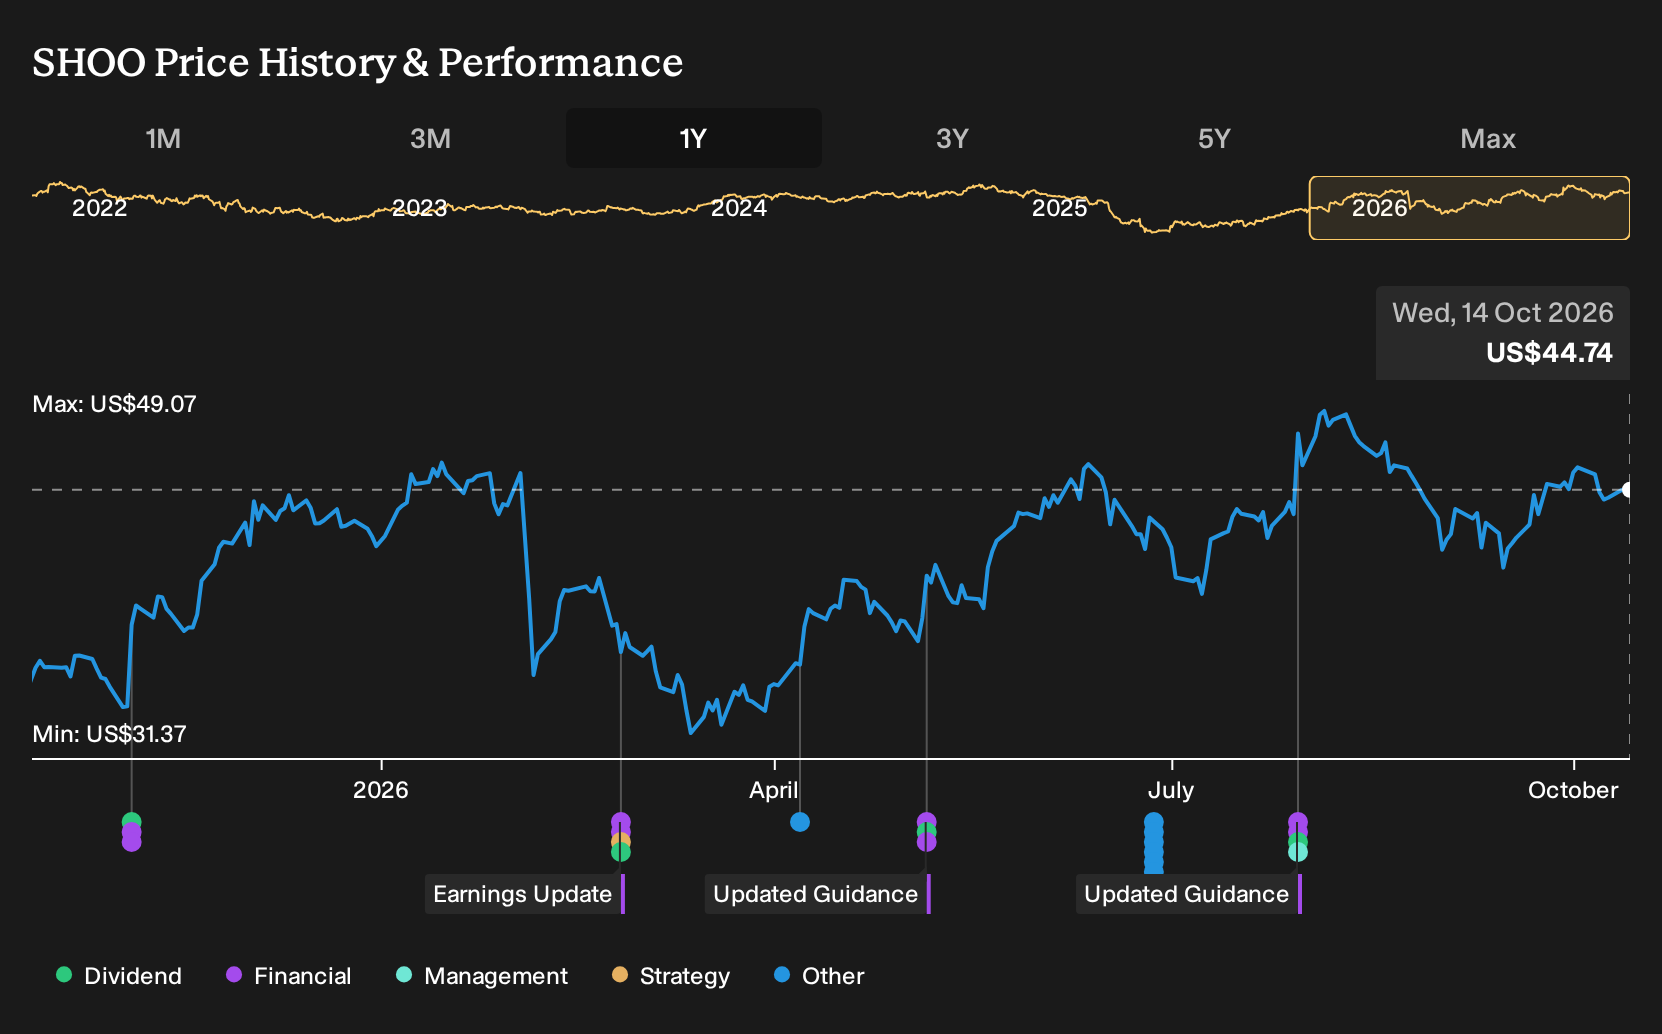
- Steve Madden recently launched a dedicated shoe line with influencer Azzy Milan, adding a new collaboration to its branded footwear portfolio.
- The Azzy Milan tie up gives Steve Madden another route to test influencer led product development, which could inform future design and marketing decisions.
- We will look at how Steve Madden's investment narrative is influenced by the Azzy Milan collaboration and its influencer led reach.
Scan how Steven Madden fits into a wider set of footwear and consumer brands by comparing it against a hand picked group of 20 high quality undiscovered gems that are poised for the next wave of attention.
Steven Madden Investment Narrative Recap
To own Steven Madden, you need to believe that branded footwear, accessories, and direct to consumer channels keep doing the heavy lifting while tariffs, freight, and Kurt Geiger integration costs stay manageable. The Azzy Milan line fits into that story as another test of influencer led demand rather than a major earnings swing factor on its own in the near term.
In the short term, the key upside driver is still mix shift into higher margin direct channels and tight control of SG&A as marketing spend rises. The main risk remains tariff and sourcing pressure, combined with weakness in value oriented wholesale and private label that could cap overall margin progress if it lingers.
Among recent developments, the Azzy Milan collaboration is most relevant here because it connects directly to Steven Madden's focus on digital growth and influencer marketing. Management is already spending around 5.3% to 5.4% of revenue on brand building. A dedicated influencer line simply gives that budget another test case tied to product, not just awareness.
This matters for catalysts because earnings forecasts emphasize strong direct to consumer performance and sustained pricing power. If influencer led capsules such as Azzy Milan support full price selling and help reduce promotional activity online and in stores, they feed into that mix shift story. If they underperform, marketing efficiency and the return on that higher spend become sharper questions for investors.
What The Azzy Milan Line Means For Steven Madden's Forecasts
Steven Madden's current analyst narrative focuses on the broader growth and margin path, and the Azzy Milan collaboration fits within that larger earnings framework. Analysts are modeling revenue to rise by 8.2% each year over the next three years, with profit margins moving from 5.2% today to 8.0% by 2029. On the earnings side, projections point to profit of $276.8 million by 2029 compared with $143.3 million today, which implies an earnings increase of about $133.5 million over that period. Those same estimates pair with a 2029 revenue target of $3.5 billion and a valuation anchored on a P/E multiple of 18.2x, down from 23.5x today. Investors can compare these figures with their own expectations for how influencer-led capsules such as Azzy Milan might contribute to that long-range mix of growth, profitability, and marketing efficiency.
Steven Madden's narrative projects $3.5 billion in revenue and $276.8 million in earnings by 2029. This implies 8.2% yearly revenue growth and an earnings increase of about $133.5 million from $143.3 million today.
Discover how Steven Madden's fair value indicates a 17% potential upside to its current price that may be short-lived.
Exploring Other Perspectives
One alternate view zooms in on free cash flow rather than headline growth. The most cautious analysts were still penciling in about 7.5% yearly revenue growth to roughly US$3.4b and earnings of US$285.9 million by 2029, yet they paired that with a much lower 13.2x P/E. You can decide whether the Azzy Milan launch eventually nudges expectations closer to the consensus story or toward that more skeptical camp.
Explore another Steven Madden fair value estimate, including one that suggests it could be worth just $52.40.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Steven Madden research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Steven Madden. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Steven Madden's overall financial health at a glance.
Looking for more Steven Madden style ideas?
If the Steven Madden story has you thinking about what else might fit your portfolio, it can help to scan a wider set of companies with similar qualities. Use the Simply Wall St screener to line up candidates by fundamentals, risk, and balance sheet strength before you commit fresh capital.
- For investors who want quality on sale, start with a focused group of 32 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- If steady cash flows and resilience matter most to you, filter for a list of solid balance sheet and fundamentals (25 results) and see which businesses pair financial strength with consistent operations.
- When capital preservation is front of mind, look across a 32 resilient stocks with low risk scores that screens for companies with lower risk scores and fewer red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com