
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
WiseTech Global (ASX:WTC) Rebounds After ASIC Clears Key Overhang With Valuation Back In Focus
WiseTech Global (ASX:WTC) jumped into focus after ASIC closed its investigations into founder Richard White and the group’s governance without enforcement action, issuing no action letters that ease a key regulatory overhang.
The ASIC outcome lands after a sharp reset in WiseTech Global’s share price this year, with the stock now at A$34.50 and a year to date share price return down 49.67%. That sits against a 1 year total shareholder return decline of 58.55% and weaker 3 and 5 year total shareholder returns, even though short term momentum has picked up with a 7 day share price return of 6.94% and a 30 day share price return of 4.39% as investors reassess regulatory risk and growth expectations.
Compare WiseTech Global's reset with a curated group of quality software and tech platforms in our 15 high quality undiscovered gems to see how other under-the-radar opportunities stack up in terms of fundamentals and recent momentum.
WiseTech Global has shed almost half its value this year, yet bounced in recent weeks as the ASIC cloud cleared. Does that reset leave enough upside in the current A$34.50 price to justify the risk?
Most Popular Narrative: 43% Undervalued
On the most followed view, WiseTech Global screens as undervalued, with a fair value of A$60.19 against the current A$34.50 share price, putting the recent reset against a much higher long term earnings story.
The rollout of the new unified, transaction-based CargoWise commercial model (the "Value Pack"), which removes seat-based pricing and bundles advanced AI-driven workflow and management engines, is expected to accelerate market penetration, reduce adoption friction, and open the SME market, resulting in significant recurring revenue uplift and higher customer retention as user engagement scales with transaction volumes.
See why 141 investors see WiseTech Global as 43% undervalued.
Result: Fair Value of A$60.19 (UNDERVALUED)
Still, the WiseTech Global story could shift quickly if E2open integration drags on costs or if the new transaction pricing model undercuts revenue from larger customers.
Find out about the key risks to this WiseTech Global narrative.
Another View: What WiseTech Global’s P/E Is Saying
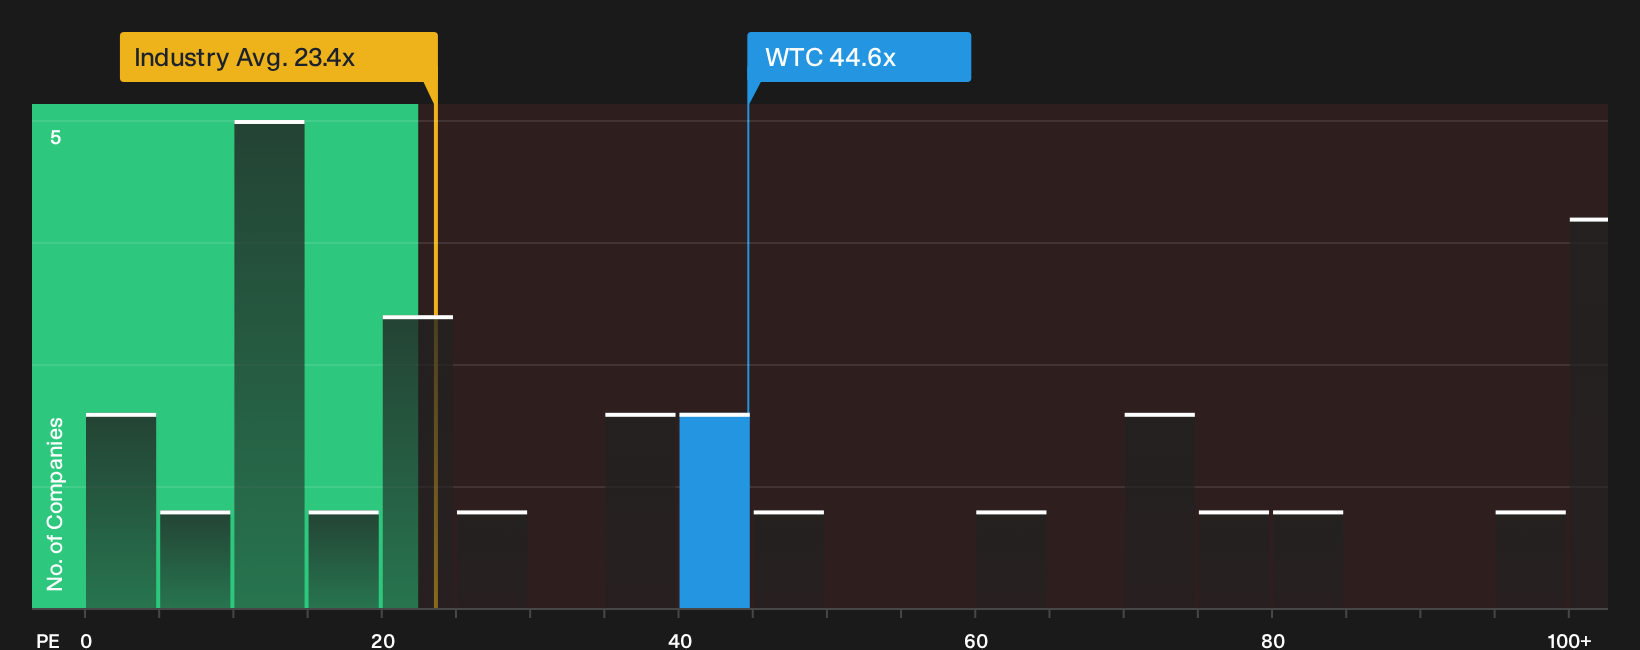
While the SWS DCF model flags WiseTech Global as undervalued, the P/E story is less generous. The stock trades on 44.6x earnings, slightly above peer averages at 44.4x and well above the Australian software group on 23.4x. If the fair ratio sits at 46.6x, investors may wish to consider whether expectations are already packed into the price.
For a closer look at how that earnings multiple compares with peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around WiseTech Global leave you unsure, treat that as your cue to move fast and interrogate the numbers yourself. To weigh up both the upside potential and the issues flagged by other investors, start with the 2 key rewards and 3 important warning signs.
Looking for more WiseTech Global sized ideas?
If WiseTech Global has sharpened your focus, do not stop here. Broaden your watchlist now and give yourself more ways to put your capital to work.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (12 results) that combine financial strength with dependable fundamentals.
- Hunt for mispriced opportunities through the 4 high quality undervalued stocks where quality metrics and valuation checks work together to surface potential bargains.
- Prioritise stability and income potential with the 3 dividend fortresses and focus on businesses offering higher yields supported by their fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com