
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Urban Outfitters (URBN) Is Getting Fresh Attention
Urban Outfitters (URBN) is back in focus after reporting its eighth straight quarter of record sales and profits, a run that has drawn fresh analyst attention and coincided with stronger recent share performance.
That backdrop has been feeding into the chart. Urban Outfitters’ share price is up 9.96% over the past month and 12.28% over the last 90 days, while total shareholder return sits at 24.71% over one year and well over 7x over five years, which points to momentum that has been building rather than fading.
Scan other retailers showing similar momentum to Urban Outfitters by reviewing the hand picked 32 high quality undervalued stocks that combine quality fundamentals with recent strength.
Recent gains leave Urban Outfitters looking healthier on the surface, yet the jump follows both record trading updates and a fresh analyst spotlight. How much of this move reflects fundamentals rather than a mood shift around the stock?
Most Popular Narrative: 5.3% Undervalued
On the most followed valuation view, Urban Outfitters’ fair value sits at $89.43, a touch above the recent $84.68 close. This frames the latest share gains as still within narrative expectations rather than wildly ahead of them.
The main thing that has to go right is continued profitable expansion of Nuuly and FP Movement while maintaining healthy margins and product relevance at Anthropologie and the Urban Outfitters banner despite cost headwinds.
The broader shift of Urban Outfitters, Inc. into a five brand portfolio with different banners, channels and customer demographics can create more stable company level revenue and margin performance as strengths in Nuuly, FP Group or Urban Outfitters offset periods of softer trends in Anthropologie or specific categories.
Find out how 15 investors see Urban Outfitters as 5% undervalued
Result: Fair Value of $89.43 (UNDERVALUED)
Still, the story around Urban Outfitters can change quickly if the planned US$475 million capex fails to pull its weight or if Anthropologie’s margin pressure persists.
Find out about the key risks to this Urban Outfitters narrative.
Another View: Urban Outfitters On Future Cash Flows
The consensus narrative frames Urban Outfitters as 5.3% undervalued at a fair value of $89.43, yet the SWS DCF model tells a different story. On that math, URBN at $84.68 trades above an estimated future cash flow value of $78.51, which points to a stock that screens as overvalued instead. Which lens do you trust when the story and the cash flow math do not quite line up?
For a closer look at the moving pieces behind this cash flow view, including the assumptions that pull the DCF result below the current share price, Look into how the SWS DCF model arrives at its fair value.
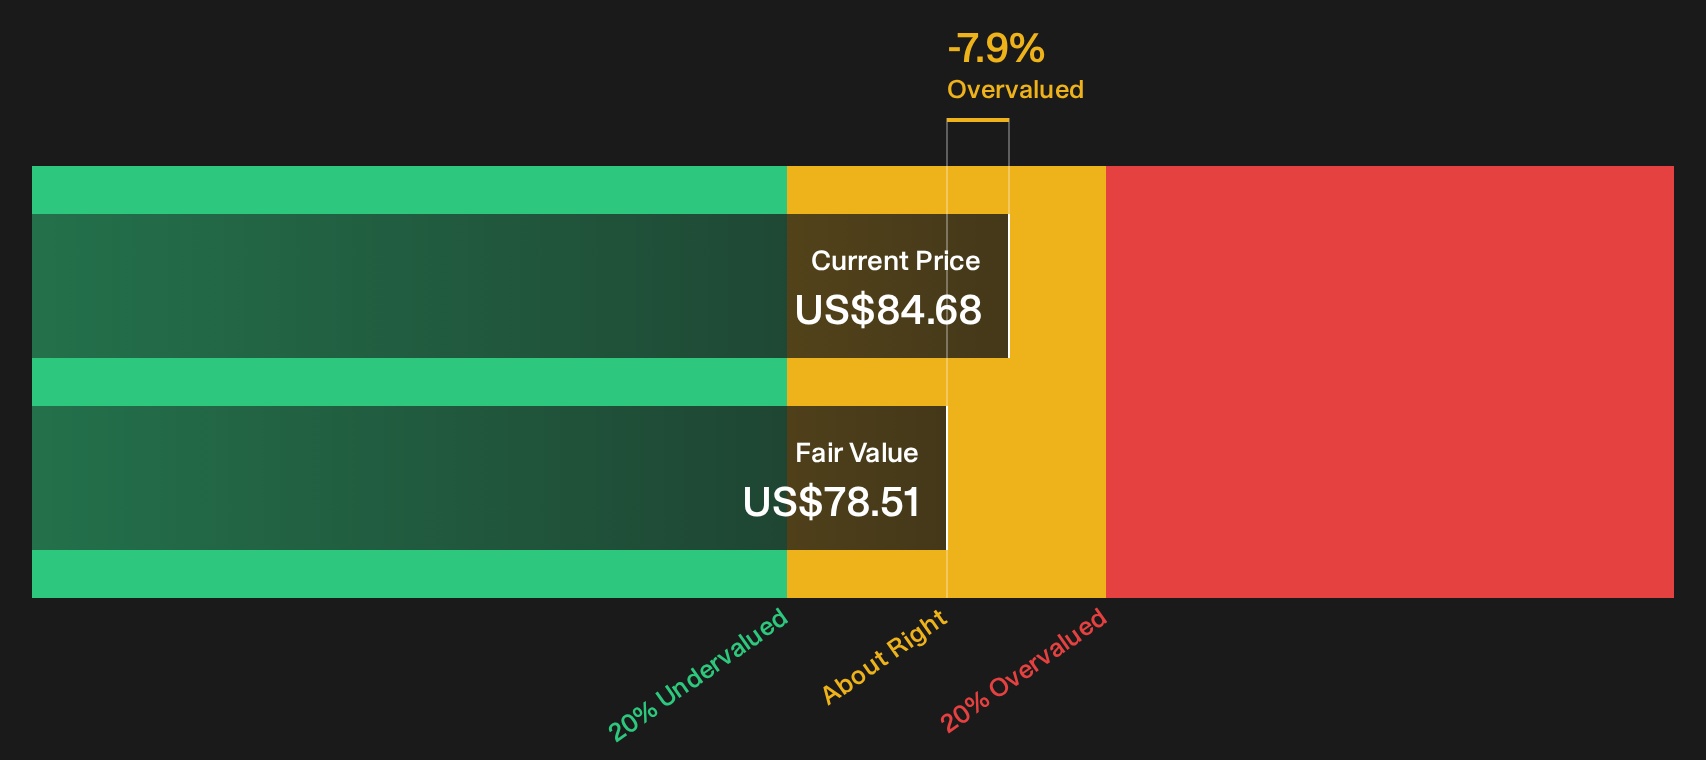
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Urban Outfitters for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Urban Outfitters so far. If you want to move fast and build your own view from the ground up, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Urban Outfitters?
Do not stop at Urban Outfitters. Use the Simply Wall Street Screener to explore additional stock ideas that align with your risk tolerance, income goals, and time horizon.
- Look for potential mispricing by scanning the 32 high quality undervalued stocks that combines robust fundamentals with prices that may not fully reflect underlying strength.
- Explore potential income streams by reviewing a curated 7 dividend fortresses built around higher yields and payout resilience.
- Adjust risk levels without avoiding opportunities by filtering for a 32 resilient stocks with low risk scores that emphasizes resilience and financial durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com