
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Are Half Year Earnings Altering The Investment Case For Izumi (TSE:8273)?
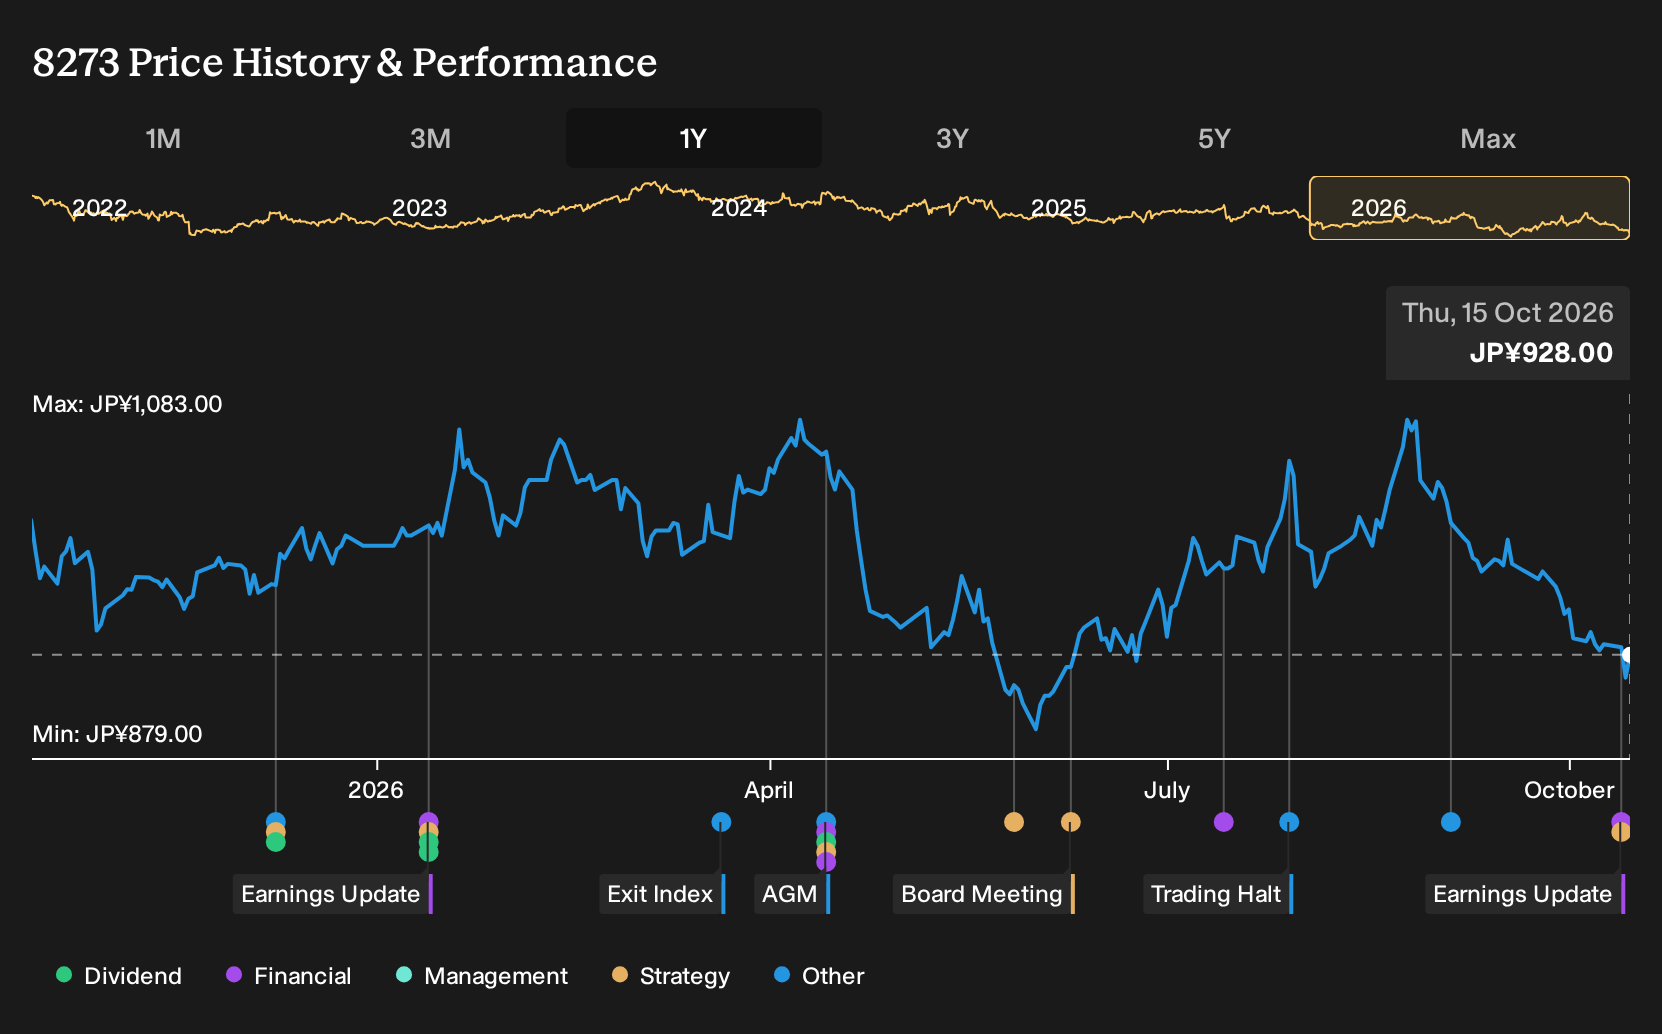
- Izumi Co., Ltd. reported half year results for the period ended August 31, 2026, with sales of ¥253,907 million, net income of ¥8,426 million, and basic earnings per share from continuing operations of ¥40.1.
- The retailer scheduled a board meeting on October 13, 2026, to consider an absorption type merger of three wholly owned subsidiaries, a move that could simplify the group structure and sharpen Izumi's operational focus.
- The investment narrative for Izumi will now be examined, with the higher half year net income acting as the key reference point.
What Is Izumi's Investment Narrative?
To own Izumi, you need to buy into a fairly simple idea. This is a mature Japanese retailer that lives or dies on solid store execution, disciplined costs, and steady customer traffic rather than big swings in demand. The half year figures show modestly higher sales and net income, with basic EPS from continuing operations at ¥40.1, which supports that story of earnings resilience more than rapid expansion.
The proposed merger of three wholly owned units, Youme Mart Kumamoto, Youme Mart Kitakyushu, and SUNLIFE, points to a push for cleaner operations and potentially lower overhead rather than a change in growth profile. In the short term, the key swing factors remain day to day demand, pricing power in a competitive retail market, and how efficiently Izumi reinvests in stores and systems, especially given its capital needs and historically low return on equity.
That said, sitting behind this apparently tidy consolidation story is one issue that can easily be missed until you look closely at...
There's only one way to know the right time to buy, sell or hold Izumi. Head to Simply Wall St's company report for the latest analysis of Izumi's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Izumi research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Izumi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Izumi's overall financial health at a glance.
Looking For More Investment Ideas Beyond Izumi?
If Izumi's story has sharpened your thinking about what you want in a business, it can help to scan a broader field of opportunities using the Simply Wall St Screener. Focus on the mix of quality, balance sheet strength, and return profile that fits your own risk tolerance and time horizon.
- If your priority is financial resilience and cleaner balance sheets, start with companies that pass a tighter quality filter by reviewing the list of solid balance sheet and fundamentals (21 results).
- For investors who prefer to hunt for strong businesses that the market may have priced cautiously, take a look at the 72 high quality undiscovered gems and see which tickers match your criteria.
- If income is front of mind and you want stocks that offer higher yields while aiming for durability, focus on the 32 dividend fortresses and see which candidates fit your payout expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com