
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Halliburton Holders Bought Into
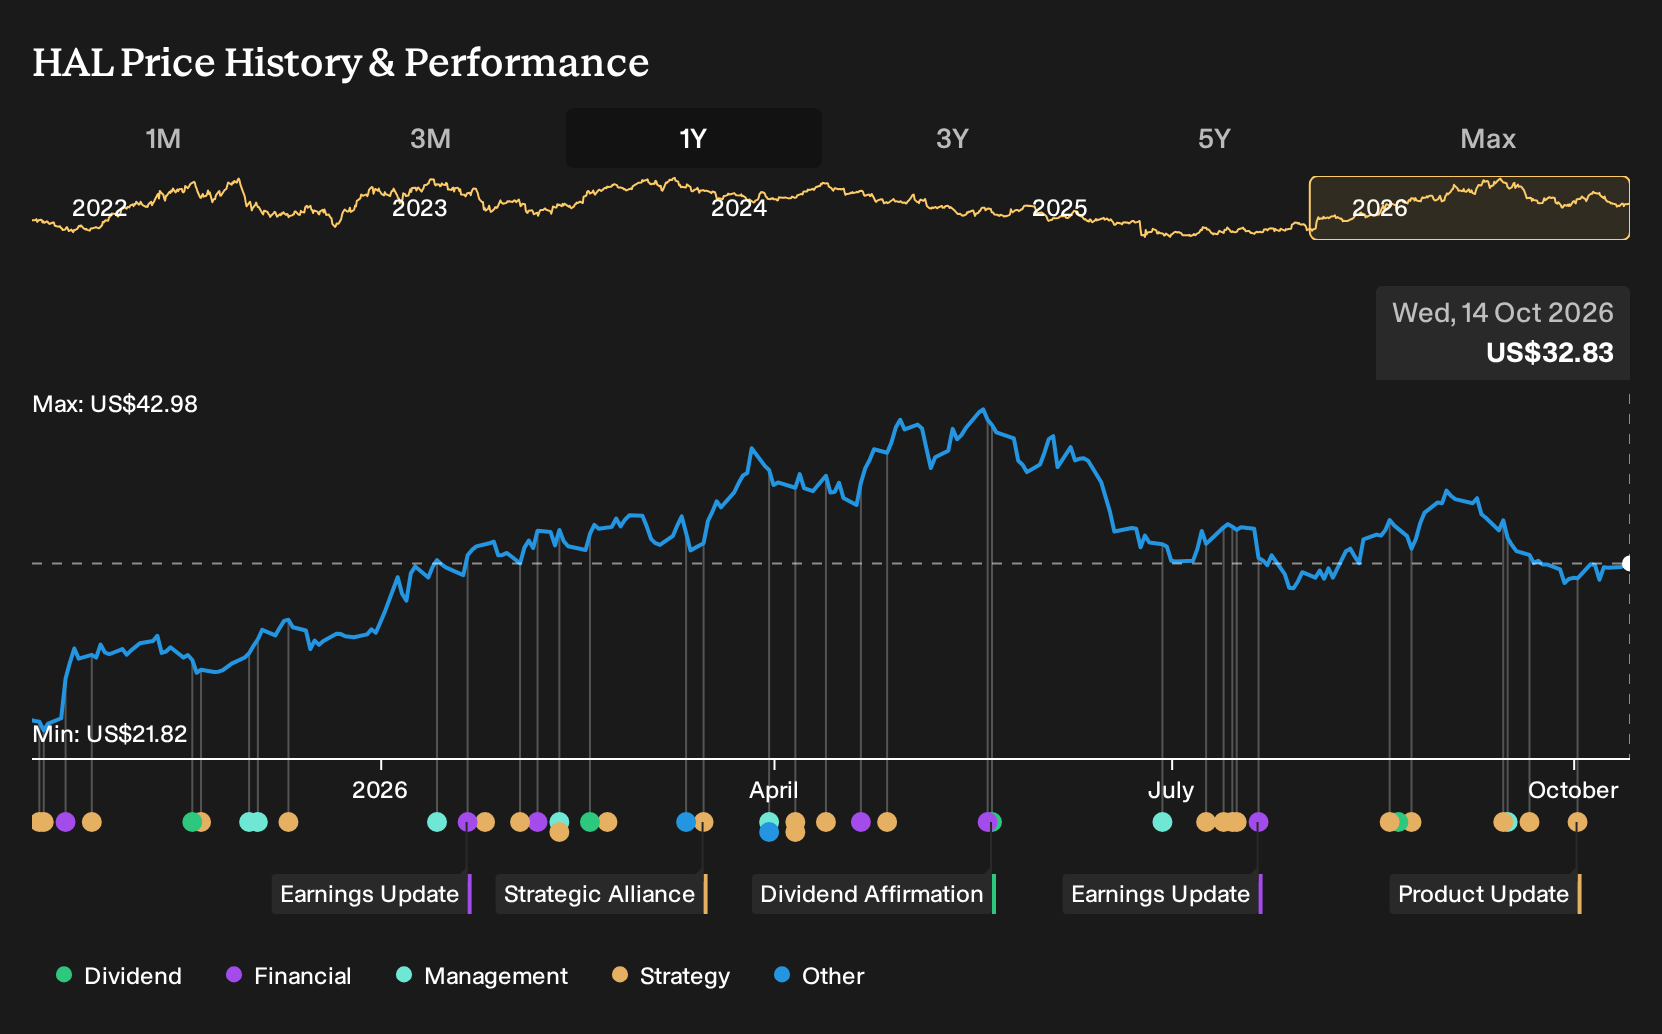
If you had bought Halliburton on 14 October 2025, the decision was not a layup. Bulls were talking up global energy demand, natural gas as a bridge fuel, and the push into Latin America and the Middle East, while bears were focused on decarbonization policy, ESG pressure, and shrinking activity in North American shale. For Halliburton shareholders, the return over the past year was 49.6%, including dividends. If that choice sat in your portfolio, what exactly were you weighing that day?
This theme extends beyond Halliburton. See which of 43 power grid technology and infrastructure stocks may still merit a closer look.
The Two Halliburton Stories Investors Had To Choose Between
The shares cost US$22.44 at the start of the period, and Halliburton sat between two sharply different stories about what came next.
On the optimistic side, the bullish view argued that rising global energy needs and natural gas as a transition fuel would support Halliburton's services. That camp saw a Fair Value of US$26.69, a price implied by assumptions such as revenue slipping only 0.2% a year while profit margins edged from 8.4% to 9.0% by 2028.
The more cautious narrative focused on fossil dependency as a long term problem. Bears worried that faster decarbonization and tighter regulation would steadily squeeze activity and cash generation. Their Fair Value was US$20, grounded in expectations that revenue would fall 3.1% annually and margins would drift from 8.4% to 8.0% over the same period.
What The Halliburton Evidence Actually Tested
Halliburton securing multi year contracts with YPF in Vaca Muerta and Aramco in Saudi Arabia supported the optimistic story about international expansion and technology led work. Quarterly results pointed the same way. Revenue moved from US$5,510m in Q2 2025 to US$5,714m in Q2 2026, while net income and net margin both rose. The evidence supported the optimistic case.
The decision on 14 October 2025 really turned on one assumption. You were either pricing in sustained international contract wins and higher margins, or you were not. When you look at another oilfield services group, check whether later contracts and reported net margin match that original expectation.
What Halliburton's Recent Run Now Asks You To Believe
Halliburton now trades at US$32.83, with this Narrative placing its Fair Value above that level based on a more optimistic reading of the current setup. The argument leans on international contracts, higher margin digital work and North America as a funding source.
The practical question is whether Halliburton can keep turning that mix into sustained free cash flow that comfortably funds ongoing buybacks.
"Bullish analysts expect Halliburton to turn its expanding international contract base, tighter North American frac market and higher margin digital offerings into stronger earnings power that is not yet fully reflected in the stock. The main thing that has to go right is that Halliburton converts its ahead of schedule international growth engines, higher margin software and automation work, and capital disciplined North American cash generation into sustained free cash flow that supports ongoing buybacks."
One Narrative disagrees with today's price. → See where this Narrative says Halliburton should trade
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 41% below our estimate - uses low cost commercial deposits to expand higher yield lending activities.
- Company 2 - 30% below our estimate - targets data centre GPU rack demand linked to its AI software ecosystem.
- Company 3 - 49% below our estimate - adds new locations and app based ordering while addressing softer comparable sales.
Three companies from the same screener. Open the full list of 32 companies trading below our estimate →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com