
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AXT (AXTI) Could Be 33% Undervalued As Inventory Buildup Puts Cash Use In Focus
Inventory buildup puts AXT (AXTI) cash use in focus
AXT (AXTI) is drawing attention after a buildup in inventory tied to expanding manufacturing and strong demand for indium phosphide substrates began to absorb more cash despite improving profitability.
Despite the recent inventory story, AXT’s share price has been volatile, with a 1-day decline of 4.7% and a 7-day drop of 22.8%, following a strong 90-day share price return of 35.2% and a year-to-date gain of 267.5%. The 1-year total shareholder return is extremely high, suggesting momentum has been strong over a longer stretch even as shorter term sentiment has cooled.
Scan beyond AXT and see how other compound semiconductor players with strong demand stories line up in our hand picked 20 high quality undiscovered gems.
AXT now appears to be a stronger operation tied to high demand for its substrates; however, the share price has surged far faster than recent weeks suggest. Is the business quality already fully baked into today’s valuation?
Most Popular Narrative: 33% Undervalued
AXT’s most followed narrative sets a fair value of $91.60 against the last close at $61.59, so the implied gap is wide and firmly rooted in long term assumptions about its role in compound semiconductors.
Accelerating global demand for high-speed data center connectivity and AI infrastructure is driving increased adoption of indium phosphide substrates, where AXT is a top supplier with 40% share. As export permit headwinds ease, this pent-up demand is expected to produce sharp revenue growth and improved utilization of manufacturing capacity.
See why 44 investors see AXT as 33% undervalued.
Result: Fair Value of $91.60 (UNDERVALUED)
Still, AXT’s heavy reliance on Chinese customers and ongoing export permit uncertainty could weaken the bullish case quickly if shipments stall or orders roll over.
Find out about the key risks to this AXT narrative.
Another View: AXT looks expensive on sales
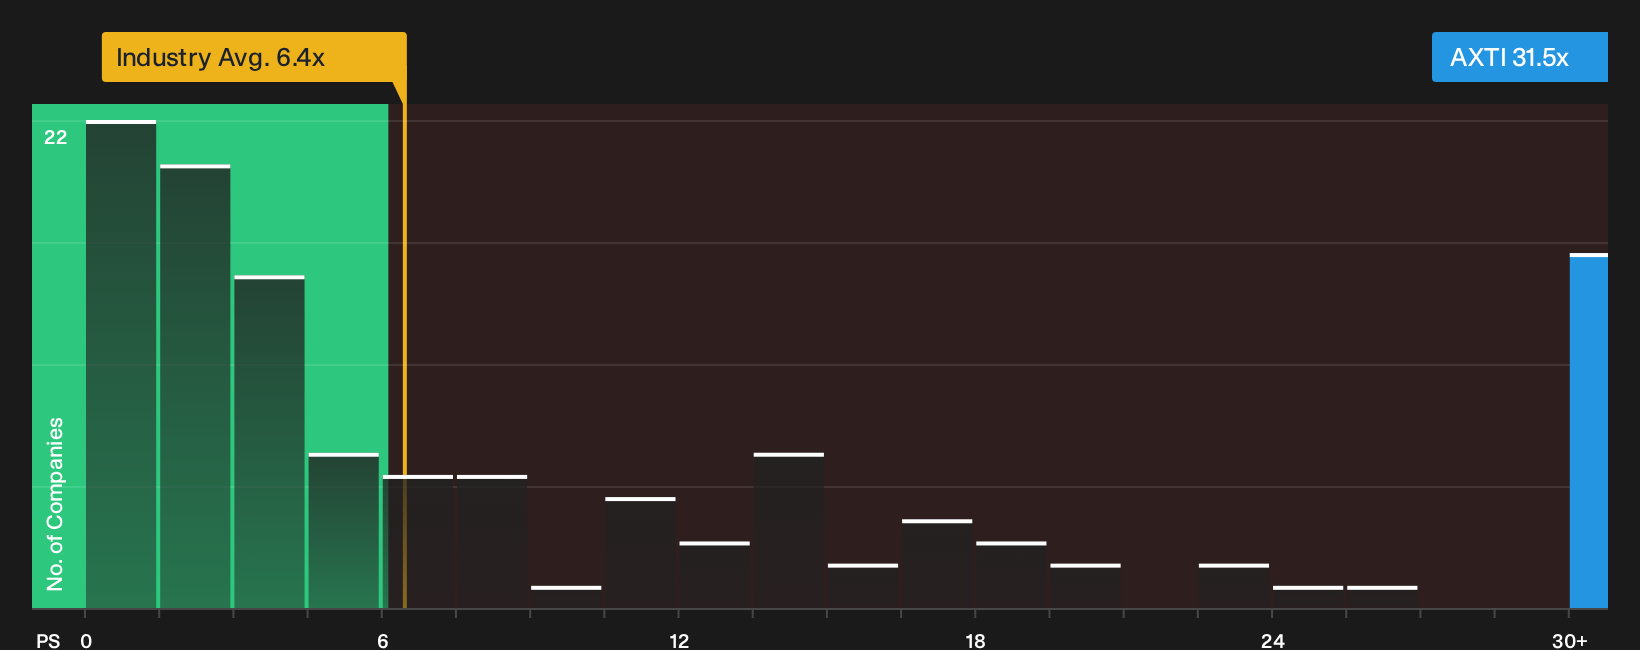
While the most popular AXT narrative leans on a $91.60 fair value, the picture changes when you look at what investors are paying for current revenue. The stock trades on a P/S of 31.5x, compared with 6.4x for the US Semiconductor group and 3.5x for peers.
The fair ratio for AXT is estimated at 26x P/S, which still sits well above industry levels but below where the shares trade today. That gap suggests valuation risk is meaningful if expectations cool. The key question is whether the revenue and earnings story can keep justifying such a rich multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on AXT’s valuation and fundamentals make this a stock you need to evaluate independently, not just read about. Consider the current sentiment and carefully compare the bullish and bearish perspectives with the 2 key rewards and 3 important warning signs.
Looking for more AXT alternatives and fresh ideas?
Do not stop at AXT. Broaden your watchlist with other potential opportunities that fit clear, evidence based criteria so you are not relying on a single story.
- Target resilient balance sheets and solid fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that can help anchor your portfolio when sentiment shifts.
- Zero in on quality at a reasonable price by using the 32 high quality undervalued stocks that filters for companies with strong financials trading below their estimated worth.
- Prioritize stability and consistent cash returns by reviewing the income focused 7 dividend fortresses that highlights higher yielding businesses with robust payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com