
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How India Hotel Debut At Marriott International (MAR) Has Changed Its Investment Story
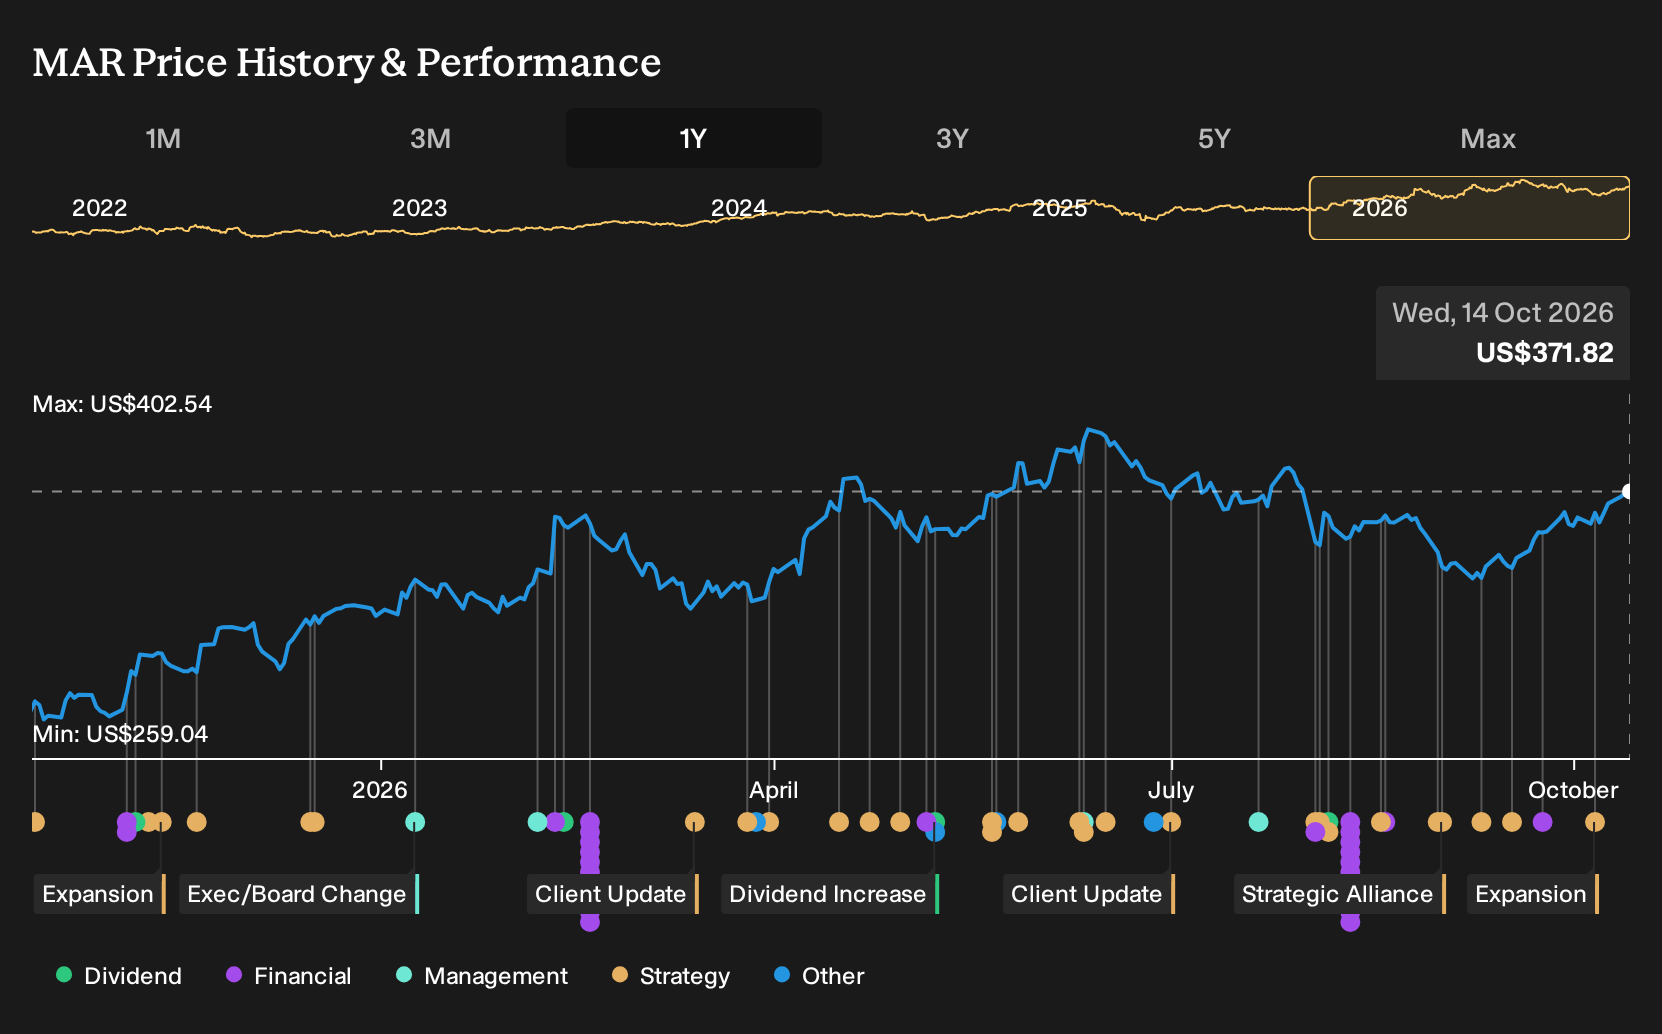
- Marriott International has opened JW Marriott Costa Elena Resort & Spa in Costa Rica as its first all-inclusive resort and launched City Express by Marriott in India with a 56 room hotel on the Udaipur–Nathdwara Highway, widening its reach from luxury leisure to value focused midscale travel.
- The twin moves into all inclusive luxury and affordable midscale lodging highlight Marriott International’s push to serve a wider mix of travelers while relying on fee based expansion rather than owning more real estate.
- Now the focus turns to how Marriott International’s investment narrative around fee based global growth compares with this City Express India expansion.
Marriott International Investment Narrative Recap
To be comfortable owning Marriott International, you need to believe the fee based model, a large room pipeline and Marriott Bonvoy can keep doing the heavy lifting even as owner economics get recalibrated. The openings in Costa Rica and India fit that story but do not change it. The near term swing factor still looks like execution on tech and loyalty so higher margin fees keep compounding.
The biggest watchpoint remains pressure from weaker Middle East RevPAR and any drag on global room additions or project timelines. Bonvoy givebacks and more support to owners also put a spotlight on margins. If these owner friendly moves do not translate into healthier net unit growth and fee revenue, earnings could be squeezed.
Against that backdrop, the launch of Series by Marriott is an important piece to watch alongside Costa Elena and City Express. Soft branding lets independent hotels plug into Marriott International distribution and technology while keeping their own identity. For you as a shareholder, the appeal is simple. More rooms can join the system without Marriott writing big checks for real estate.
This matters for the catalyst that analysts focus on most. A record pipeline of about 629,000 rooms, plus Series conversions, supports the prospect of higher fee income as properties open or switch flags. Execution risk is clear. If owner interest cools, or tech and loyalty do not deliver the expected uplift in bookings and pricing power, that rooms pipeline becomes slower fee growth rather than a tailwind.
What The Marriott International Forecasts Are Really Asking You To Believe
Analysts sketch a bold arc for Marriott International over the next few years, and it is worth slowing that story down into concrete numbers. The current revenue outlook assumes yearly top line growth of 60.7% for the next 3 years, which sets a high bar for what the fee based model, new openings and loyalty partnerships need to deliver. Earnings today sit at about US$2.6b, with consensus expectations pointing to US$3.9b of profit by 2029, which is an increase of roughly US$1.3b. On that framework, forecasts converge on 2029 revenue of US$30.7b and earnings of US$3.9b as the core case.
Uncover why Marriott International's fair value is essentially in line with its current price.
Exploring Other Perspectives
One alternate angle you might explore is how optimistic analysts lean into Marriott International’s fee potential from international expansion. Before the Costa Elena and City Express headlines, the most bullish forecasts were already sketching revenue of about US$37.0b and earnings near US$4.3b by 2029. That is a much richer story than the US$30.7b and US$3.9b that the broader group had in mind, and fresh all inclusive and midscale openings could easily shift those views again. It is worth comparing both sets of assumptions yourself, so you see how differently reasonable people can read the same business.
Explore 4 other Marriott International fair value estimates, including one that suggests as much as 14% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Marriott International research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marriott International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marriott International's overall financial health at a glance.
Looking for more Marriott International style investment ideas?
If the Marriott International story around fee based expansion, loyalty economics and capital light growth appeals to you, it can pay to keep a wider watchlist of companies building along similar lines. The Simply Wall St Screener is a useful way to scan for stocks that match your preferred mix of quality, balance sheet strength and risk profile without having to comb through every market manually.
- For investors who want quality businesses at prices that still look reasonable, start with a curated set of 32 high quality undervalued stocks that already show stronger fundamentals than their current market tags might imply.
- If capital preservation sits high on your priority list, focus on companies that aim for steadier earnings and fewer financial surprises by filtering through a 32 resilient stocks with low risk scores to narrow your options.
- When the goal is to find resilient balance sheets that can handle tougher conditions, look through a list of solid balance sheet and fundamentals (25 results) and concentrate on businesses that keep leverage in check while funding future growth.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com