
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Baseball Futures Launch At CME Group (CME) Has Changed Its Investment Story
- CME Group has launched the world’s first Baseball futures contracts, tied to CMEFutureSports Performance Indexes that convert official team statistics for 30 professional clubs into rules based financial benchmarks, with both standard and micro contract sizes traded nearly around the clock on a regulated, centrally cleared exchange.
- This move extends CME Group’s derivatives franchise into sports performance, creating a new data and fee pool built on IOSCO aligned benchmark methodologies. This development could matter for how the business scales its product offering beyond traditional interest rate, equity, and commodity contracts.
- We will now look at how CME Group’s new baseball futures platform could influence the broader investment narrative around product expansion.
Scan how CME Group’s move into baseball contracts compares with other exchanges pushing into niche derivatives by reviewing the hand picked 32 resilient stocks with low risk scores built around resilient business models and balance sheets.
CME Group Investment Narrative Recap
To own CME Group, you need to believe it can keep defending its benchmark franchises in rates, equity indexes and commodities while steadily extending into new contracts such as sports, crypto and power. The key near term swing factor remains derivatives volume and open interest, which are closely tied to risk management demand from institutions and a growing pool of retail traders.
The biggest operational risk still sits with competition in core asset classes and any pressure this creates on pricing, share in key contracts and ultimately margins. Baseball futures and other new lines look incremental rather than transformational in the short run, so they do not materially change the near term risk reward skew on their own.
Among recent developments, the use of CME Group’s FedWatch tool to gauge the jump in rate hike odds after the latest inflation print is highly relevant. It reinforces how central the group’s interest rate complex and related analytics remain to global hedging activity, which feeds directly into transaction fee revenue and market data demand.
That same backdrop of higher rate uncertainty highlights both the opportunity and the threat. Elevated policy debate can support volume in flagship contracts while rivals target the same flow in futures and swaps. Baseball futures and other new products sit alongside this core rate complex as a supplementary catalyst, giving CME Group another venue to test product design, index governance and clearing infrastructure without changing what most investors still view as the main engine of the business.
CME Group Forecasts Behind The Baseball Futures Story
CME Group's narrative projects US$8.0b revenue and US$4.6b earnings by 2029. This is based on analyst assumptions of 5.6% yearly revenue growth and implies an earnings increase of about US$0.3b from US$4.3b today.
Uncover why CME Group's fair value is essentially in line with its current price.
Exploring Other Perspectives
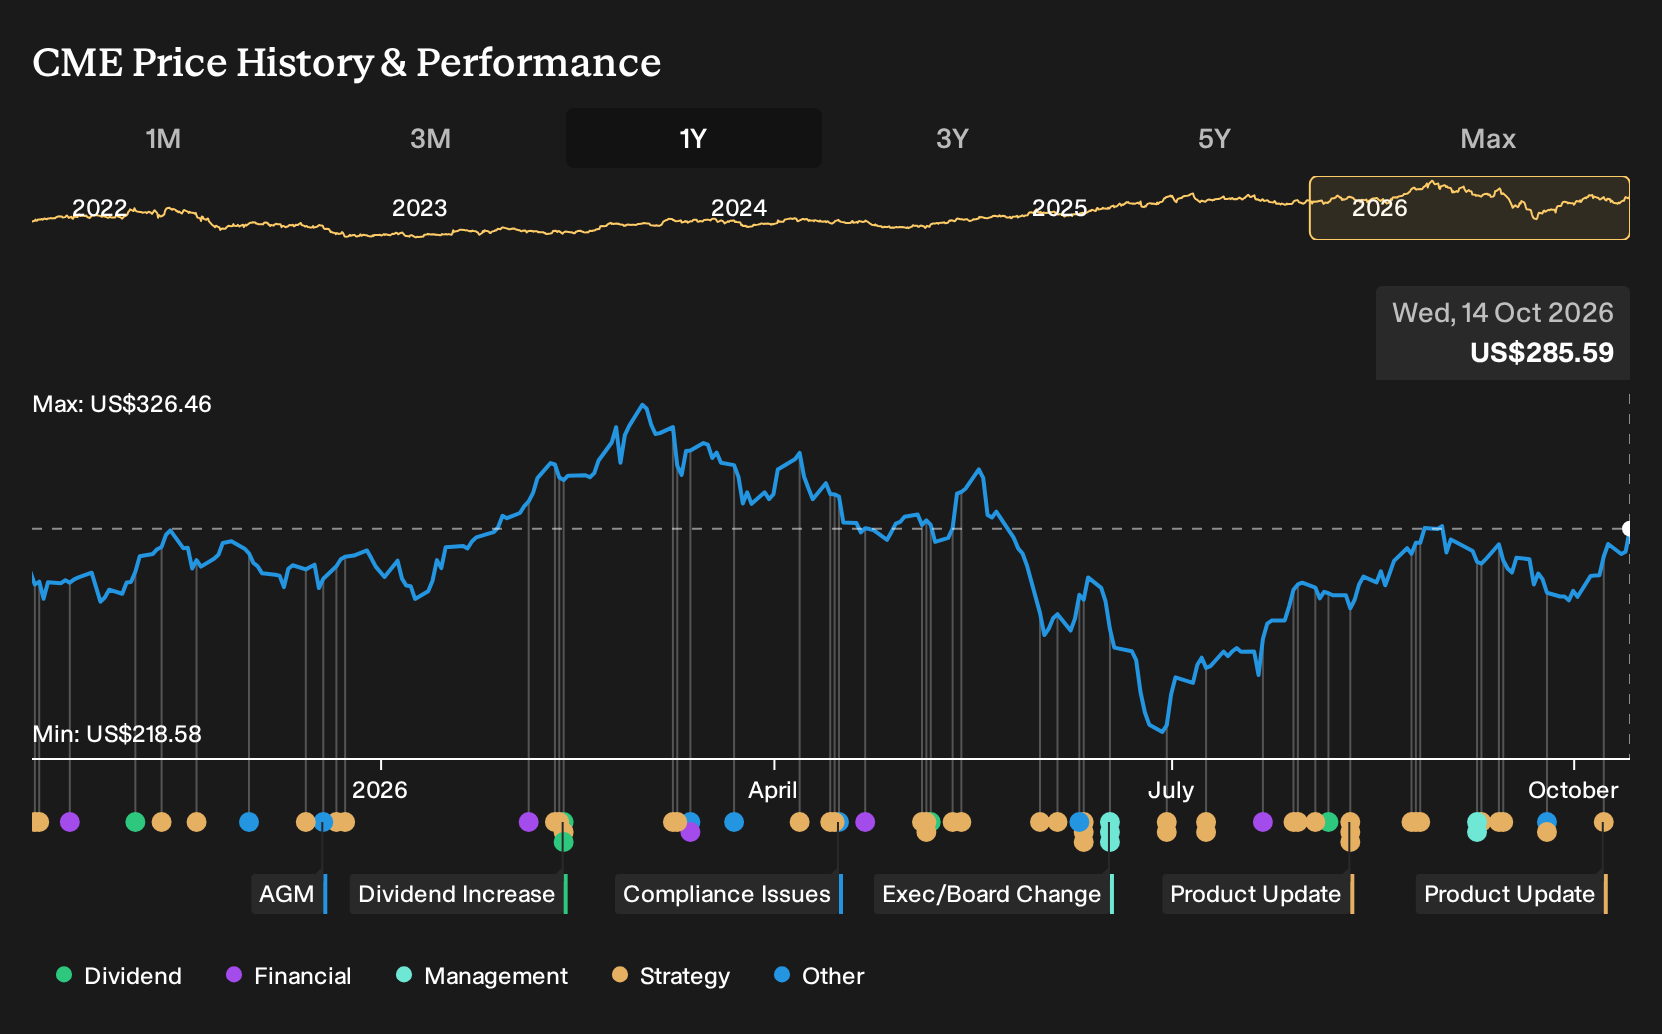
Across three fair value estimates from the Simply Wall St Community, CME Group is priced between about US$247.82 and US$292.88, a fairly tight band that still shows how far private views can diverge. When you set that against rising competition worries and fresh product launches such as baseball futures, there are plenty of reasons to explore multiple viewpoints before deciding how CME Group fits into your portfolio.
Explore 2 other CME Group fair value estimates, including one that suggests it could be worth as much as $292.88.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CME Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CME Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CME Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond CME Group?
If the baseball futures story has sharpened your interest in listed exchanges and risk platforms, it can be useful to set CME Group alongside other businesses with very different profiles. A structured screener lets you filter for balance sheet strength, income potential or mispriced quality, so you are not relying on headlines alone to build your watchlist.
- For investors who care most about resilience and capital preservation, start with a curated 32 resilient stocks with low risk scores that focuses on businesses with lower risk scores and steadier fundamentals.
- If value is your main filter, compare CME Group with companies that currently look mispriced on quality and fundamentals through the targeted 32 high quality undervalued stocks.
- Income focused investors can hunt for sturdier yield opportunities by scanning the high yield fortress style 7 dividend fortresses and seeing which payouts look better supported by underlying financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com