
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Corcept Therapeutics (CORT) Undervalued Or Is Its Big Run Already Priced In?
Options activity around Corcept Therapeutics (CORT) has picked up after the November 20, 2026 $47.50 put contract showed unusually high implied volatility, which some traders see as a signal of a potentially sizeable price swing.
Corcept Therapeutics has cooled off after a huge run, with the share price down 1.33% over the past day and 2.82% over the past week, yet still showing a 29.55% 90 day share price return and a 204.27% year to date share price return. The 5 year total shareholder return of 496.66% suggests that recent volatility is being measured against a very strong longer term record.
Scan for other high momentum pharmaceutical and biotech stories by checking the hand picked 20 high quality undiscovered gems that share some of the same fast moving traits as Corcept Therapeutics.
Corcept Therapeutics now sits at the crossroads of story and sentiment. Is this sharp rerating tied to the underlying cortisol franchise, or are options traders simply amplifying mood swings around the stock’s valuation setup?
Most Popular Narrative: 18% Undervalued
At a last close of $116.23 against a most-followed fair value of $141, the current Corcept Therapeutics share price sits below what that narrative implies, which keeps the focus on whether the cortisol pipeline can earn its way into that gap.
The shift from a single Cushing’s product to a broader cortisol modulation portfolio, including Lifyorli in ovarian cancer, late-stage oncology programs, and Phase II or III efforts in ALS and MASH, points to a more diversified revenue base and potential improvement in earnings resilience as dependence on any one product declines.
See why 61 investors see Corcept Therapeutics as 18% undervalued.
Result: Fair Value of $141 (UNDERVALUED)
Still, the Corcept Therapeutics story can fray quickly if Korlym concentration and the recent shift from profit to a loss continue to weigh on confidence.
Find out about the key risks to this Corcept Therapeutics narrative.
Another View: Corcept Therapeutics Through A Sales Lens
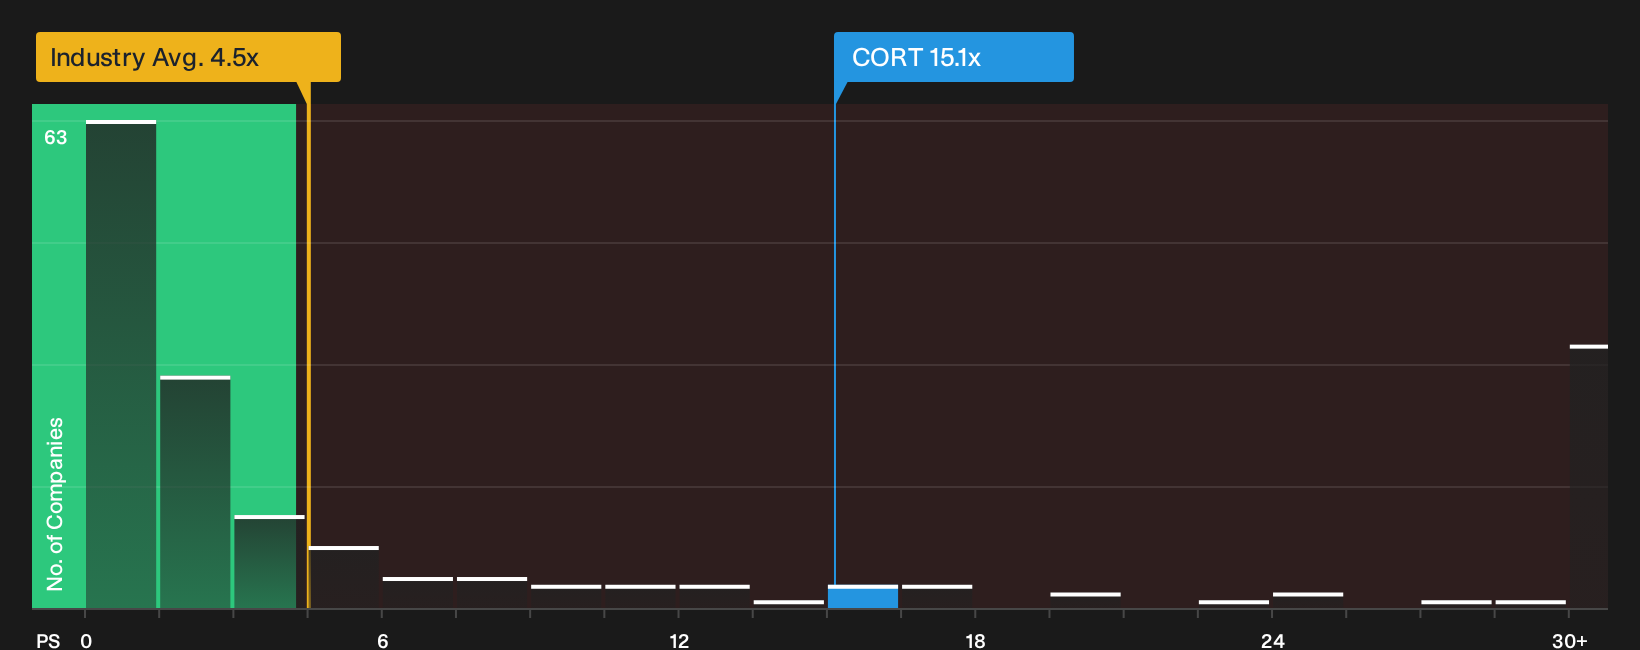
Corcept Therapeutics looks cheap against the $141 fair value from the most followed narrative, yet the sales based yardstick sends a different message. The stock trades on a P/S ratio of 15.1x compared with 4.5x for the wider US Pharmaceuticals group and 6.9x for peers.
The fair ratio sits at 16x, only slightly above today’s level, which suggests less room for multiple expansion and more sensitivity if sentiment cools. For investors weighing the story, the question becomes whether future execution justifies Corcept living this far above its sector on P/S.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Corcept Therapeutics is split, and that is exactly when fresh data can matter most. Move quickly and pressure test the story for yourself by weighing its 2 key rewards and 2 important warning signs
Looking for more Corcept Therapeutics style ideas?
Do not stop your research with Corcept Therapeutics alone. Fresh ideas often come from scanning beyond the obvious, so widen your net before the next move runs away.
- Hunt for quality at a discount by checking our 32 high quality undervalued stocks that filters for strong fundamentals at prices that may not fully reflect them.
- Lock in potential income streams by reviewing the 7 dividend fortresses that highlights companies combining higher yields with more durable payout profiles.
- Protect your downside first by focusing on stability through the 32 resilient stocks with low risk scores that spotlights businesses with more resilient risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com