
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missile Defense Certification Might Change The Case For Investing In Ondas Stock (ONDS)
- Ondas Holdings reported that its Airborne Missile Protection System was successfully installed and certified by the European Union Aviation Safety Agency for a Bombardier Global 7500. This confirms the platform meets rigorous international aviation safety requirements and expands its addressable market in airborne defense and aircraft protection.
- This EASA certification signals that Ondas can execute complex, high-spec defense integration projects, which matters for future contract credibility, pricing power, and competitive positioning across its broader autonomous systems and security portfolio.
- We will look at how Ondas' EASA certified missile protection system reshapes the investment narrative around defense scale and execution quality.
Scan other defense and autonomy stocks moving on similar contract credibility stories with the hand picked 91 robotics and automation stocks focused on security, drones, and automated systems.
Ondas Investment Narrative Recap
For an investor to own Ondas, there needs to be confidence that autonomous systems, counter drone platforms and private wireless solutions can convert current programs into durable orders without eroding margins. The recent EASA certification for the Airborne Missile Protection System supports that belief only at the execution level. It validates that Ondas can deliver complex, regulated projects but does not by itself change the near term revenue profile.
The key near term swing factor still sits with Ondas Autonomous Systems, where management is working to turn backlog across Optimus, Iron Drone and related defense work into realized sales. The biggest risk remains the cost base and funding mix. High operating expenses, volatile margins, debt of about US$52m and a history of shareholder dilution leave little room if contract timing slips again.
The development that most closely ties into this missile protection win is the broader push across Ondas Autonomous Systems into defense and homeland security programs using Optimus and Iron Drone systems. The EASA approval sits alongside those efforts as proof that the group can satisfy strict aviation and security standards on live deployments, not just in trials.
That matters for the catalyst investors often focus on. A ramp in OAS revenue, helped by expanding defense programs in Israel and the UAE and supported by the Palantir AI partnership, depends on repeat contract awards and scaling deployments. The more Ondas shows it can execute tightly specified work like AMPS, the stronger its case when competing for complex, higher value security and counter UAS projects.
Ondas' current analyst story points to forecast revenues of US$1.6b and earnings of US$31.0 million by 2029, based on assumptions that the top line will grow at 110.2% per year while profits shift from US$85.8 million today to the lower 2029 consensus. This implies an earnings decline of US$54.8 million over that period.
Discover how Ondas' fair value points to a 207% potential upside compared to its current price before that type of discount begins to narrow.
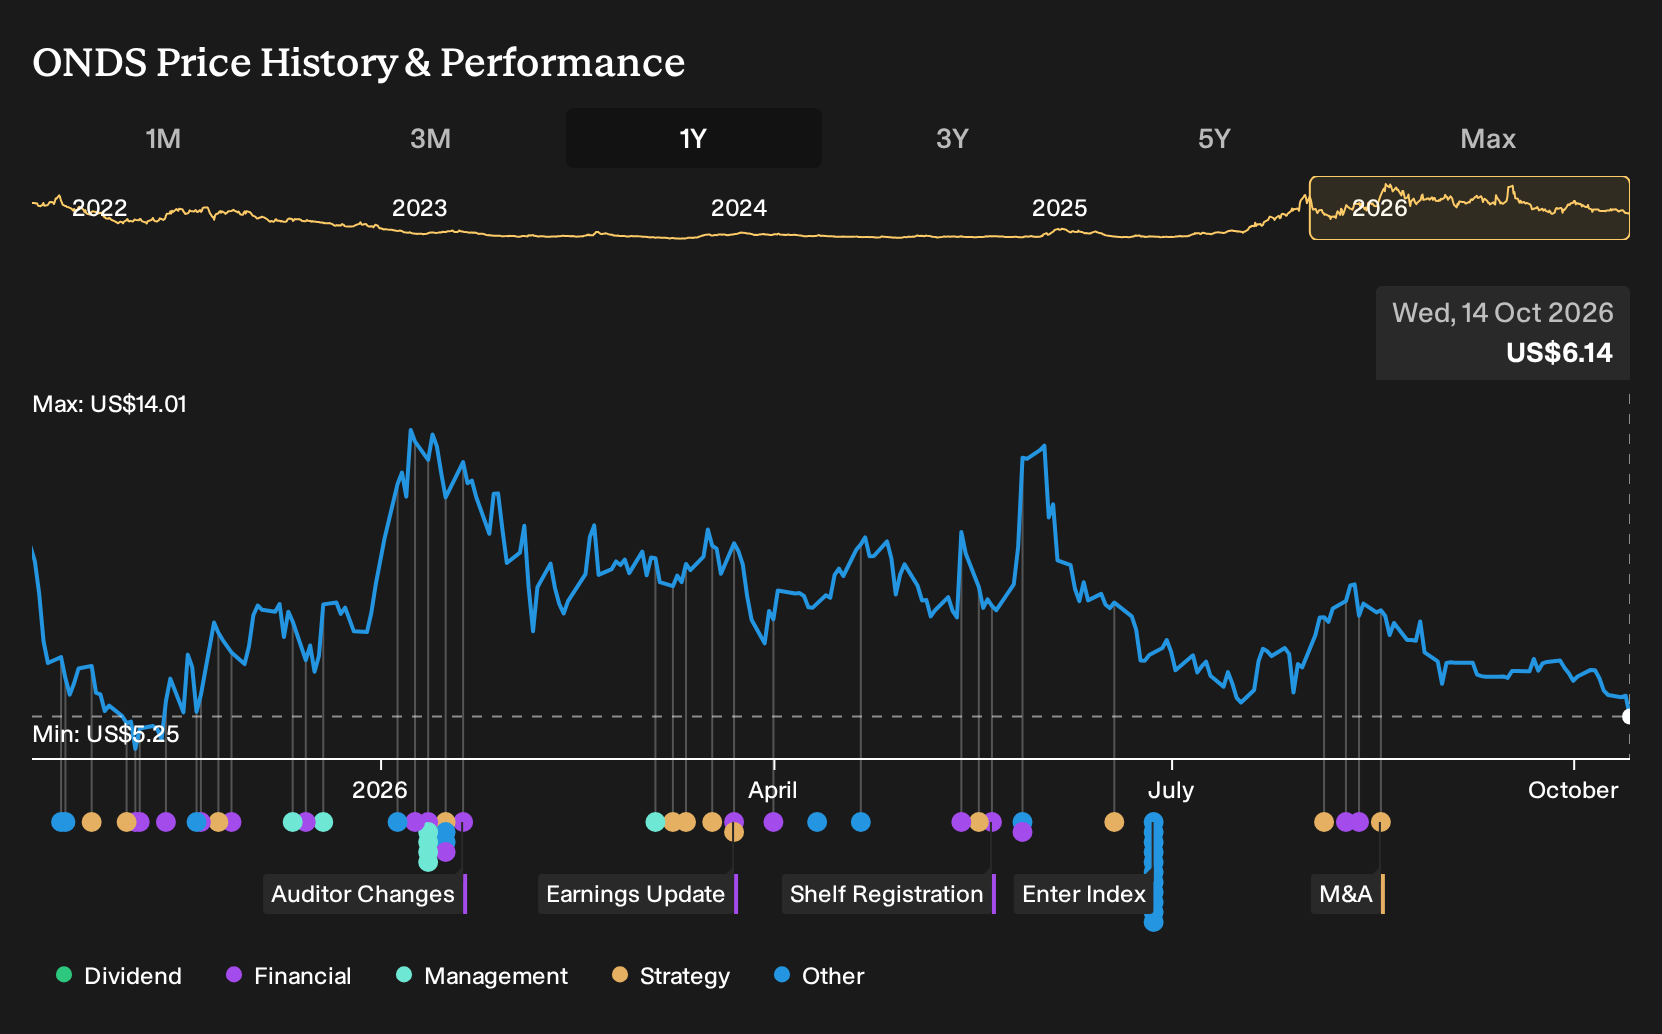
Exploring Other Perspectives
One alternate take is that Ondas’ heavy counter drone push and acquisition pipeline could become the real swing factor rather than single certifications like AMPS. The most pessimistic analysts were working off roughly US$1.3b of 2029 revenue and US$148.7 million of earnings, yet still set the lowest target. That shows how far opinions stretch. Use this EASA news as a cue to compare those pre news forecasts with your own expectations and decide which camp feels closer to your view.
Explore 8 other Ondas fair value estimates, including one that suggests it could be worth just $7.89!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ondas research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Ondas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ondas' overall financial health at a glance.
Looking For More Ideas Beyond Ondas?
Once you have a view on Ondas, it helps to cross check that thesis against other opportunities that fit different risk and income profiles. The Simply Wall St Screener is a quick way to line up comparable stocks, stress test your assumptions, and build a watchlist that is not reliant on a single defense or autonomy story.
- If you want potential upside but still care about balance sheet strength, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without constant refinancing risk.
- For investors who prioritize valuation discipline, compare Ondas to a 32 high quality undervalued stocks that combine quality fundamentals with pricing that may leave more room for future returns.
- Income focused portfolios might benefit from adding a few 7 dividend fortresses that aim to pair meaningful yields with business models built around recurring cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com