
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DXC Stock Gets A LangChain AI Partnership Boost
- DXC Technology reported a past partnership with LangChain, bringing LangGraph and LangSmith into its OASIS platform to run governed AI agents in mission critical IT environments that are already moving toward 125 customer deployments.
- The company is using this LangChain technology inside OASIS to cut incident resolution times from up to days to minutes, while maintaining human approval on sensitive actions and detailed traceability of every decision.
- We will now look at how DXC Technology's LangChain powered OASIS rollout might influence the existing investment narrative around AI execution.
Scan other governed AI and automation opportunities that echo DXC Technology's OASIS story by reviewing our handpicked 92 AI infrastructure stocks alongside this LangChain partnership news.
DXC Technology Investment Narrative Recap
To own DXC Technology, you need to believe the pivot from shrinking, labor heavy IT contracts toward AI led platforms can eventually stabilise revenue and lift margins. The OASIS and agentic AI push goes straight at that problem. The LangChain tie up helps execution on that plan but does not, on its own, resolve the current top line pressure or weak profit margins.
In the near term, the key swing factor is whether bookings and live AI deployments translate into steadier organic revenue after guidance for a 3% to 5% decline. The biggest risk is that Global Infrastructure Services and other legacy activities keep eroding faster than AI and software offerings like OASIS, CoreIgnite and insurance platforms can grow. At the same time, high debt and legal overhang limit flexibility.
The insurance focused announcement on the Assure Platform is highly relevant to the OASIS and LangChain story. Both efforts point to DXC Technology leaning on governed AI and workflow automation within mission critical environments rather than chasing more commoditised IT outsourcing. That matters for you because it speaks directly to the mix shift toward higher margin, product like revenue.
Assure Smart Apps, the broadened Assure Platform and planned integration with the London Market Core Platform all show DXC Technology trying to layer AI and automation on top of long lived insurance systems. This direction ties into the same catalysts investors watch in OASIS bookings, including efficiency gains, recurring software and SaaS revenue, and the question of whether these newer platforms can offset revenue declines in older segments.
DXC Technology's current analyst narrative points to forecast revenue of US$11.9b and earnings of US$169.4 million by 2029. This is presented alongside an assumed yearly revenue decline of 1.7% and an earnings increase of about US$45.4 million from the US$124.0 million reported today.
Uncover why DXC Technology's fair value points to a 12% potential downside to its current price, indicating that the existing premium may not be sustainable.
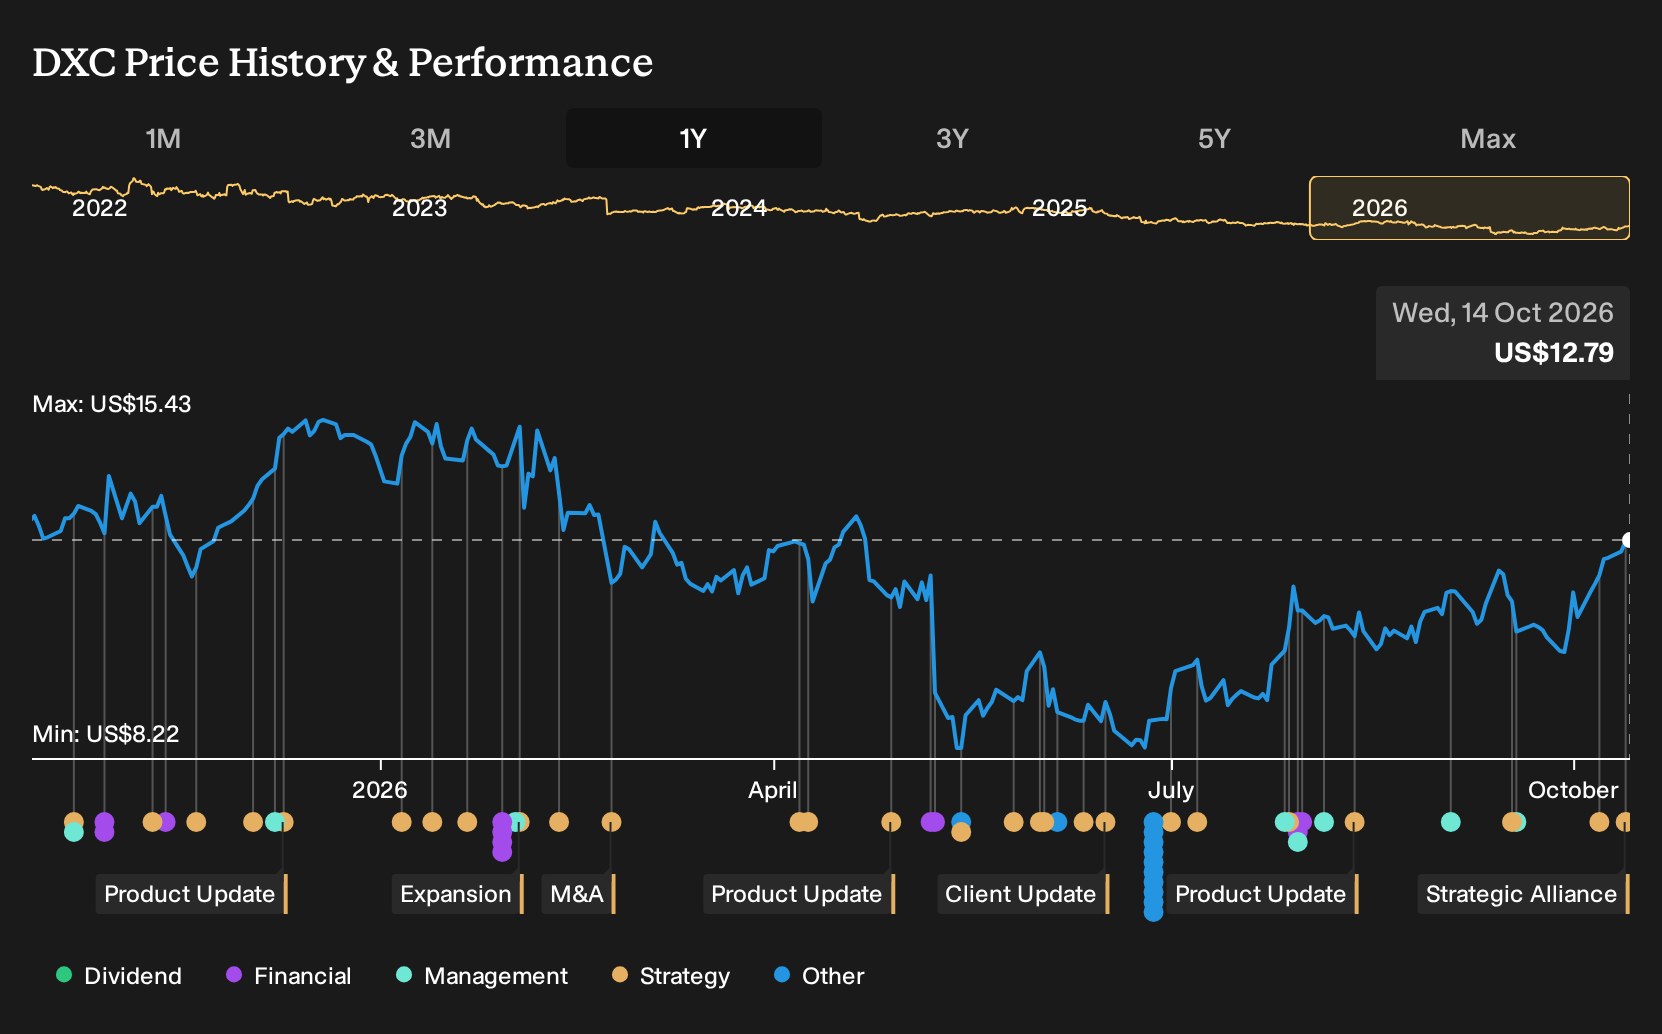
Exploring Other Perspectives
One alternate view hangs on DXC Technology’s margin story rather than its revenue slide. The most optimistic analysts were pencilling in earnings of about US$186.9 million on roughly US$12.3b of sales by 2029, compared with the baseline US$169.4 million on US$11.9b. Those forecasts came before this LangChain partnership, so opinions may shift.
Explore 3 other DXC Technology fair value estimates, including one that suggests as much as 175% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DXC Technology research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for DXC Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DXC Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond DXC Technology?
If DXC Technology has sharpened your thinking on AI execution and turnarounds, you can use that same lens to scan a wider field of opportunities with the Simply Wall St Screener and compare how other businesses stack up on quality, value and resilience.
- If you want potential upside together with strong finances, start with a 20 high quality undiscovered gems that combines robust fundamentals with less widely followed tickers.
- For investors who care most about balance sheet strength and staying power, narrow your list using a list of solid balance sheet and fundamentals (25 results) that filters for healthier leverage and liquidity profiles.
- When capital preservation sits near the top of your checklist, focus your research on a 32 resilient stocks with low risk scores so you can compare businesses with lower overall risk scores side by side.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com