
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 UK Consumer Staples Stocks Worth Watching As Energy Bills Squeeze Household Budgets
UK households are wrestling with higher energy debts and rising gas costs, and that pressure does not hit every corner of the market in the same way. When utility bills eat into pay packets, spending habits can shift and some defensive consumer staples can look relatively steadier compared with more cyclical areas. This article walks through 3 stocks from our screener that appear better placed in this utility cost squeeze and explains why each might deserve a closer look.
The three stocks that follow are just a starting sample, and the full screen on Simply Wall St surfaced 8 more UK consumer staples with equally compelling stories that are not covered in this article.
If you want to identify which of these defensive plays best fits your own risk and income goals, head straight into the UK Defensive Consumer Staples Amid Utility Cost Squeeze screener
Reckitt Benckiser Group (LSE:RKT)
Reckitt Benckiser Group taps directly into the screener theme, with everyday health, hygiene and nutrition products that consumers tend to keep buying even when energy bills climb and other spending is cut back.
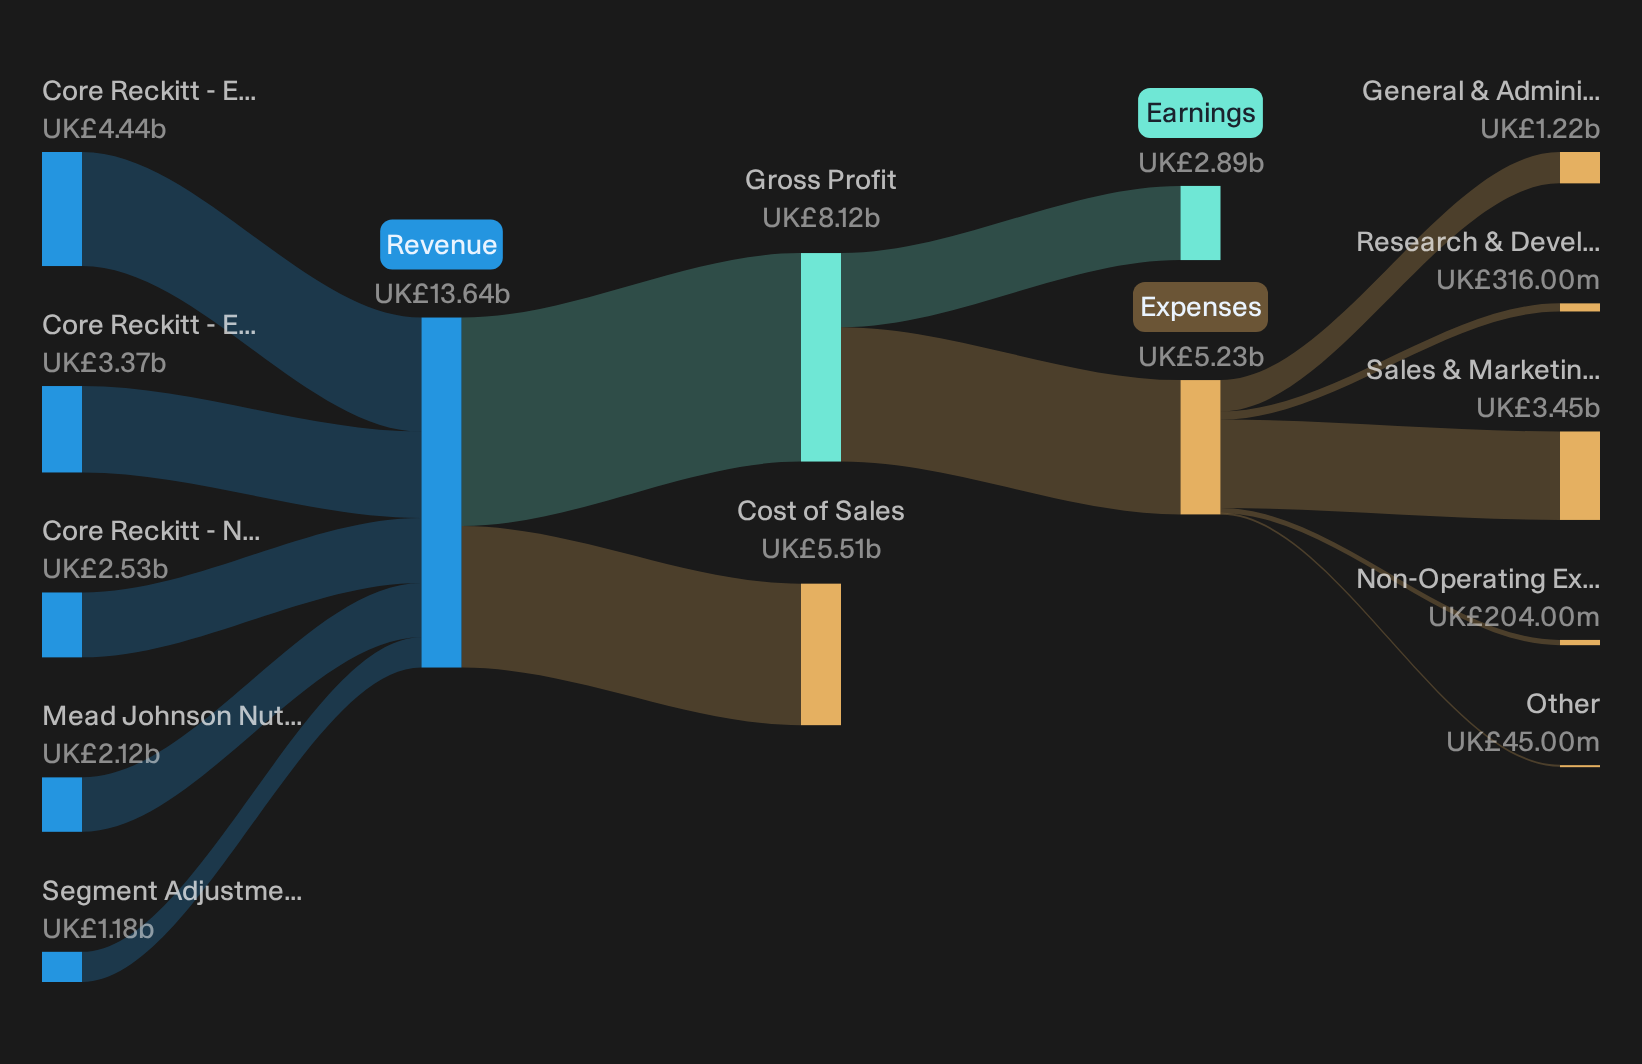
Reckitt Benckiser Group sells essential health, hygiene and infant nutrition brands like Dettol, Durex, Lysol and Enfamil that fit the consumer staples brief in a utility squeeze. Revenue leans on Core Reckitt Emerging Markets at £4.4b, ahead of Europe at £3.4b, North America at £2.5b and Mead Johnson Nutrition at £2.1b, with segment adjustments of £1.2b. The group is a large cap with a market value of about £34.1b.
For investors looking at defensive consumer staples, Reckitt Benckiser Group offers a mix of everyday products, global reach and a business model that can matter when household budgets get tight.
"Expansion in emerging markets and ongoing product innovation are associated with higher margins and may influence Reckitt's revenue profile."
The real swing factor is how one unresolved cost and pricing pressure shapes future earnings quality and the resilience of those margins.
That margin question is exactly what the full narrative for Reckitt Benckiser Group unpacks, separating short term cost noise from longer term earnings power and pricing strength.
Tesco (LSE:TSCO)
Tesco is the bellwether for this screener theme, because when energy bills bite and shoppers trade down, the weekly grocery basket still runs through its tills. That is where its mix of big stores, convenience outlets and wholesale reach really starts to matter.
Tesco runs supermarkets, convenience outlets, online grocery and food wholesale, plus side businesses like mobile, insurance and data services. It is anchored by £60.0b from United Kingdom and Republic of Ireland and £8.9b from Booker, and carries a market value of about £32.8b.
"Tesco's continued focus on boosting customer satisfaction through investments in quality, innovation in its fresh and Finest ranges, and better shopping experiences, backed by UK market share gains of more than 100 bps over four years, is expected to support future revenue growth."
What really moves the dial for Tesco now is how one quiet cost pressure interacts with that value promise when household budgets feel the strain.
That quiet cost pressure is exactly what the full narrative for Tesco unpacks, showing where Tesco's value promise could be accelerating or quietly stalling next.

Associated British Foods (LSE:ABF)
Associated British Foods brings together everyday food brands, agricultural products, ingredients and the Primark retail chain, with Grocery at about £4.1b, Retail roughly £9.7b and Ingredients near £2.2b in revenue, plus Sugar and Agriculture, and a market value around £13.3b.
For the UK Defensive Consumer Staples Amid Utility Cost Squeeze theme, Associated British Foods matters because its food and ingredients arms sell essentials that tend to stay in the basket even when energy bills climb. Primark, meanwhile, is working to keep value shoppers loyal as wallets tighten.
"The rollout of digital initiatives and Click & Collect in Primark has moved on, with nationwide coverage in Great Britain and strong website traffic growth. The planned launch of UK home delivery from the new Sheffield depot is aimed at lifting customer reach and like for like sales while supporting Primark margins."
What really shapes how defensive Associated British Foods feels now is how one cost sensitive part of the group holds up if household budgets stay squeezed.
If that cost sensitive segment is where your attention goes first, the full narrative for Associated British Foods explains how Primark and the wider group could be separating from more budget-conscious shoppers.

Seeking Fresh Alternatives Beyond Today
Some of the most interesting ideas often move first, and by the time the crowd catches on the best entry points are gone. Scan fresh breakouts and under the radar strength before momentum is fully priced in and act now.
- Spot strong balance sheets before the story is widely known and sort through a curated list of solid balance sheet and fundamentals (9 results) while the strongest names are still flying under most investors' radars.
- Target resilient income opportunities and review a hand picked 3 dividend fortresses while yields still look appealing and share prices have not fully caught up.
- Ride structural shifts in computing and review a focused 25 quantum computing stocks while these potential breakout stories are still dropping under most investors' screens.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com