
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Viking Holdings (VIK) On Barclays Upgrade Is The Weather Setback A Buying Opportunity
Viking Holdings (VIK) drew fresh attention after Barclays shifted its stance on the stock, describing weather-driven weakness on European rivers as a temporary drag rather than a lasting business issue.
Viking Holdings has been through a mixed patch, with the share price down 4.42% over the past month and 15.77% over 90 days, yet still showing a 14.29% year to date share price return and a 33.77% total shareholder return over the past year. Recent moves, including the Barclays upgrade and the launch of the Viking Rota, have come as the stock tries to rebuild momentum from that pullback around the current US$82.60 level.
Spot fresh momentum ideas by comparing Viking Holdings with a curated group of travel and leisure plays screened as 20 high quality undiscovered gems.Bulls see a weather blip and a Barclays vote of confidence; bears see a premium cruise operator after a sharp run. Which side does Viking Holdings valuation currently lean toward?
Most Popular Narrative: 26% Undervalued
Against Viking Holdings last close of $82.60, the most followed narrative anchors fair value around $110.81. This implies a sizeable valuation gap that investors are trying to justify through growth, margins, and capital returns.
Advanced bookings for core products remain exceptionally strong, with 96% of 2025 capacity and 55% of 2026 capacity already sold at higher rates, indicating durable repeat demand and allowing for mid-single-digit pricing growth that directly benefits company earnings and net margins. Consistent investment in standardized, modern, and energy-efficient fleet across ocean and river segments enables tight operational control, better shipyard pricing, and scalable cost efficiencies that are expected to support ongoing margin expansion and improved long-term profitability.
See why 8 investors see Viking Holdings as 25% undervalued.
Result: Fair Value of $110.81 (UNDERVALUED)
Still, the Viking Holdings story carries clear pressure points, including heavy reliance on older affluent travelers and exposure to regulatory or environmental shocks on key European river routes.
Find out about the key risks to this Viking Holdings narrative.
Another View: Viking Holdings Through The P/E Lens
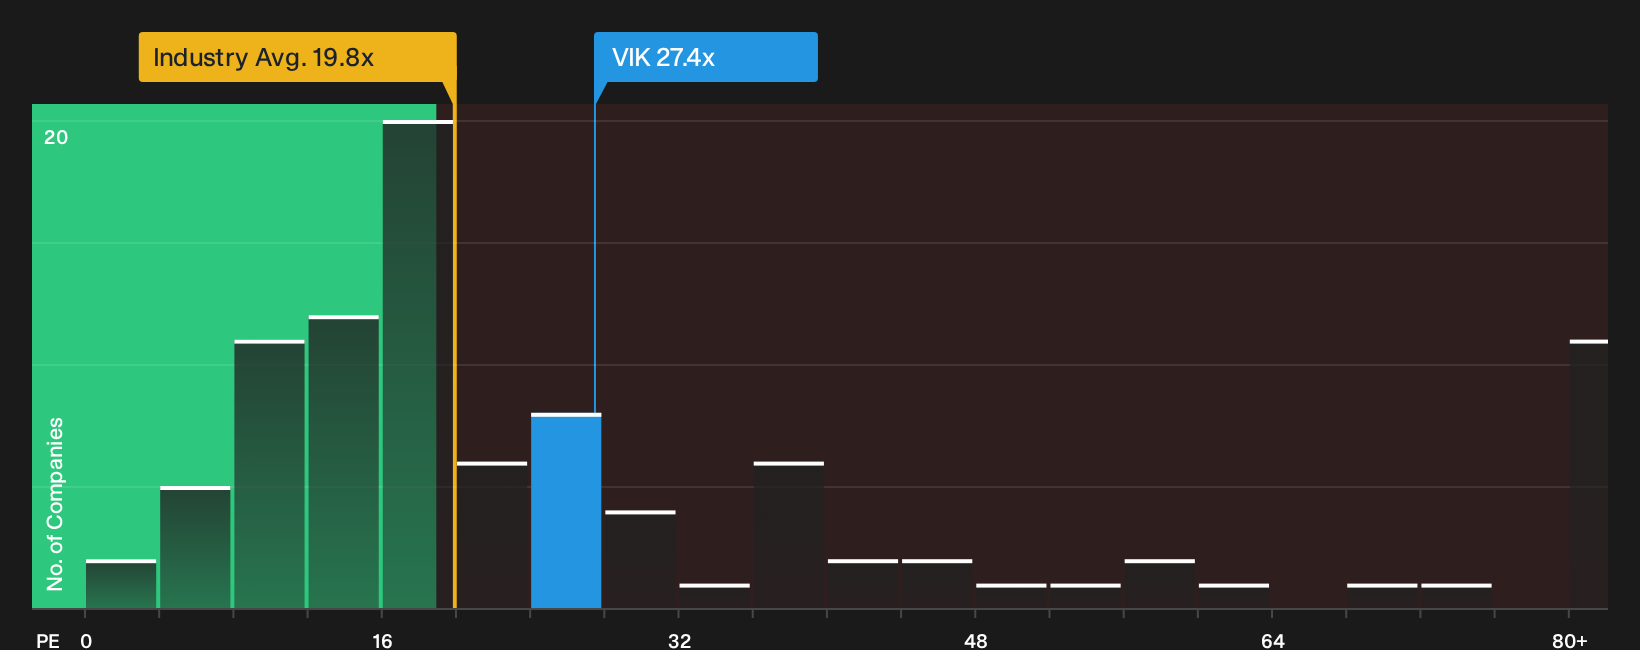
On price targets and fair value models, Viking Holdings looks underpriced. On simple earnings multiples, the picture is less forgiving. The stock trades on a P/E of 27.4x compared with a 19.9x average for the US Hospitality group and a 12.7x peer average, which points to a rich entry tag relative to many competitors.
The gap to the estimated fair ratio of 28.9x is small, so the current multiple sits close to where the market could reasonably settle if the story plays out. That mix, a premium to sector but near its fair ratio, leaves investors weighing whether they are paying up for quality or just compressing their margin of safety.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or a clear tilt in sentiment around Viking Holdings, either way the data is on the table and the clock is ticking for your own judgment. To weigh those pressure points against the upside case in one place, check the 4 key rewards and 1 important warning sign.
Looking for more Viking Holdings style investment ideas?
If you stop with Viking Holdings, you risk missing other opportunities that fit your approach. Put a few more high quality contenders on your radar quickly.
- Scan for mispriced quality and see which companies line up in the 32 high quality undervalued stocks before others start paying attention.
- Target resilience first by checking companies on the list of solid balance sheet and fundamentals (25 results) and focus your time on businesses with sturdier finances.
- Dial down portfolio stress by hunting for opportunities in the 32 resilient stocks with low risk scores and keep your next idea aligned with your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com