
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Microsoft (MSFT) Could Be 27% Overvalued As Maia 300 And Azure Growth Lift Sentiment
Microsoft (MSFT) is reshaping its AI story around hardware. The Maia 300 chip program, heavier data center spending, and strong Azure and cloud earnings now sit at the center of the stock’s narrative.
Recent price action reflects that excitement. Microsoft shares have climbed, with a 90 day share price return of 33.06% and a 30 day share price return of 5.60%. The 1 year total shareholder return sits at 4.80% and the 5 year total shareholder return at 80.89%. This pattern points to strong long term momentum supported by the Maia 300 announcement, record Azure revenue and fresh data center commitments, even as short term daily moves remain choppy.
Scan where Microsoft’s AI hardware push might rhyme with other opportunities by reviewing our curated list of 92 AI infrastructure stocks across the data center and cloud stack.
Bulls point to Microsoft’s record data center commitments and Maia 300 as proof the stock’s premium is earned. Bears flag heavy capital spend and accounting tweaks. Which side do the current valuation markers actually support?
Most Popular Narrative: 27% Overvalued
According to the most widely followed Microsoft narrative, the fair value sits at $419.91, well below the last close at $533.69. That gap frames the Maia 300 build out and heavier data center investment as a valuation stress test rather than a free pass.
The one real debate is capital intensity. Capex has roughly doubled to ~37% of revenue as Microsoft builds out AI infrastructure, and that has compressed free cash flow in the near term. The key point for a value investor is that this is funded from operating strength, not debt. Whether it earns a good return is the thing to watch, but the company is not stretching its balance sheet to do it.
See why 267 investors see Microsoft as 27% overvalued.
According to CubanEros, this story adds up to a high quality business where the current share price runs ahead of that $419.91 narrative estimate. The focus for anyone tracking Microsoft is whether the Maia 300 and cloud capex cycle turn that spending into durable earnings power that could later close the gap.
Result: Fair Value of $419.91 (OVERVALUED)
Still, the Microsoft story can wobble if AI capex fails to translate into higher quality earnings, or if accounting around the OpenAI stake clouds reported results.
Find out about the key risks to this Microsoft narrative.
Another View: Microsoft Through The Earnings Lens
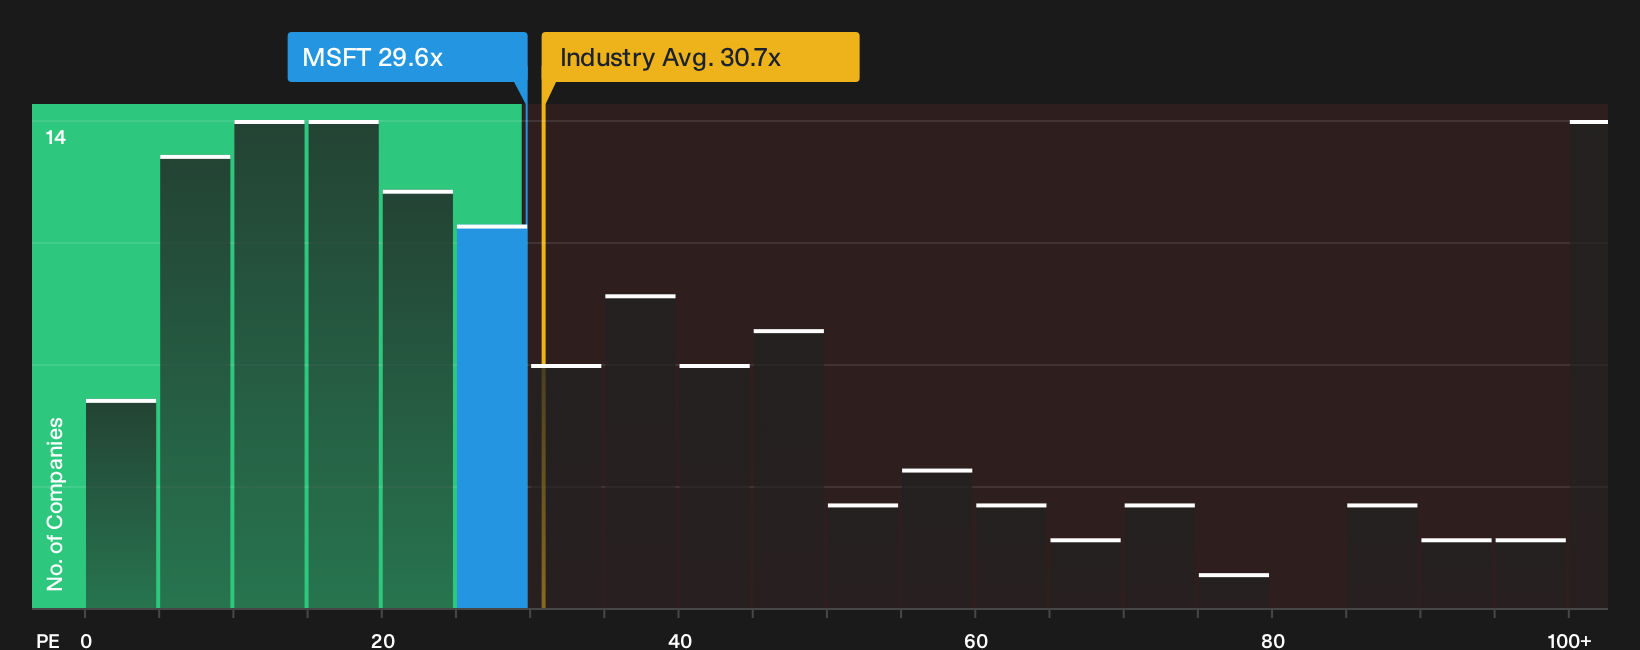
That 27% gap to the $419.91 fair value is only one way to frame Microsoft. On current numbers, the stock trades on a P/E of 29.6x, which is slightly below the US Software industry average of 30.7x and above the peer group on 26.2x.
The fair ratio sits much higher at 50.1x. If the market ever leaned closer to that level, today’s pricing would look less stretched. If sentiment moved back toward the 26.2x peer average instead, the premium narrative would feel very different. The question then becomes: which anchor do you treat as your starting point?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Microsoft is split, with strong AI optimism pulling against fresh concerns about spending and risk. Act promptly, review the underlying data yourself, and weigh the 3 key rewards and 1 important warning sign carefully.
Looking for more investment ideas beyond Microsoft?
Do not stop with Microsoft. Use the Simply Wall St screener to uncover other opportunities that fit your style before the market prices them more tightly.
- Target value first and hunt for companies that combine quality fundamentals with attractive pricing by scanning our 32 high quality undervalued stocks.
- Strengthen your defense and focus on resilience during tougher markets by reviewing a 32 resilient stocks with low risk scores that can help you sleep at night.
- Upgrade portfolio quality and search for rock solid finances using a curated list of solid balance sheet and fundamentals (25 results) with consistently robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com