
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why It’s Time To Load Up on GE Aerospace Stock
GE Aerospace (GE) will release its third-quarter financial results on October 20. So far in 2026, the stock has struggled to gain momentum and has lagged behind the broader market. Its shares have also fallen roughly 21% from their 52-week high.
Several factors have weighed on investor sentiment. GE Aerospace’s relatively high valuation has made investors more cautious. At the same time, rising oil prices have raised concerns about airline costs and the potential impact on air travel demand. If fuel costs remain elevated, commercial airlines could face additional financial pressure, creating uncertainty for the broader aviation industry.
However, GE Aerospace’s underlying business remains strong. Demand across commercial aviation and defense remains supportive, while its aftermarket services business provides another important source of revenue. This segment benefits from ongoing demand for aircraft engine maintenance, repairs, and replacement parts, helping support recurring revenue and profitability.
With these business drivers in place, GE Aerospace could deliver solid third-quarter results despite the broader market concerns. Strong performance in commercial aviation, defense, and aftermarket services could also help restore investor confidence and support the stock's recovery.
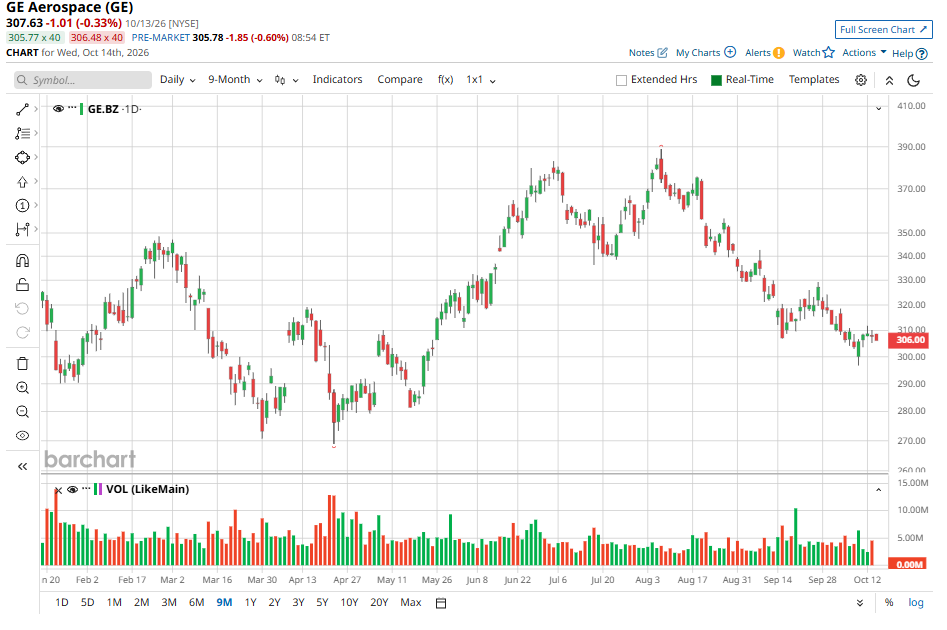
GE Aerospace Q3 Outlook
GE Aerospace appears well positioned heading into its third-quarter earnings report, supported by strong demand across its Commercial Engines & Services (CES) and Defense & Propulsion Technologies (DPT) businesses. Management has expressed confidence in the company’s second-half outlook and raised its full-year guidance.
The company delivered a strong second-quarter performance, largely driven by growth in commercial services. Orders rose 17%, with both business segments posting solid growth. Revenue rose 24%, led by a 27% increase in CES and 16% growth in DPT. Operating profit climbed 18%, while earnings per share (EPS) increased 22%. For the first half of the year, orders surged 49%, revenue grew 27%, and EPS advanced 24%.
Looking ahead to Q3, GE Aerospace could maintain this growth momentum. Strong order activity, rising demand for maintenance services, and healthy cash generation are likely to drive its performance.
The CES business is expected to benefit from airlines continuing to maintain and upgrade their existing fleets. This should support demand for engine overhauls, spare parts, and long-term service agreements. Growth in commercial equipment deliveries, particularly LEAP engines, could provide an additional boost.
The aftermarket business also remains a key strength. Demand for spare parts has been strong. GE Aerospace reported that 95% of its spare parts orders are in backlog, and it has secured all planned shop visits for the quarter. This provides good visibility into future service activity and supports expectations for continued revenue growth.
Meanwhile, the DPT segment should benefit from resilient defense spending and steady demand across its markets.
GE Aerospace has also built a strong track record of beating analysts’ earnings estimates, exceeding expectations in each of the past four quarters. In Q2 2026, it reported an 8.6% earnings surprise. For the upcoming quarter, Wall Street expects EPS of $2.01, a 21% year-over-year increase.
Overall, strong demand in commercial aviation, a growing services business, and resilient defense activity could help GE Aerospace deliver another solid quarter.
Load Up on GE Stock
GE Aerospace stock looks attractive ahead of its third-quarter earnings release. Strong demand for commercial aircraft equipment and services, along with a resilient defense business, could support continued growth. The company’s healthy order backlog, rising earnings, and upbeat full-year outlook also point to solid growth ahead. Meanwhile, the recent pullback in its share price has eased some valuation concerns, making the stock more appealing.
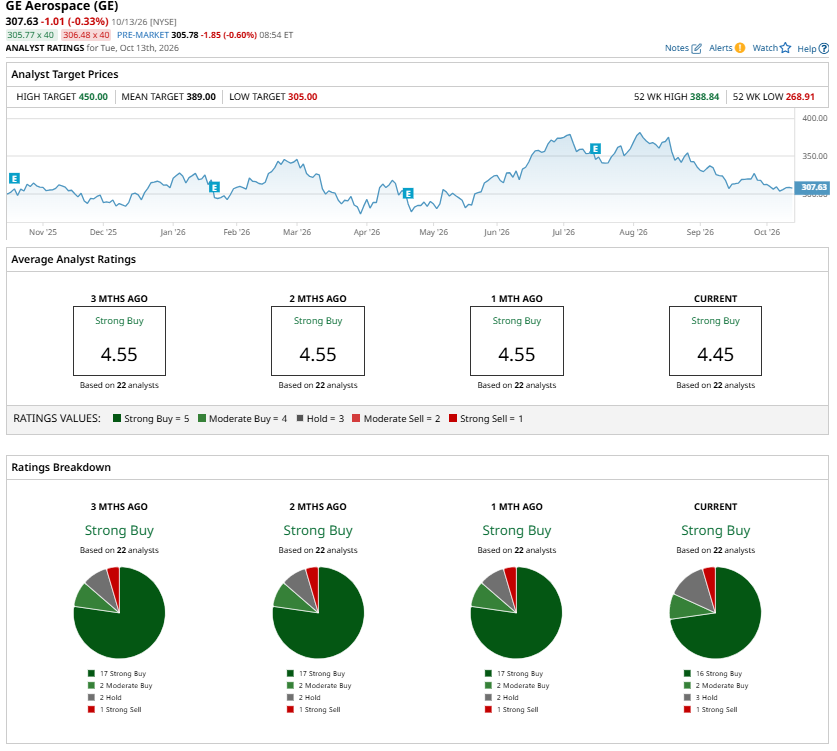
Analysts remain bullish on GE Aerospace ahead of its Q3 earnings report, maintaining a “Strong Buy” consensus rating.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.