
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Nanosonics Bears Saw Before The Fall
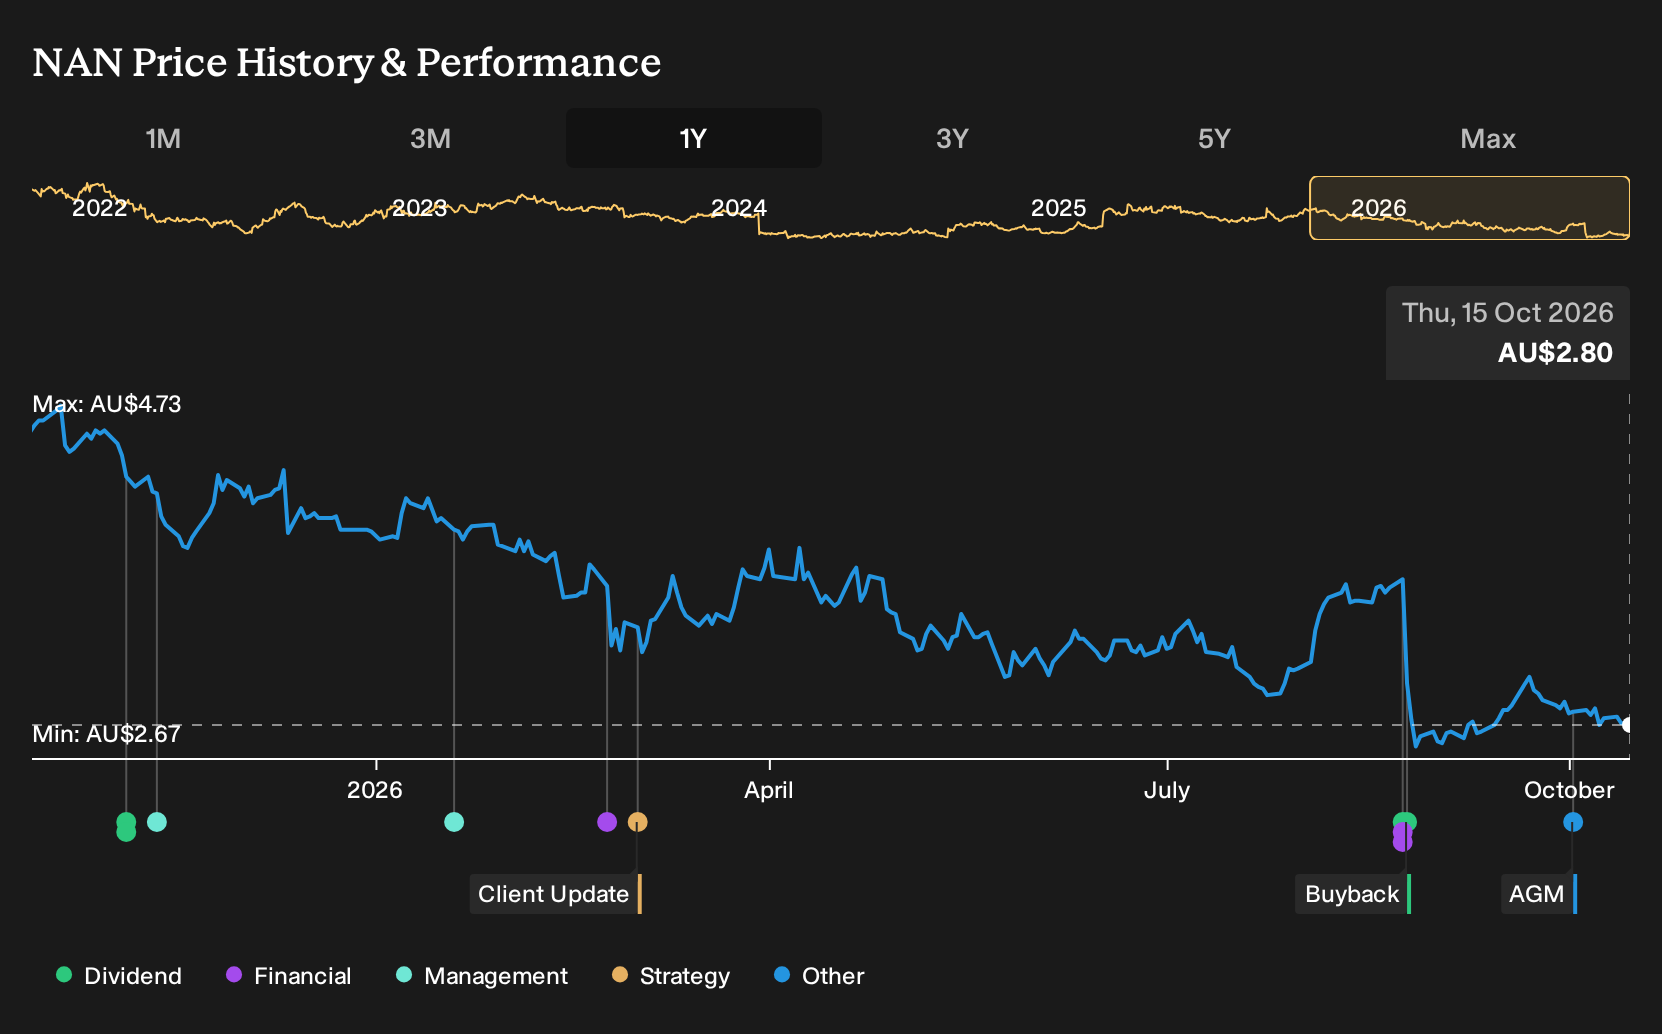
When Nanosonics reported its August 24, 2026 result, investors saw total revenue and net profit both lower than the prior half, and net margin sliding from 10.4% to 8.1%. That drop in profitability framed what shareholders had just lived through. Holding Nanosonics over the past year would have meant a 39.7% loss, including dividends. If you had been weighing a purchase back on 15 October 2025, how did the original growth story compare with this weaker margin outcome?
The easy part of this move is behind Nanosonics. Zero in on 4 high quality undervalued stocks for companies trading below our estimates.
The Two Nanosonics Stories Investors Were Arguing About
The shares cost A$4.61 at the start of the period, so any decision on Nanosonics hinged on which story about its future you found more convincing.
On the optimistic side, the bullish view saw a Fair Value of A$6, a price implied by strong assumptions. That camp leaned on expectations of 13.8% annual revenue growth and profit margins rising from 10.4% to 19.6%, helped by vertical integration in Indianapolis.
The cautious camp worked off a Fair Value of A$3.75 and worried about different issues. Bears focused on rising hospital cost containment and the risk that alternative disinfection technologies would leave trophon exposed and margins shrinking toward 7.6%.
What The Results Changed For Nanosonics
The clearest development was the reported H2 2026 result. Nanosonics posted A$101.662m in revenue and A$8.192m in net income, both below H2 2025, with net margin moving from 10.4% to 8.1%. That pattern challenged the optimistic case that leaned on faster growth and widening profitability, and it better matched the cautious scenario that flagged pressure on earnings quality.
The lesson is simple. When a story leans heavily on margin expansion, treat net margin as the key checkpoint and compare it across periods, not just the revenue and profit headlines.
What You Are Really Paying For In Nanosonics Today
Today Nanosonics trades at A$2.8, after a share price that fell 39.7% over the past year. The selected Narrative sees Fair Value above that level, built around recurring income from the existing trophon base and the planned expansion of CORIS.
The stress test is simple. A buyer now must judge whether CORIS achieves broad commercial adoption while trophon keeps producing enough cash to support disciplined, slower operating cost growth than revenue.
"Key Takeaways: Bullish analysts expect Nanosonics to convert its trophon installed base and the commercial launch of CORIS into higher recurring annuity revenue and EBIT over time, while keeping operating expenses growing more slowly than revenue. The main thing that has to go right is that CORIS moves from controlled market release to successful multi region commercial adoption, while the trophon franchise continues to support cash generation and share buybacks without adding debt."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 49% below our estimate - targets long dated audiovisual, electrical and cabling projects bundled with ongoing maintenance contracts.
- Company 2 - 31% below our estimate - supplies hard to source truck and bus components while handling diagnostics and parts interpretation for operators.
- Company 3 - 37% below our estimate - runs big box and online stores that cross sell electronics, appliances and installation services to households.
Three companies from the same screener. Open the full list of 12 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com