
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Merck KGaA Stock As AI Chip Survey Flags Capacity Strains
- EMD Electronics, the North American electronics business of Merck KGaA, recently published a survey showing strong AI linked semiconductor demand alongside capacity issues in advanced packaging, testing and talent.
- The survey points to supply chain resilience, rather than full reshoring, and highlights skilled workforce shortages as the primary constraint on planned investment.
- The next section examines how Merck KGaA's investment narrative could be affected by workforce shortages that are shaping AI driven semiconductor material demand.
Scan the chipmakers shaping AI infrastructure beyond Merck KGaA by reviewing our curated list of 92 AI infrastructure stocks.
Merck KGaA Investment Narrative Recap
To back Merck KGaA as a shareholder, you need to think the AI driven upswing in semiconductor materials, Life Science workflows and newer Healthcare therapies can collectively support earnings over time. The EMD Electronics survey aligns with that idea, since it points to solid AI related chip demand, but it does not change the short term story on its own.
The key near term swing factor still sits in execution. Semiconductor Solutions already showed 17% organic growth in Q2 2026 and tight customer capacity, so operational follow through there matters most. The biggest risk remains pressure in weaker activities and future Healthcare erosion around Mavenclad, especially if new rare disease and fertility drugs underperform expectations.
Within this context, the planned €11.5b acquisition of Bio Techne remains a central announcement for Merck KGaA. It is intended to bring higher consumables exposure and potential cost synergies, with analysts expecting it to lift Life Science margins and support EPS pre once integrated, if management hits its targets.
When viewed alongside the EMD Electronics survey, that deal looks even more important. AI related semiconductor demand can be cyclical, while a larger, workflow focused Life Science platform could help smooth group earnings if chip materials see periods of softer orders or currency effects. Your assessment comes down to confidence in integration, cost discipline and the balance between AI materials and Healthcare patent cliffs.
Merck KGaA Assumptions Behind the AI and Life Science Story
Analysts sketch out a fairly specific financial path for Merck KGaA that sits behind the AI, Life Science and Healthcare narrative. Consensus models point to revenue growth of 5.2% per year over the next three years, with profit margins moving from 11.2% today to 13.9% on their 2029 time frame. That combination underpins the view that the business can absorb swings in semiconductor materials demand while still funding pipeline drugs and workflow build outs.
Earnings forecasts pull this together in a single figure. The analyst group expects profit to reach €3.4b by around 2029 compared with €2.4b today, with a more optimistic camp looking for as much as €3.8b. In practice, that means investors weighing up roughly a €1.0b step up in earnings and asking whether Bio Techne integration, AI linked Electronics exposure and new Healthcare launches can collectively carry that weight without margin slippage.
Valuation work then applies a P/E lens. For the analyst price targets to hold, Merck KGaA would need to trade on a P/E of 22.5x those projected 2029 earnings, versus about 25.3x today and compared with 18.4x for the wider GB Pharmaceuticals group. That implies the market view already bakes in a premium for the mix of AI infrastructure leverage, Life Science consumables and higher risk rare disease assets, even as it assumes some multiple compression from current levels.
Merck KGaA's current analyst framework points to forecast revenue of €24.6b and earnings of €3.4b by 2029, built on 5.2% yearly revenue growth and an earnings increase of about €1.0b from €2.4b today.
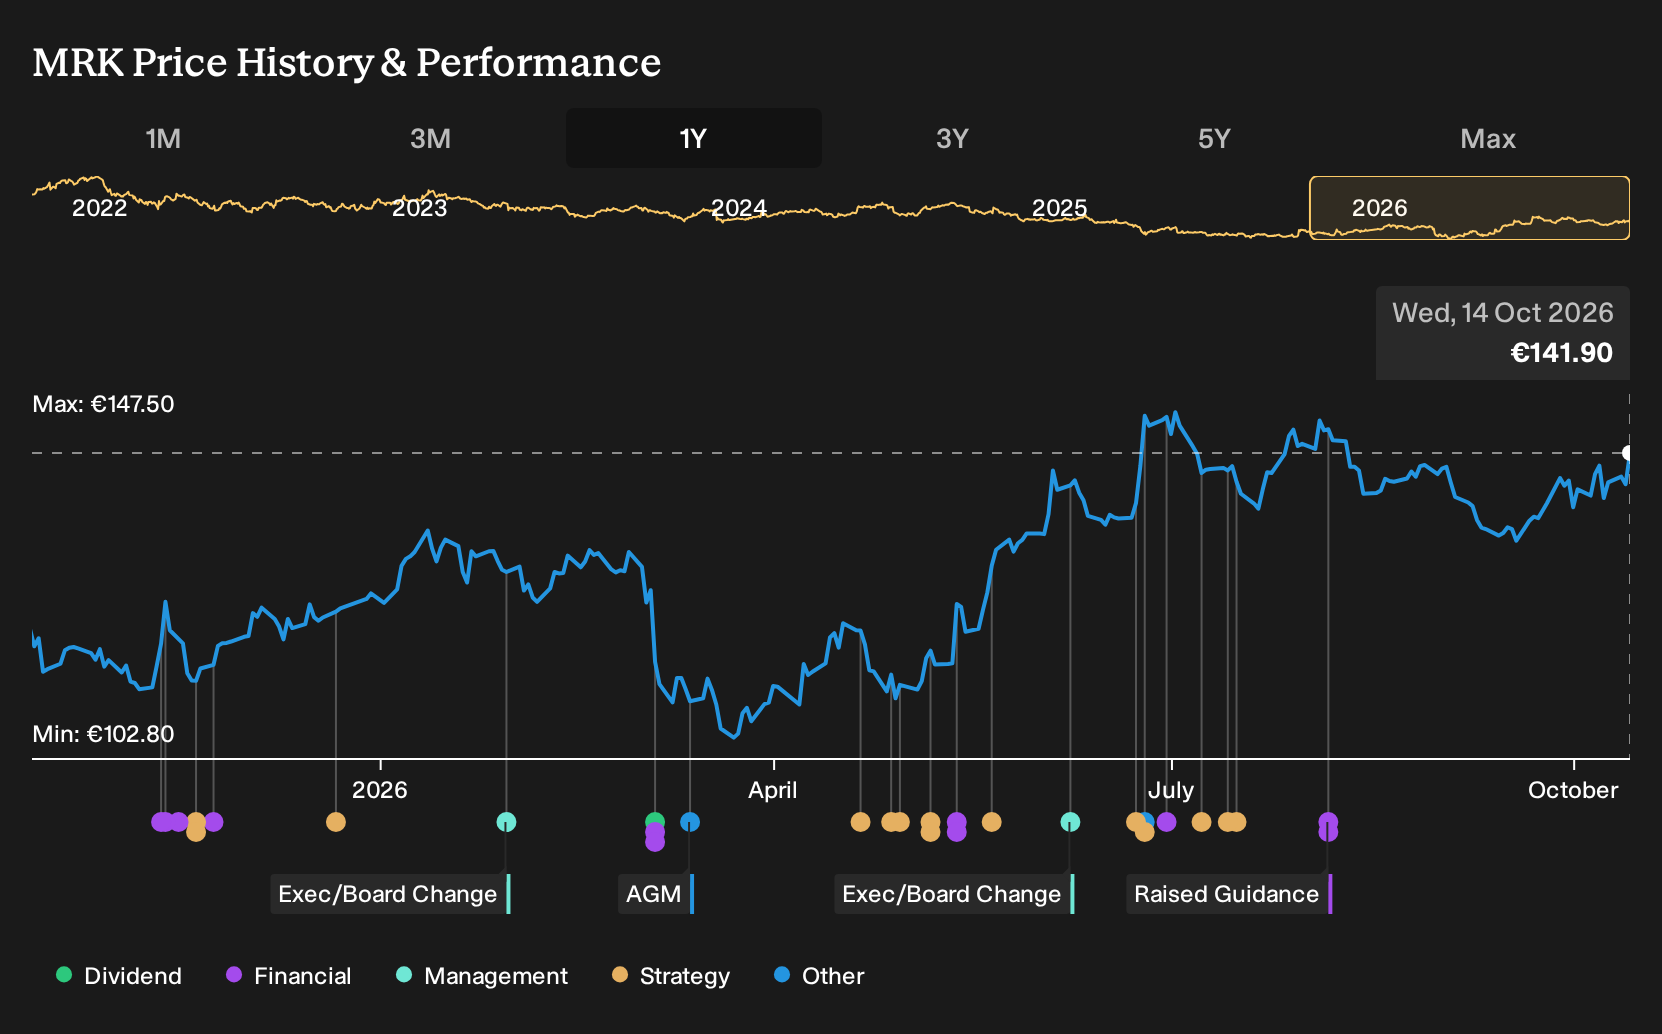
Uncover why Merck KGaA's fair value indicates a 9% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Workforce risk sits at the center of the most bearish story on Merck KGaA. You see that in the lower analyst group expecting revenue of about €23.9b and earnings of €3.1b by 2029, well under consensus. Those estimates were set before this EMD Electronics survey, so fresh data on talent bottlenecks could shift opinions in both directions.
Explore 3 other Merck KGaA fair value estimates, including one that suggests it could be worth just €135.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Merck KGaA research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Merck KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Merck KGaA's overall financial health at a glance.
Looking For More Ideas Beyond Merck KGaA?
Once you have formed a view on Merck KGaA, it can help to compare that thesis with opportunities across other sectors and regions. The Simply Wall St Screener gives you a filtered starting point so you are not scrolling through thousands of tickers with no structure.
- Focus on value first by scanning companies that combine quality fundamentals with potentially attractive pricing through our 196 high quality undervalued stocks.
- If stability matters more to you than headline growth stories, start with a 223 resilient stocks with low risk scores that emphasises resilient balance sheets and steadier risk profiles.
- Prefer businesses that are quietly compounding away from the crowd, with solid financials and limited coverage, by checking the 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com