
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
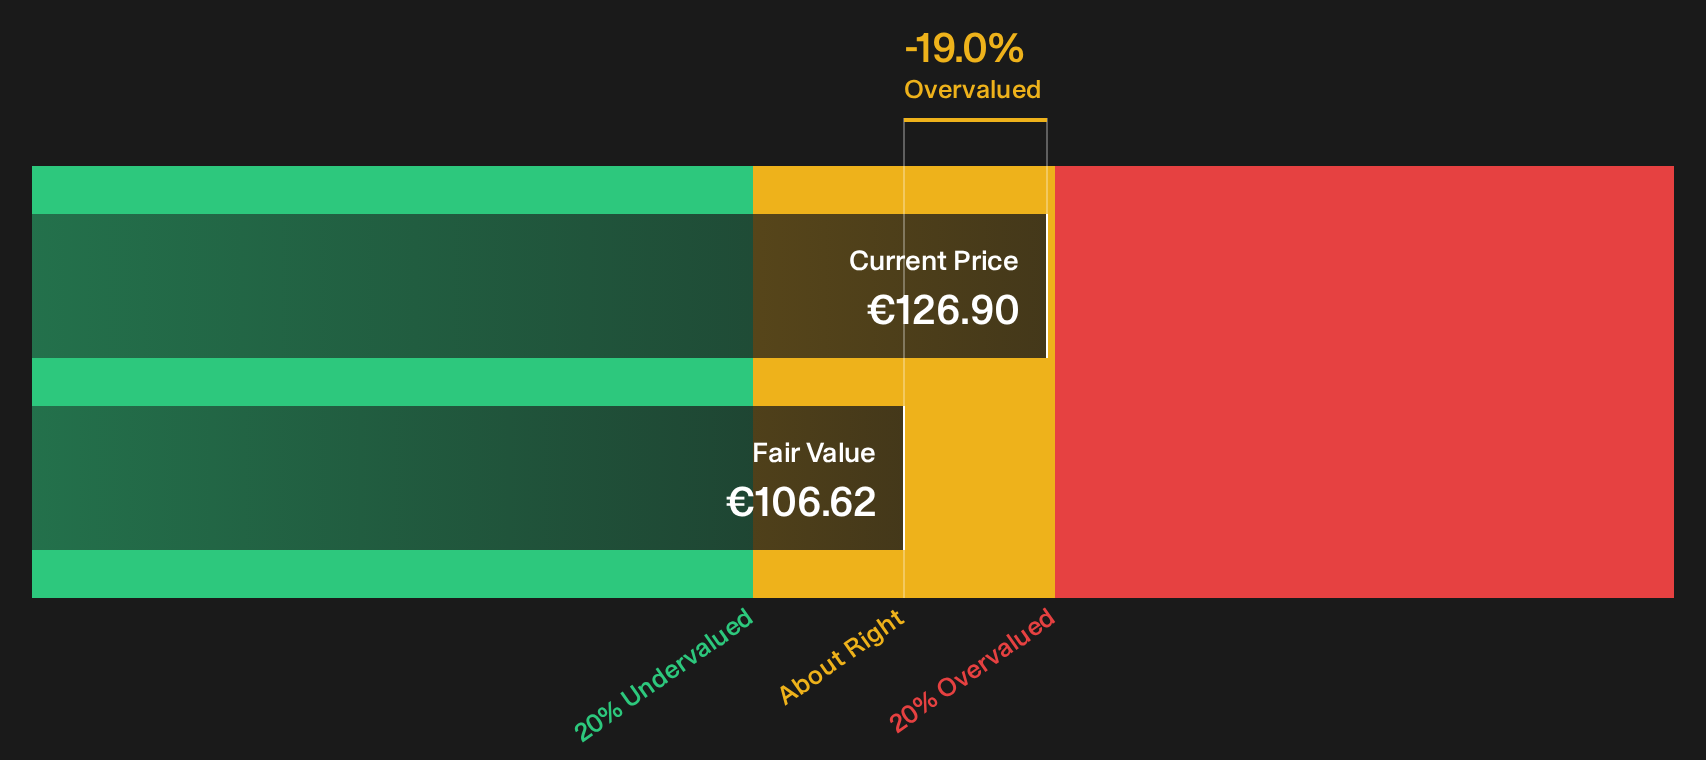
Reply (BIT:REY) Could Be 19% Overvalued On Symbiosis Launch
Reply (BIT:REY) has launched Symbiosis, an AI driven operating model that connects corporate strategy, portfolio choices and day to day execution. The focus is on measurable outcomes, continuous learning and tighter resource allocation.
Reply shares have been on a strong run recently, with a 30.82% 90 day share price return and an 8.28% 1 month share price gain. The 1 year total shareholder return of 8.22% points to steadier long term progress as Symbiosis and other initiatives land with investors.
Scan a curated set of AI focused opportunities alongside Reply by checking out the 150 AI small caps that are already building real products and operating models around generative AI.
After a 31% move in three months and annual revenue of €2,535.399m, Reply is priced for a lot of belief already. Does the current valuation still leave enough upside for new buyers?
Price-to-Earnings of 18x: Is it justified for Reply?
Reply now trades on a P/E of 18x at a last close of €126.90, which leaves the stock looking more expensive than its immediate peer group but not out of line with the wider European IT sector.
The P/E ratio compares the current share price with earnings per share, so it reflects how much investors are willing to pay for each euro of Reply's profit. For a software and digital services player, this matters because profit trends often carry more weight than one off revenue swings.
Reply's P/E of 18x sits almost exactly in line with the broader European IT industry at 18.2x. This suggests the market is valuing its earnings broadly in step with regional peers. At the same time, that multiple is well above the peer average of 12.6x flagged in the data, so investors are paying a clear premium versus a tighter peer set. Against an estimated fair P/E of 32.4x, the current rating is far lower, so the market could move a long way before it reached that modelled level.
Explore the SWS fair ratio for Reply.
Result: Price-to-earnings of 18x (ABOUT RIGHT)
Still, a richer P/E leaves Reply vulnerable if AI projects underdeliver or if revenue growth of 7.4% falls short of investor expectations.
Find out about the key risks to this Reply narrative.
Another View On Reply's Valuation
The P/E story for Reply looks balanced, yet the SWS DCF model points in a different direction. On that cash flow view, the share price of €126.90 sits above an estimated value of €106.62, which frames the stock as overvalued on this method. Which signal do you trust more?
Our DCF output is one input, not a verdict. It depends heavily on growth, margins and discount rate assumptions that may or may not play out as forecast, so treat it as a cross check rather than a final answer. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Reply for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Reply's AI push and valuation is mixed, so it helps to move fast and review the underlying data yourself before opinions settle. To see what optimistic investors already like about the business, check the 4 key rewards
Looking for more investment ideas beyond Reply?
Reply may already be on your radar, but the strongest portfolios rarely rely on a single story. Spread your bets and keep fresh opportunities in view.
- Target potential mispricings by scanning the 196 high quality undervalued stocks that combine solid fundamentals with prices the market has not fully reflected yet.
- Build a steadier income stream by focusing on 217 dividend fortresses that aim to pair higher yields with more resilient payout histories.
- Strengthen your downside protection by reviewing the 223 resilient stocks with low risk scores designed to highlight businesses with more resilient balance sheets and risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com