
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Sales Growth Altering The Investment Case For Kesko Oyj (HLSE:KESKOB)?
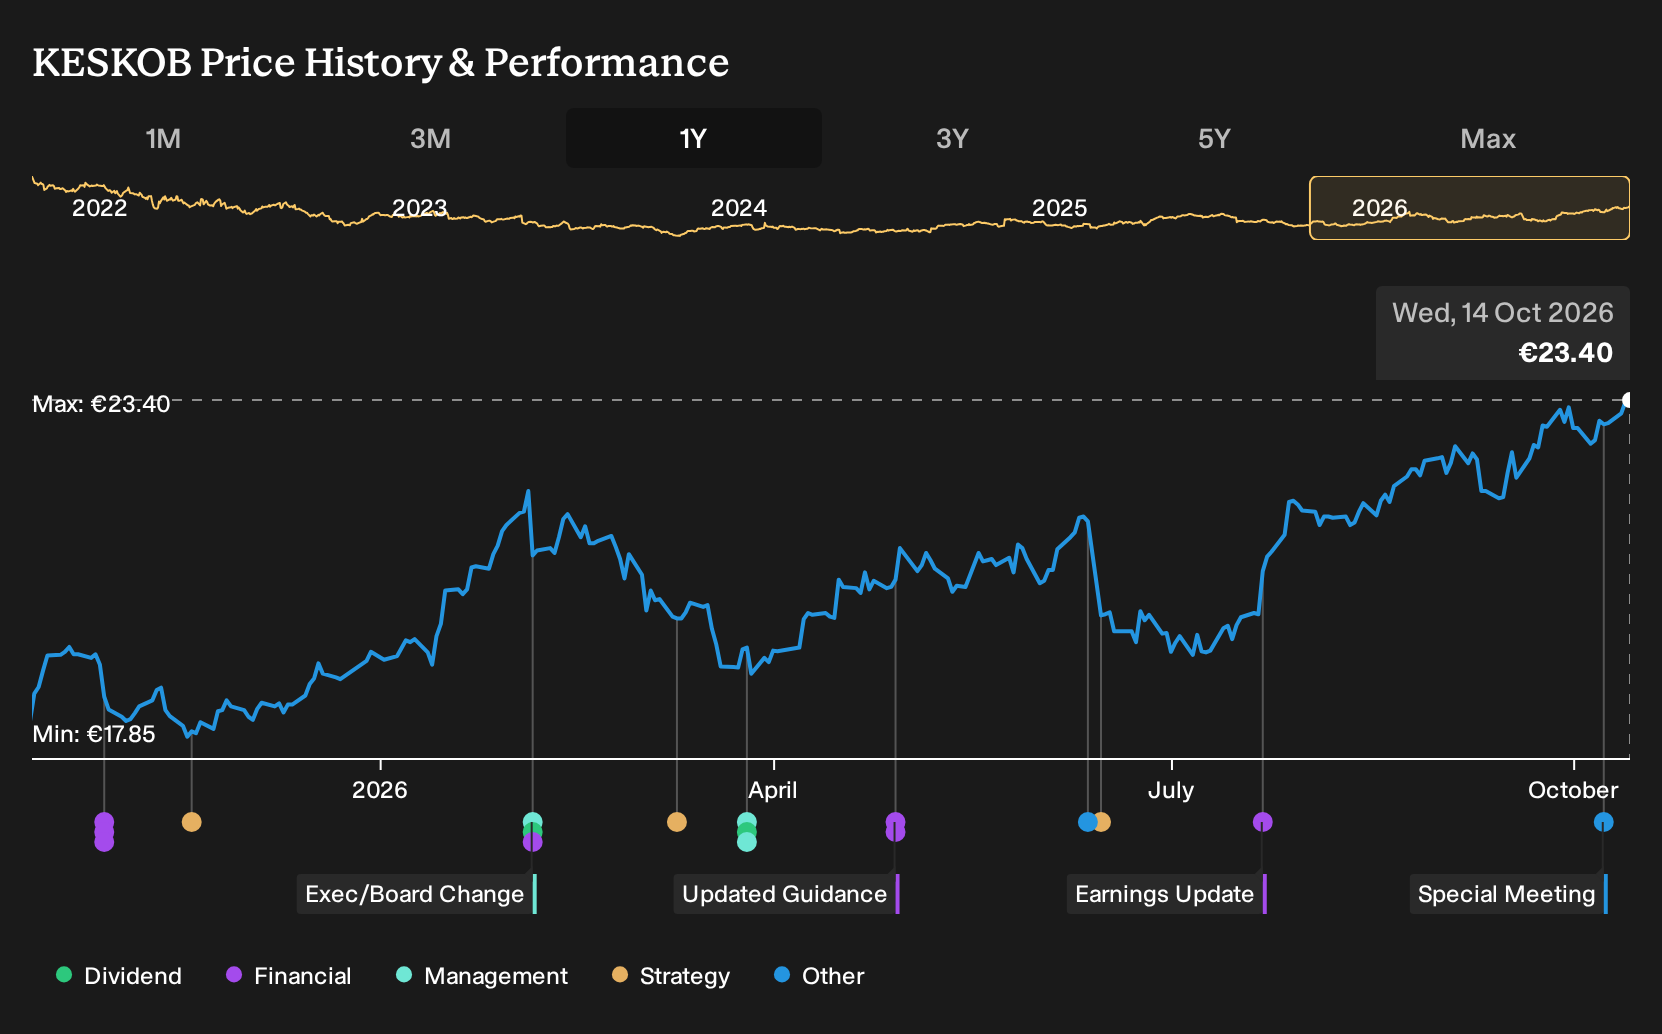
- Kesko Oyj reported Group sales of €1,198.4 million for September 2026, a 4.8% year-on-year rise, with year-to-date sales reaching €3,477.8 million.
- The combination of stronger September trading and higher cumulative sales indicates that Kesko Oyj is currently converting underlying demand into tangible top-line gains.
- This article will now examine how Kesko Oyj's 4.8% September sales increase could influence the existing investment narrative and longer-term expectations.
Scan how Kesko Oyj's sales momentum compares with other retailers by reviewing the hand picked list of solid balance sheet and fundamentals (202 results).
Kesko Oyj Investment Narrative Recap
To hold Kesko Oyj, you generally need to believe in a steady, multi segment retailer that can turn dense Nordic urban markets, quality focused food offerings and a broad building and technical footprint into consistent earnings. The September sales print points to demand that is currently holding up and supports that bigger picture, but does not reshape it.
The short term swing factor still looks tied to how quickly construction related volumes and pricing stabilise in Building and Technical Trade, given its scale alongside Grocery Trade. The biggest near term risk remains heavy grocery and technical price competition in Finland and the wider region, which could pressure margins if promotions keep intensifying.
The September 2026 sales release is the cleanest operational datapoint right now. Group sales of €1,198.4 million for the month and €3,477.8 million year to date indicate that the retail engine is active across grocery, building supplies and autos, which matters for a diversified retailer like Kesko Oyj that depends on using scale to support profitability.
For catalysts, this update fits directly into the existing thesis around volume recovery and operating leverage in European construction and technical trade. If sales in that division hold up alongside grocery traffic in urban hypermarkets, it helps execution on automation and logistics efficiency projects that Kesko has been rolling out, while still leaving competitive intensity and debt levels as key watchpoints for you.
Kesko Oyj's current analyst narrative points to revenues of €14.3b and earnings of €575.1 million by 2029, anchored on forecast revenue growth of 3.6% per year and an earnings increase of about 38% from €418.2 million today.
Uncover how Kesko Oyj's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span a tight band between €22.30 and about €47.69, so some private investors see Kesko Oyj as close to half or double what others think it is worth. Those opinions were formed before the September sales update. You may want to weigh them against the risks around construction exposure, grocery CapEx payback and price competition, which could all influence how the business converts revenue into sustainable earnings over time.
Explore 2 other Kesko Oyj fair value estimates, including an estimate that suggests it could be worth just €22.30.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kesko Oyj research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kesko Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kesko Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kesko Oyj?
If this Kesko Oyj update has sharpened your view on quality retailers, it can be useful to compare it with a broader watchlist of potential opportunities using the Simply Wall St Screener.
- Focus on quality at a discount by scanning companies that combine solid fundamentals with appealing valuations through the 196 high quality undervalued stocks.
- If capital preservation sits high on your checklist, narrow in on sturdier balance sheets and steadier businesses via the 223 resilient stocks with low risk scores.
- When you want to cast the net wider for promising but less followed opportunities, widen your search with the 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com