
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Strength Might Change The Case For Investing In Moog (MOG.A)
- Moog has reported strong earnings, supported by solid revenue growth, rising free cash flow margin, and an active share repurchase program that has lifted earnings per share.
- The company’s precision motion control portfolio, including systems for platforms like the B-2 stealth bomber, underpins this performance while investors weigh a premium valuation against Moog’s operational execution.
- We will now look at how Moog's earnings strength, particularly the impact of share repurchases, might reshape its broader investment narrative.
Scan beyond Moog and see how other aerospace and defense players stack up in our hand-picked list of 32 resilient stocks with low risk scores.
Moog Investment Narrative Recap
For a Moog shareholder, the core belief is that its motion control portfolio across defense, commercial aircraft, and industrial markets can keep converting a strong backlog into resilient earnings and cash generation. The latest results, with solid revenue and higher free cash flow margin, support that operating story and give management more room to keep investing while returning capital.
In the near term, the key swing factor is execution on efficiency programs and free cash flow conversion as working capital needs evolve. Tariff pressures on steel, aluminum, and imported components remain the biggest operational risk. The recent earnings strength helps offset that headwind, but it does not remove the challenge.
With no new major announcements beyond the earnings update, the most relevant development is still Moog’s improving free cash flow margin combined with its active share repurchase activity. Higher cash generation, if sustained, gives the business more flexibility to fund defense and data center pump opportunities without relying as heavily on additional borrowing.
For catalysts, this matters because tariff headwinds and the next phase of cost improvement are expected to be tougher, and cash can cushion that. Share repurchases also interact directly with the premium P/E, since fewer shares concentrate any future earnings on a smaller base. That magnifies both execution upside and any stumble in margins or program performance.
Moog's narrative projects US$5.3b revenue and US$428.3m earnings by 2029. Analysts are assuming 7.1% yearly revenue growth, and this outlook implies an earnings increase of about US$51.2m from the current US$377.1m.
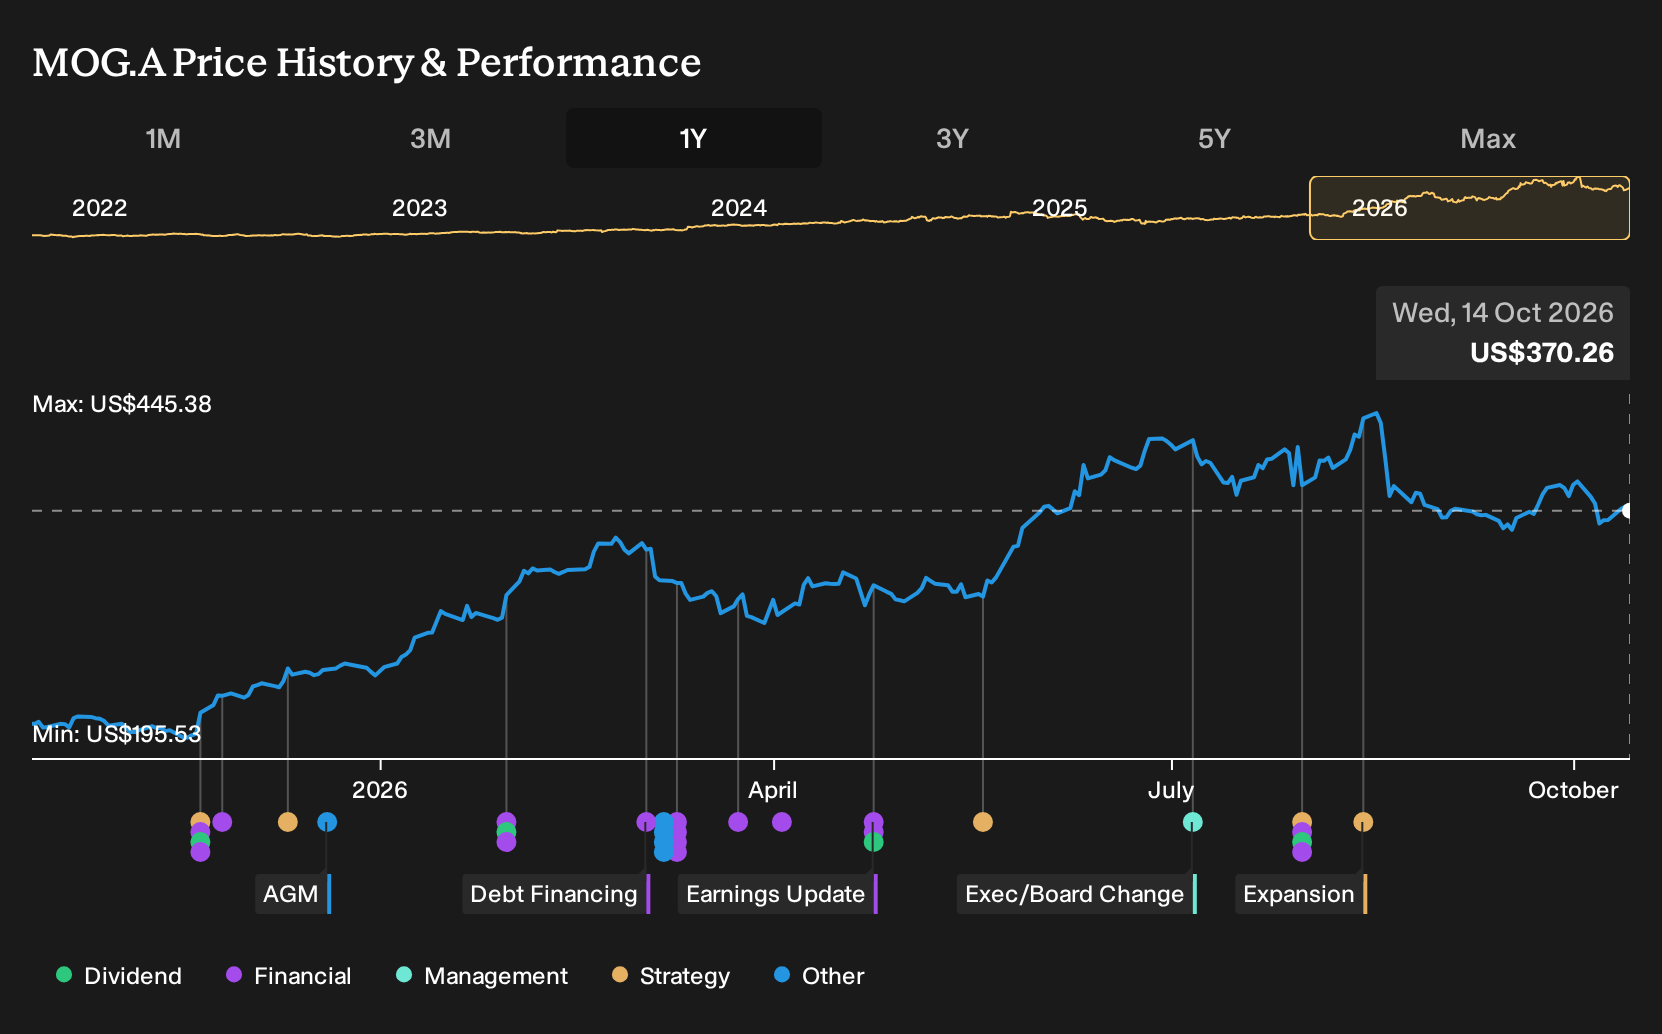
Uncover why Moog's fair value indicates a 21% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the lowest Moog forecasts lean hard into execution risk on missile and space capacity expansion. Those analysts were modeling earnings of about US$397.4m on US$5.3b revenue by 2029, with margins slipping faster than consensus. That more cautious story could shift meaningfully once the latest earnings news gets fully absorbed.
Explore 3 other Moog fair value estimates, including one that suggests as much as 51% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Moog research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Moog. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Moog's overall financial health at a glance.
Looking For More Investment Ideas Beyond Moog?
If Moog's story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you quickly filter the market into focused shortlists that match your own risk and income preferences.
- For investors who care most about resilience, start with a curated group of companies that have historically scored well on balance sheet strength and fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results).
- If value is your priority, narrow the field to stocks that combine quality metrics with what our models flag as pricing that may be attractive through the 32 high quality undervalued stocks.
- Those seeking income can focus on businesses that offer higher yields alongside an emphasis on stability by scanning the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com