
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Earnings Beat Will Impact CoreCivic Stock Investors
- CoreCivic reported an exceptional Q2, with revenue and EPS above analyst estimates and the fastest growth rate among its peers.
- The results highlight how rising demand for physical and cybersecurity focused safety solutions is flowing into CoreCivic’s core detention and services platform.
- We will now see how CoreCivic’s investment narrative is shaped by this exceptionally strong Q2 earnings performance.
Scan how CoreCivic’s Q2 momentum compares with peers in the safety and security space by zeroing in on our hand-picked 32 resilient stocks with low risk scores that pair resilience with disciplined risk profiles.
CoreCivic Investment Narrative Recap
To own CoreCivic, you need to believe the detention and corrections outsourcing model will keep drawing steady federal demand, especially from ICE, and that the firm can keep facilities productively utilized. The strong Q2 results support that view in the near term by showing the platform can convert rising safety and security needs into higher activity.
The key short term swing factor is contract volume and pricing with federal partners, particularly around immigration detention. The biggest risk remains policy and budget volatility that could cut detention counts or reprice contracts. Recent insider selling and a board still bedding in add an extra execution and sentiment overhang.
Recent facility sales to the government, worth about US$2.2b, with CoreCivic retaining management contracts, are central to this Q2 story. They free up capital while keeping operating income streams tied to those prisons. That helps explain how the group can report strong earnings while still discussing debt reduction and balance sheet flexibility.
For investors, those transactions tie directly into the same catalysts highlighted in Q2. There is a large owned real estate base of 56 specialized properties, long duration federal contracts, and a capital pool that can be directed toward debt paydown or buybacks. The potential operational benefits must be weighed against policy risk and the need to keep occupancy and cash generation sufficient to cover leverage.
CoreCivic's narrative anticipates US$3.4b in revenue and US$516.8m in earnings by 2029, based on the projections provided. According to these figures, this would correspond to 11.6% yearly revenue growth and approximately a fourfold increase in earnings compared to the current US$127.9m.
Uncover why CoreCivic's fair value suggests a 28% potential upside to its current price that could close more quickly than the market expects.
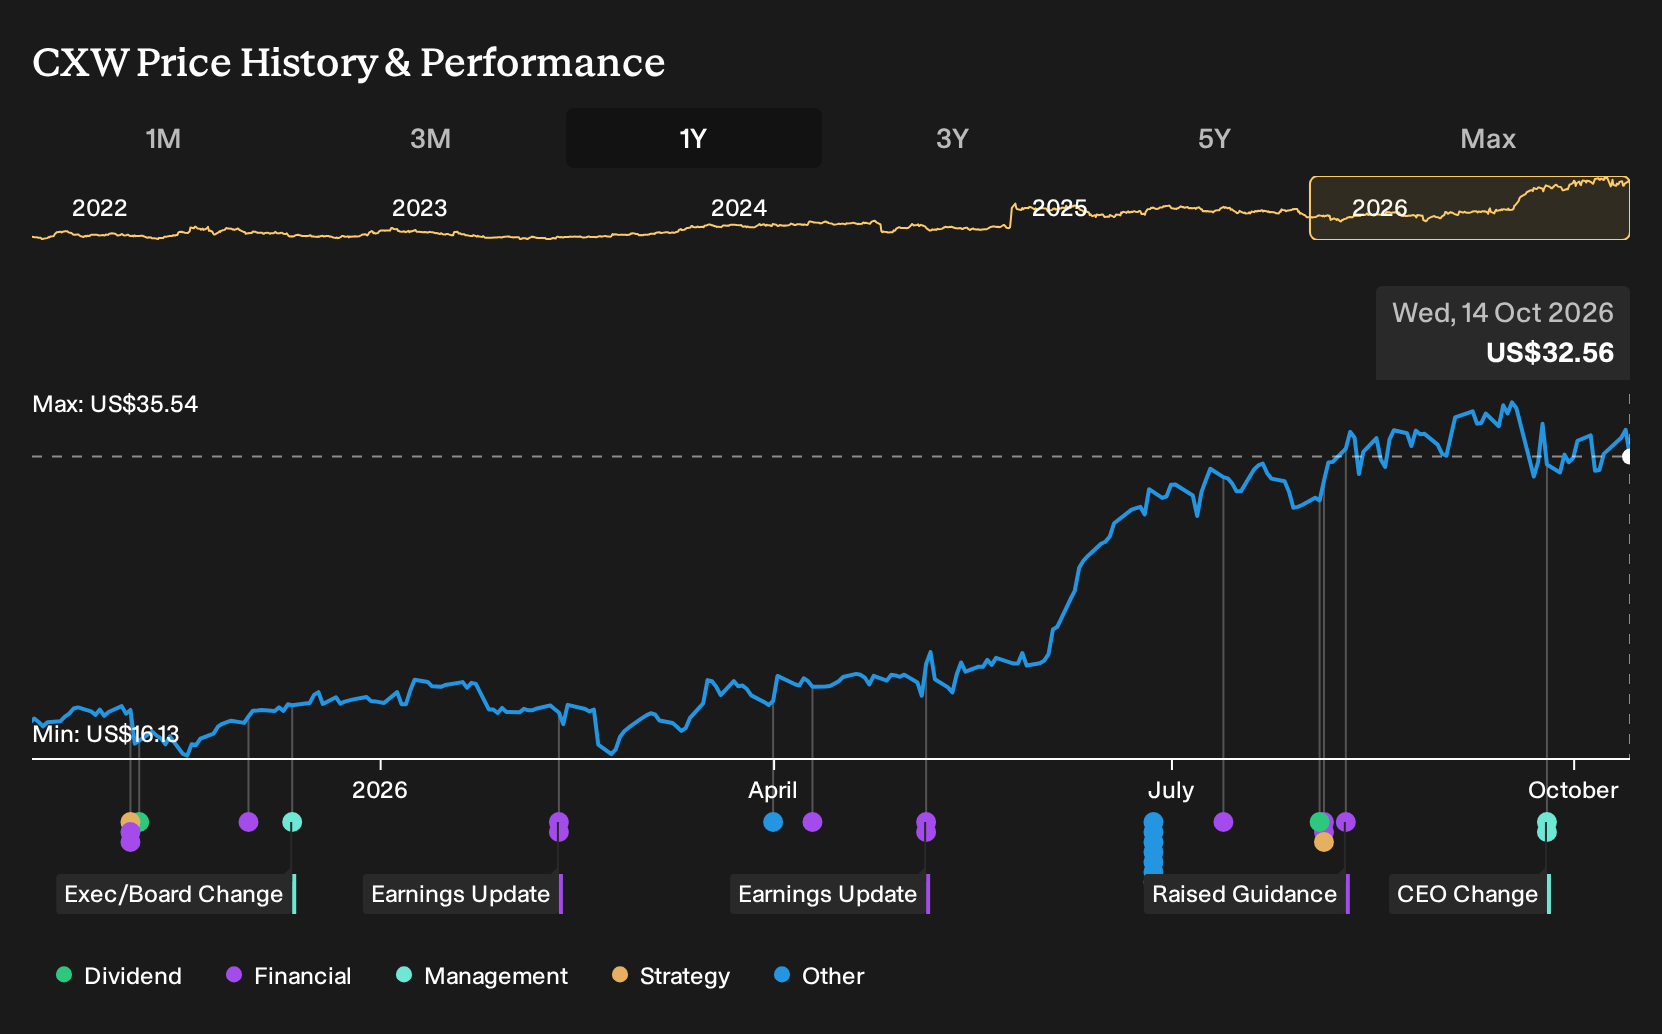
Exploring Other Perspectives
Some of the most optimistic analysts on CoreCivic focus on idle capacity turning into fresh ICE and state contracts, with revenue growing 13.3% a year and earnings reaching US$162.1m by 2029. That is more upbeat than consensus. Q2’s strong surprise could push these views closer together or further apart, so consider both possibilities.
Explore 2 other CoreCivic fair value estimates, including one that suggests as much as 28% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CoreCivic research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CoreCivic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CoreCivic's overall financial health at a glance.
Looking for more CoreCivic-sized investment ideas?
If CoreCivic has sharpened your thesis on risk, cash flow and contracts, it can be useful to widen the lens and see how other companies stack up on income potential, quality, and resilience using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting in your portfolio, scan a curated set of higher-yield opportunities through our 7 dividend fortresses.
- For readers who care most about financial strength and staying power, filter for companies with cleaner balance sheets using the list of solid balance sheet and fundamentals (25 results).
- If you prefer to hunt for underfollowed opportunities backed by solid fundamentals, start with this focused 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com