
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
EVERTEC (EVDA) Following Its Expansion Story Still Looks Undervalued
EVERTEC (EVTC) drew fresh attention after its recent share move, with the price closing at US$30.89 on 14 October 2026. That shift has investors rechecking the payment processor's fundamentals and valuation.
Recent momentum has tilted positive for EVERTEC, with a 1 week share price return of 6.66% and a 30 day gain of 5.32%. However, the 5 year total shareholder return of a 33.31% decline shows that longer term holders have faced a much tougher journey.
Scan other payment and fintech processors showing similar price action to EVERTEC with the hand picked 32 high quality undervalued stocks that balance quality fundamentals against recent valuation pressure.
EVERTEC’s recent uptick could be read as a nod to improving fundamentals, or just a burst of optimism chasing the chart. To sort those stories, the valuation needs a closer look next.
Most Popular Narrative: 13% Undervalued
EVERTEC’s most followed valuation story pegs fair value at $35.60, which sits above the latest $30.89 close and presents the recent move as only part of the gap that narrative sees.
Ongoing Latin America expansion through acquisitions such as Sinqia, Dimensa, Tecnobank and BBChain, combined with large processing contracts including Transbank in Chile and Clip in Mexico, is expected to shift more of EVERTEC’s revenue mix toward higher growth markets and support earnings over the next several years.
See why 2 investors see EVERTEC as 13% undervalued.
Result: Fair Value of $35.60 (UNDERVALUED)
Still, a few fault lines could crack that EVERTEC story, especially if the recent cybersecurity incident leads to higher ongoing costs or if Business Solutions revenue weakness persists and drags on earnings.
Find out about the key risks to this EVERTEC narrative.
Another View: EVERTEC Through Earnings Multiples
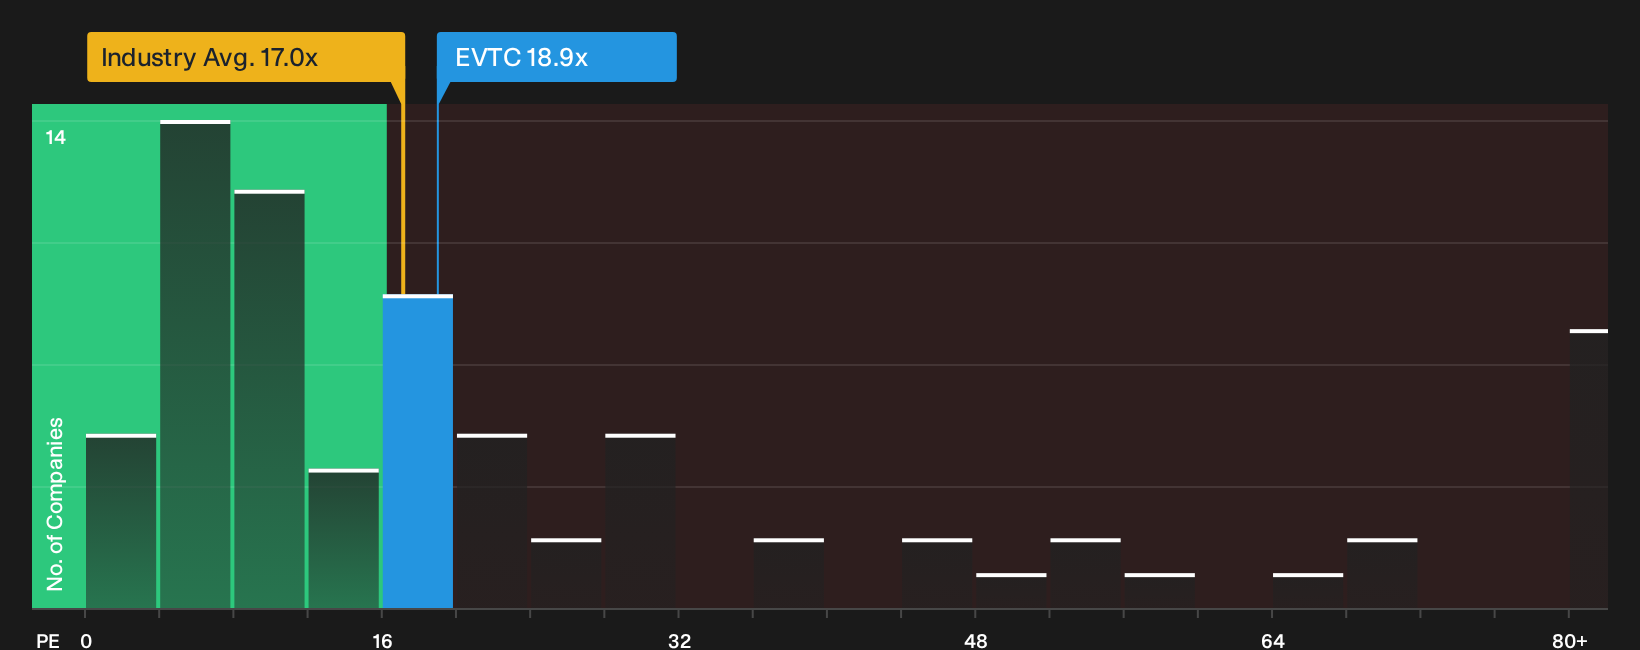
There is a very different read on EVERTEC when you stop looking at fair value estimates and simply compare today’s price to current earnings. The stock trades on a P/E of 18.9x, which sits above both the US Diversified Financial industry at 17.1x and the fair ratio of 15.4x that the regression work points to.
That gap suggests investors are already paying a premium to peers and to the fair ratio the market could move toward. This raises the chance that disappointment on execution or forecasts would affect the share price faster than a pure discount story implies. Which version of the EVTC story do you trust most when real money is on the line?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of the EVERTEC story so far. Move quickly, review the data, and weigh both sides using the 2 key rewards and 3 important warning signs
Looking for more EVERTEC style investment ideas?
If the EVERTEC debate has you thinking about portfolio upgrades, use the Simply Wall Street Screener to spot fresh ideas before they slip past your watchlist.
- Hunt for potential mispriced opportunities by scanning the broader market through the 32 high quality undervalued stocks. This screener filters for quality alongside compressed valuations.
- Strengthen your income stream by reviewing the 7 dividend fortresses, which highlights companies combining sizeable yields with supporting fundamentals.
- Dial down portfolio stress by focusing on resilience with the 32 resilient stocks with low risk scores. This tool surfaces businesses carrying lower aggregate risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com