
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Thermo Fisher Scientific (TMO) Expands Drug Development Services, Is The Stock Fully Valued?
Thermo Fisher Scientific (TMO) is back in focus after Quantum BioPharma selected its clinical research arm to run a Phase 2 multiple sclerosis trial, highlighting growing reliance on the company’s end to end drug development services.
Thermo Fisher Scientific’s recent contract wins and product launches come against a backdrop of firm share price momentum, with a 30 day share price return of 9.71% and a 90 day share price return of 23.93%. Total shareholder return over the past year sits at 27.98%, while the 3 year total shareholder return is 45.48%, suggesting investors have been rewarding the business as its role in drug development and clinical services expands.
Spot other drug development and biotech service stocks with similar momentum by scanning the 20 high quality undiscovered gems that are quietly building strong positions across clinical trials, tools, and bioprocessing.Thermo Fisher Scientific’s near term surge sits at the crossroads of solid contract flow and product rollouts on one side, and a warmer mood around AI linked life sciences tools on the other. How does that backdrop square with today’s valuation?
Most Popular Narrative: 3% Overvalued
Thermo Fisher Scientific closed at $673.20, modestly above the most followed fair value estimate of $652.85. The current optimism in the share price therefore leans slightly ahead of that narrative, which is built using an 8.44% discount rate and analyst earnings assumptions.
Thermo Fisher Scientific is viewed as fairly valued and the current share price implies that the market already prices in continued mid-single-digit organic growth, ongoing margin expansion, and incremental contributions from recent acquisitions and capital returns.
See why 95 investors see Thermo Fisher Scientific as 3% overvalued.
Result: Fair Value of $652.85 (OVERVALUED)
Still, this fair value story can fray if pharma and biotech funding cools again, or if the microbiology divestment drags on margins longer than expected.
Find out about the key risks to this Thermo Fisher Scientific narrative.
Another View: Thermo Fisher Scientific Through The P/E Lens
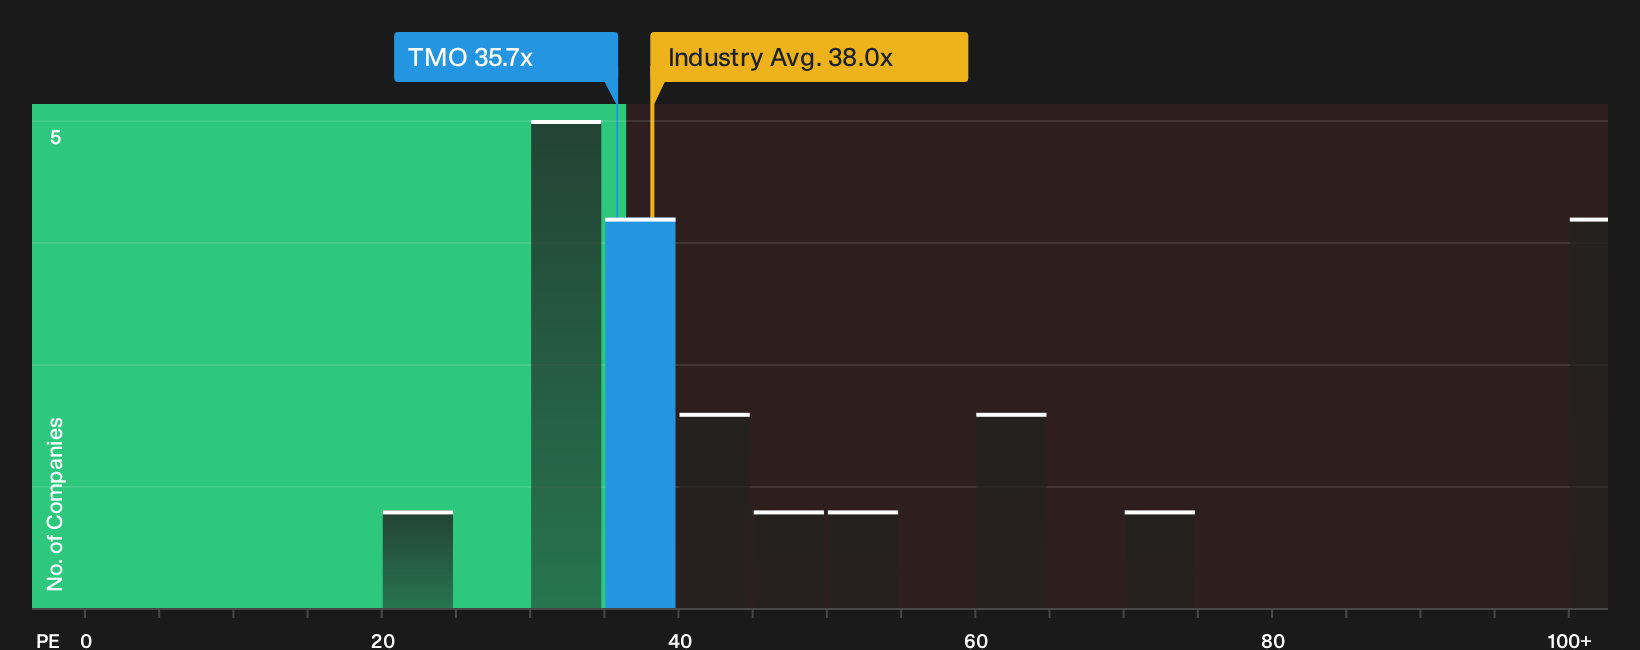
Thermo Fisher Scientific screens as slightly expensive on one key check. The stock trades on a P/E of 35.7x versus a fair ratio estimate of 33.5x, even though the Life Sciences industry and peer averages are higher at 41.6x and 38.7x. That gap points to some valuation risk if sentiment cools before earnings catch up.
For a closer look at how this earnings multiple compares with sector norms and how the fair ratio might influence pricing over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions are mixed on whether Thermo Fisher Scientific’s current setup appears balanced or stretched. Act quickly on your curiosity, review the full picture for yourself, and consider both the potential upside factors and the concerns through the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Thermo Fisher Scientific?
If Thermo Fisher Scientific has your attention, do not stop here. Broaden your opportunity set and pressure test your thesis by scanning other ideas that match your risk and return preferences.
- Target fresh upside potential by reviewing a curated 20 high quality undiscovered gems that many investors have not yet placed on their radar.
- Prioritize resilience in tougher markets by focusing on a 32 resilient stocks with low risk scores that aims to keep drawdowns in check while still leaving room for returns.
- Anchor your watchlist around financial strength by filtering for a list of solid balance sheet and fundamentals (25 results) that can better handle funding pressures and business setbacks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com