
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Alcoa (AA) Stock May Be Below Fair Value On Earnings
Alcoa has seen a sharp mix of gains and setbacks over recent years, which puts fresh focus on whether the current US$40.08 share price lines up with the earnings power of the business. With the stock pulling back in the short term but showing a strong multi year result, the question now is how much of that journey is actually supported by profits.
- Over the past 3 years the stock has returned 56.3%, which puts real weight on the question of whether earnings can carry that kind of performance.
- The company’s value case rests heavily on how efficiently it can turn its aluminum operations into consistent earnings, which can affect how sustainable today’s P/E ratio looks against the Fair Ratio benchmark.
- Your read on Alcoa is one view; the desks covering it have another. See what analysts think Alcoa's shares could be worth.
The stock’s next move may depend on whether Alcoa’s current price is properly anchored to its earnings profile.
If you want to pressure test Alcoa’s earnings story against a wider field, compare it with companies in the 32 high quality undervalued stocks
Is Alcoa a Bargain on Earnings?
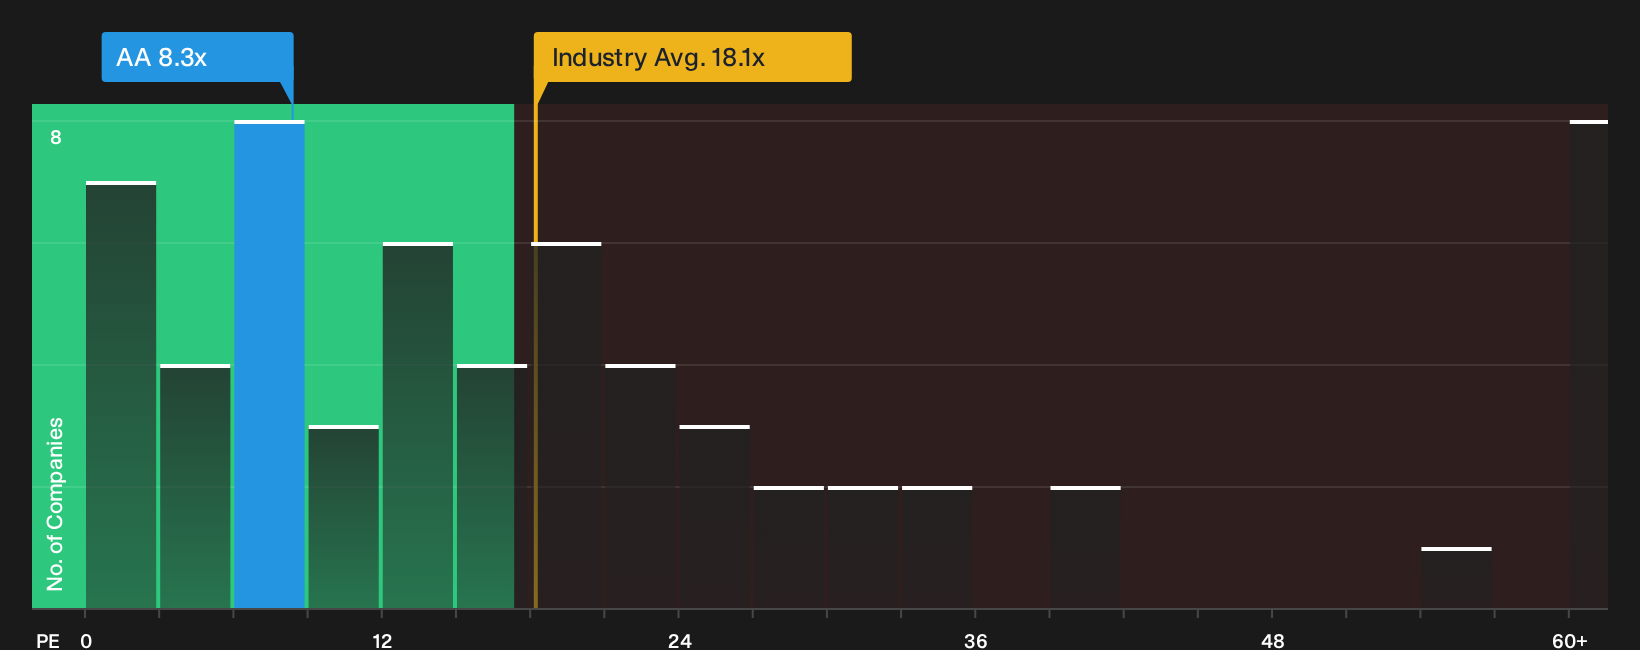
The P/E ratio suits Alcoa because earnings still sit at the center of how investors frame a cyclical producer like this. On that measure, the stock trades on about 8.3x earnings, which is lower than both the Metals and Mining industry average near 18.1x and the peer group sitting around 7.6x. So the share price tags Alcoa at a discount to the wider sector while being only slightly richer than closer rivals in the same peer set.
A Fair Ratio model that folds in Alcoa’s own mix of growth forecasts, profitability profile, size and risk implies the business could support a higher P/E than where the shares currently change hands. That leaves the present 8.3x multiple screening as undervalued relative to this tailored benchmark, although investors still need to weigh how cyclical earnings, capital intensity and commodity exposure affect what feels comfortable to pay. Explore the numbers behind Alcoa's P/E valuation.
The Alcoa Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off by spelling out what would need to happen to Alcoa's future growth, profitability and earnings profile for the stock to look meaningfully cheaper or more expensive than it does today on Simply Wall St's Community page. Each one links a valuation view to a specific path for Alcoa's revenue trends, margin resilience and risk profile that you can revisit as new information arrives.
One of the top community narratives on Alcoa: 34% undervalued
"Decarbonization trends, supply constraints, and sustainable product innovation position Alcoa for stronger pricing, improved margins, and resilient long-term growth..."
Discover why this Narrative puts Alcoa at 34% undervalued.
One more angle on Alcoa that investors often overlook
Everything so far has focused on what Alcoa looks like today, yet there is an entire layer of expectations built into where professionals think this business could be a few years from now. Explore where analysts expect Alcoa to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com