
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Weak Marmaxx Sales Just Shift TJX Stock's Investment Narrative?
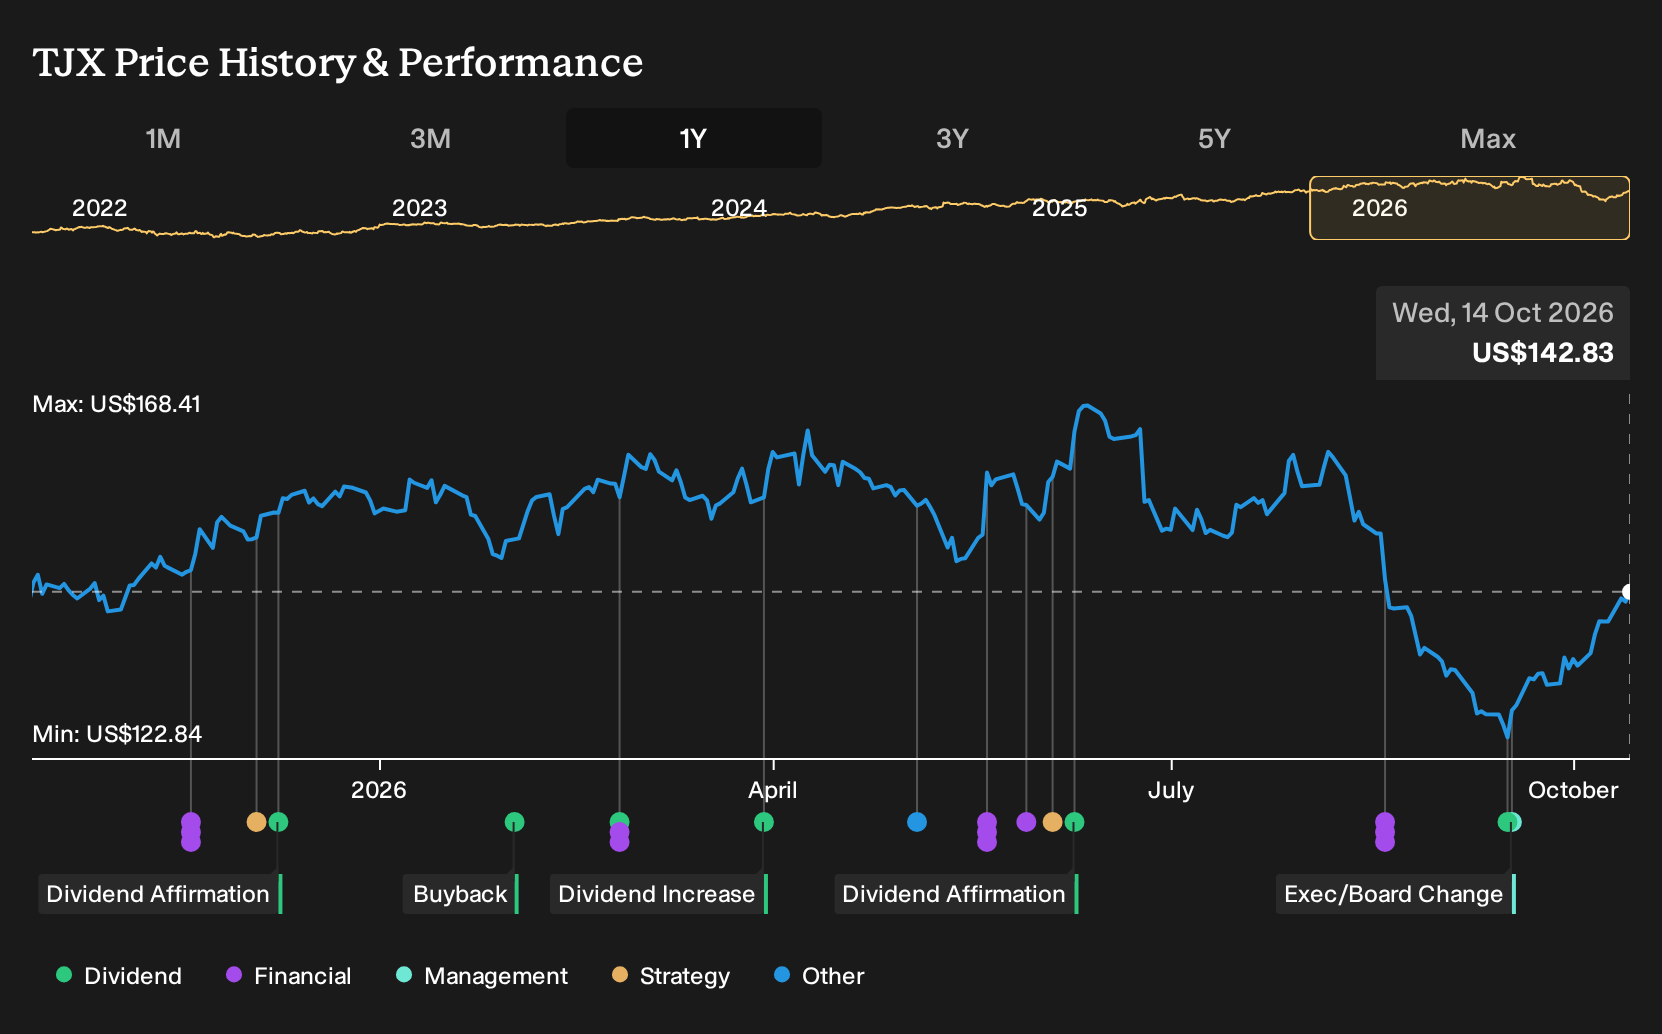
- TJX Companies reported that its key Marmaxx division posted same store sales below both internal and consensus expectations, with management pointing to merchandising and category mix execution challenges rather than structural demand or competitive pressure.
- At the same time, TJX Companies is pressing ahead with a plan to add at least 1,300 stores worldwide, signaling that management is committing capital to a larger off price footprint even as it works through near term issues at Marmaxx.
- The next step is to evaluate how TJX Companies' investment narrative is affected by weaker Marmaxx comparable sales alongside an aggressive long term store expansion plan.
Scan beyond TJX Companies and compare how other off price and value focused retailers are positioned today using our hand picked 32 resilient stocks with low risk scores as a starting universe.
TJX Companies Investment Narrative Recap
TJX Companies still asks you to believe in the long term appeal of off price shopping, supported by its scale, sourcing reach and disciplined merchandising. The weak Marmaxx comparable sales put a spotlight on execution, not on the concept of off price itself. The main short term catalyst is whether management can quickly fix product and category mix to stabilize traffic.
The biggest risk right now sits in a repeat of those mix issues at Marmaxx, while fuel and freight costs pressure margins. If the merchandising reset lands cleanly, the store base and distribution model give TJX Companies room for operating improvement. If it stumbles again, earnings could feel it.
The most relevant recent announcement is TJX Companies setting a goal to open at least 1,300 additional locations globally. That expansion plan leans on the same sourcing, distribution and traffic engines now under scrutiny at Marmaxx. As a result, the current missteps effectively become a live test of whether the model scales cleanly.
New Marshalls stores rolling out across states like New York, Texas, Massachusetts and California keep unit growth visible as a catalyst, even while investors track near term comp volatility. Those openings increase fixed commitments. Execution on merchandising, freight cost control and customer engagement will matter more as this larger footprint comes on line.
TJX Companies Consensus Assumptions and Valuation Bridge
TJX Companies' narrative projects US$75.6b revenue and US$7.3b earnings by 2029. Analysts are building this on 6.6% yearly top line growth and an earnings increase of about US$1.2b from US$6.1b today.
Uncover why TJX Companies' fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest TJX Companies analysts focus on rising freight and fuel costs as the real swing factor, not just Marmaxx mix. Before this news, they were penciling in about US$74.1b of revenue and US$7.0b of earnings by 2029. That is a more cautious story. Use this gap in views to explore several possible futures, not just one.
Explore 7 other TJX Companies fair value estimates, including one that suggests as much as 26% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TJX Companies research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for TJX Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TJX Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond TJX Companies?
Once you have a view on TJX Companies, it can help to compare that opinion with opportunities across the wider market using the Simply Wall St Screener.
- For investors who want potential upside with a margin of safety, start with a focused pool of 32 high quality undervalued stocks that combine quality fundamentals with pricing that may leave room for re rating.
- If consistent income is a priority, narrow your search to companies with resilient payouts by reviewing our curated set of 7 dividend fortresses that meet a minimum 5% yield hurdle.
- To keep risk in check while still targeting returns, filter for businesses with stronger financial profiles by using our list of solid balance sheet and fundamentals (25 results) as your shortlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com