
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Pfizer (PFE) Could Be 60% Below Fair Value On Tukysa Approval And Vaccine Data
Pfizer (PFE) stock moved after a busy October for the drugmaker. Investors reacted to a new frontline approval for Tukysa in HER2-positive metastatic breast cancer, as well as new vaccine data released ahead of IDWeek 2026.
The latest oncology approval and vaccine readouts arrive after a strong run in Pfizer’s shares, with a 90 day share price return of 16.19% and a year to date share price gain of 16.00%. The 1 year total shareholder return of 28.16% suggests momentum building rather than fading.
Scan how Pfizer’s move on oncology and vaccines compares with peers by running a quick check on 34 healthcare AI stocks as potential next research ideas.
Pfizer now trades near a two year high after oncology wins and fresh vaccine data, so the question is whether to lean into this momentum or wait for a better price before running the numbers.
Most Popular Narrative: 1% Overvalued
Pfizer closed at $29.21 against a most-followed fair value estimate of $28.88, which leaves the stock sitting just above that narrative anchor while attention shifts to obesity, oncology and cost savings rather than COVID revenue.
Oncology portfolio build out centered on antibody drug conjugates and targeted agents, including the Seagen assets and new internal programs such as mevrometostat with a pivotal prostate cancer trial readout expected in Q4 2026, supports expectations that oncology can contribute a larger share of total sales and cash flow as new indications are approved and adopted.
See why 545 investors see Pfizer as 1% overvalued.
Result: Fair Value of $28.88 (OVERVALUED)
Still, the Pfizer story can break if drug pricing pressure bites harder than expected, or if setbacks in key oncology or obesity programs chip away at that fair value anchor.
Find out about the key risks to this Pfizer narrative.
Another View: Pfizer through the cash flow lens
That 1% overvaluation call sits awkwardly next to Simply Wall St's DCF work. On this measure, Pfizer at $29.21 trades about 60% below an estimated future cash flow value of $73.64, which paints the stock as cheap rather than stretched. Which story do you think best reflects the risks you care about?
For a closer look at the moving parts behind that cash flow driven fair value, Look into how the SWS DCF model arrives at its fair value.
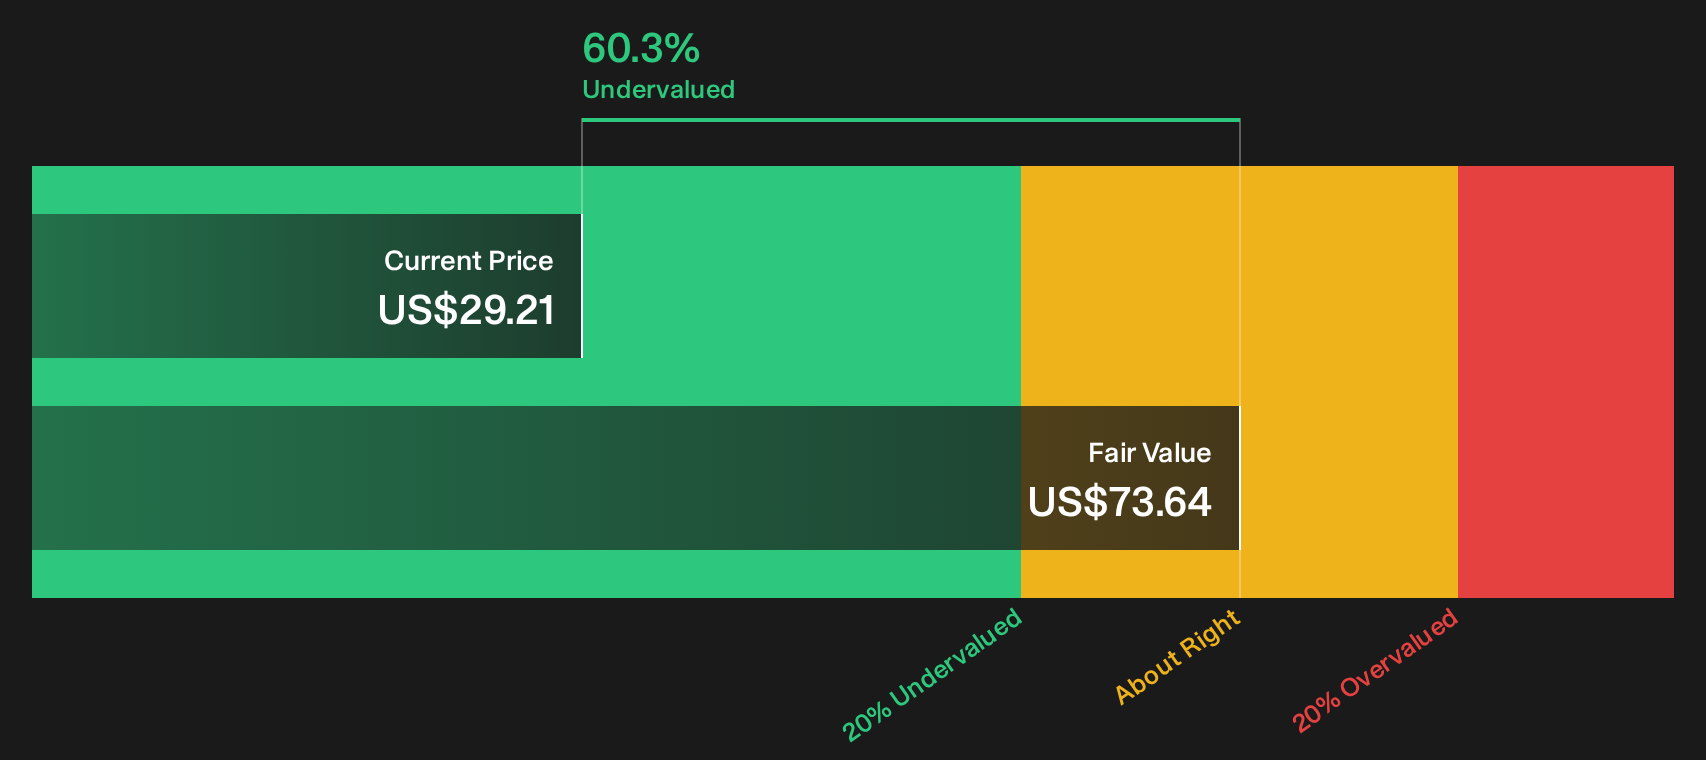
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pfizer for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Momentum stories like Pfizer can feel convincing, yet the real edge comes from weighing both optimism and caution yourself while the data is fresh. Run through the full picture, including 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Pfizer?
You have fresh data on Pfizer. Do not stop there when the same tools can surface other opportunities that might fit your goals even better.
- Target potential upside by scanning a curated pool of companies trading below intrinsic estimates using the 32 high quality undervalued stocks.
- Seek more dependable income streams by focusing on businesses screened for higher yields and resilience through the 7 dividend fortresses.
- Aim to reduce portfolio stress by concentrating on sturdier balance sheets and healthier fundamentals identified by the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com