
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Agnico Eagle Mines (AEM) Keep Trading At A Discount?
Agnico Eagle Mines has delivered a very large 3 year share price gain, yet recent swings and fresh headlines around gold markets leave a simple question on the table for investors. Is the current US$177.01 price adequately supported by what the company is earning today and what those earnings may justify over time?
- Over the past 3 years the stock has returned about 277.8%, which puts real pressure on the question of whether its earnings still line up with that move.
- Recent reports of high grade gold discoveries near Agnico Eagle’s operations and its ability to generate solid realized prices and return cash to shareholders can shape assumptions about how durable and predictable its profit base might be.
- There is a second opinion on Agnico Eagle Mines worth weighing. See what analysts think Agnico Eagle Mines's shares could be worth.
The issue now is whether Agnico Eagle Mines' current valuation is properly explained by its earnings power once you put the recent share price performance into context.
To pressure test whether Agnico Eagle Mines' 277.8% three year gain and current earnings story still stack up, it can help to compare with 35 elite gold producer stocks
Is Agnico Eagle Mines a Bargain on Earnings?
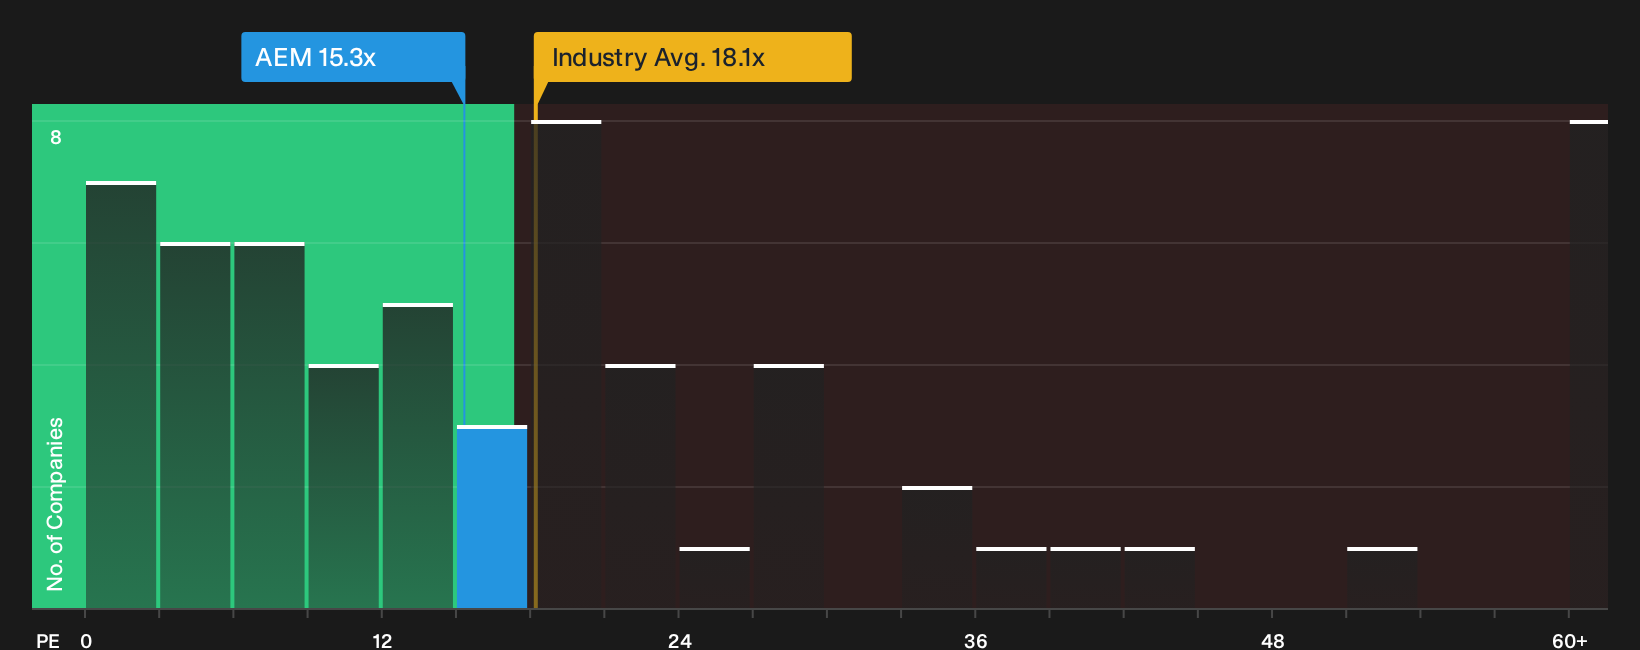
P/E suits Agnico Eagle Mines because earnings remain a primary anchor for how investors weigh a large, established gold producer. At the current US$177.01 share price, the stock trades on a P/E of 15.3x, compared with about 18.1x for the wider Metals and Mining sector and roughly 17.3x across peers. On this simple comparison, the market is assigning a lower earnings multiple than both the sector and similar companies.
That discount looks more striking because the fair P/E implied by a more tailored model, which folds in Agnico Eagle Mines' margins, risk profile and scale, sits above the current 15.3x level and points to the shares pricing in a degree of caution. Because the company recently reported a realised gold price above US$4,400 per ounce and returned US$625 million to shareholders, the lower P/E suggests investors are treating that performance as already in the rear view mirror rather than paying up for it today. Explore the numbers behind Agnico Eagle Mines's P/E valuation.
The Agnico Eagle Mines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Agnico Eagle Mines take that valuation puzzle and turn it into clear, testable stories about what would need to happen to future growth, margins and earnings for the current price to look too high or too low. Each scenario links a fair value estimate to a particular mix of potential catalysts and risks, so you can track how Agnico Eagle Mines' actual progress compares with those paths over time on the Community page.
One of the top community narratives on Agnico Eagle Mines: 18% undervalued
"Continuation of strong free cash flow generation, highlighted by about $1.3b in Q2 2026 and supported by company wide cash costs and all in sustaining costs..."
Discover why this Narrative puts Agnico Eagle Mines at 18% undervalued.
Agnico Eagle Mines is more than a ticker and a price tag
The next thing to scrutinize is who actually runs Agnico Eagle Mines, how their rewards line up with shareholder outcomes, and whether those incentives really point in the same direction as your capital. See who runs Agnico Eagle Mines and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com