
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Chemring Group And 2 British Defense Stocks To Watch
Norway’s plan to review ethical rules for its $2.3b sovereign wealth fund, including a potential shift on investing in nuclear weapons related companies, has pushed defence spending firmly back into the spotlight. For United Kingdom aerospace and military contractors, that kind of institutional attention can shape order books and investor focus. This article walks through three Aerospace and Defense screener stocks that reflect how this theme is playing out right now.
The three Aerospace and Defense stocks covered next are just a sample, and the full screen surfaced 9 more companies with equally detailed stories that are not included here. To size up the wider field and identify your own highest conviction ideas, head straight to the Aerospace And Defense screener.
Chemring Group (LSE:CHG)
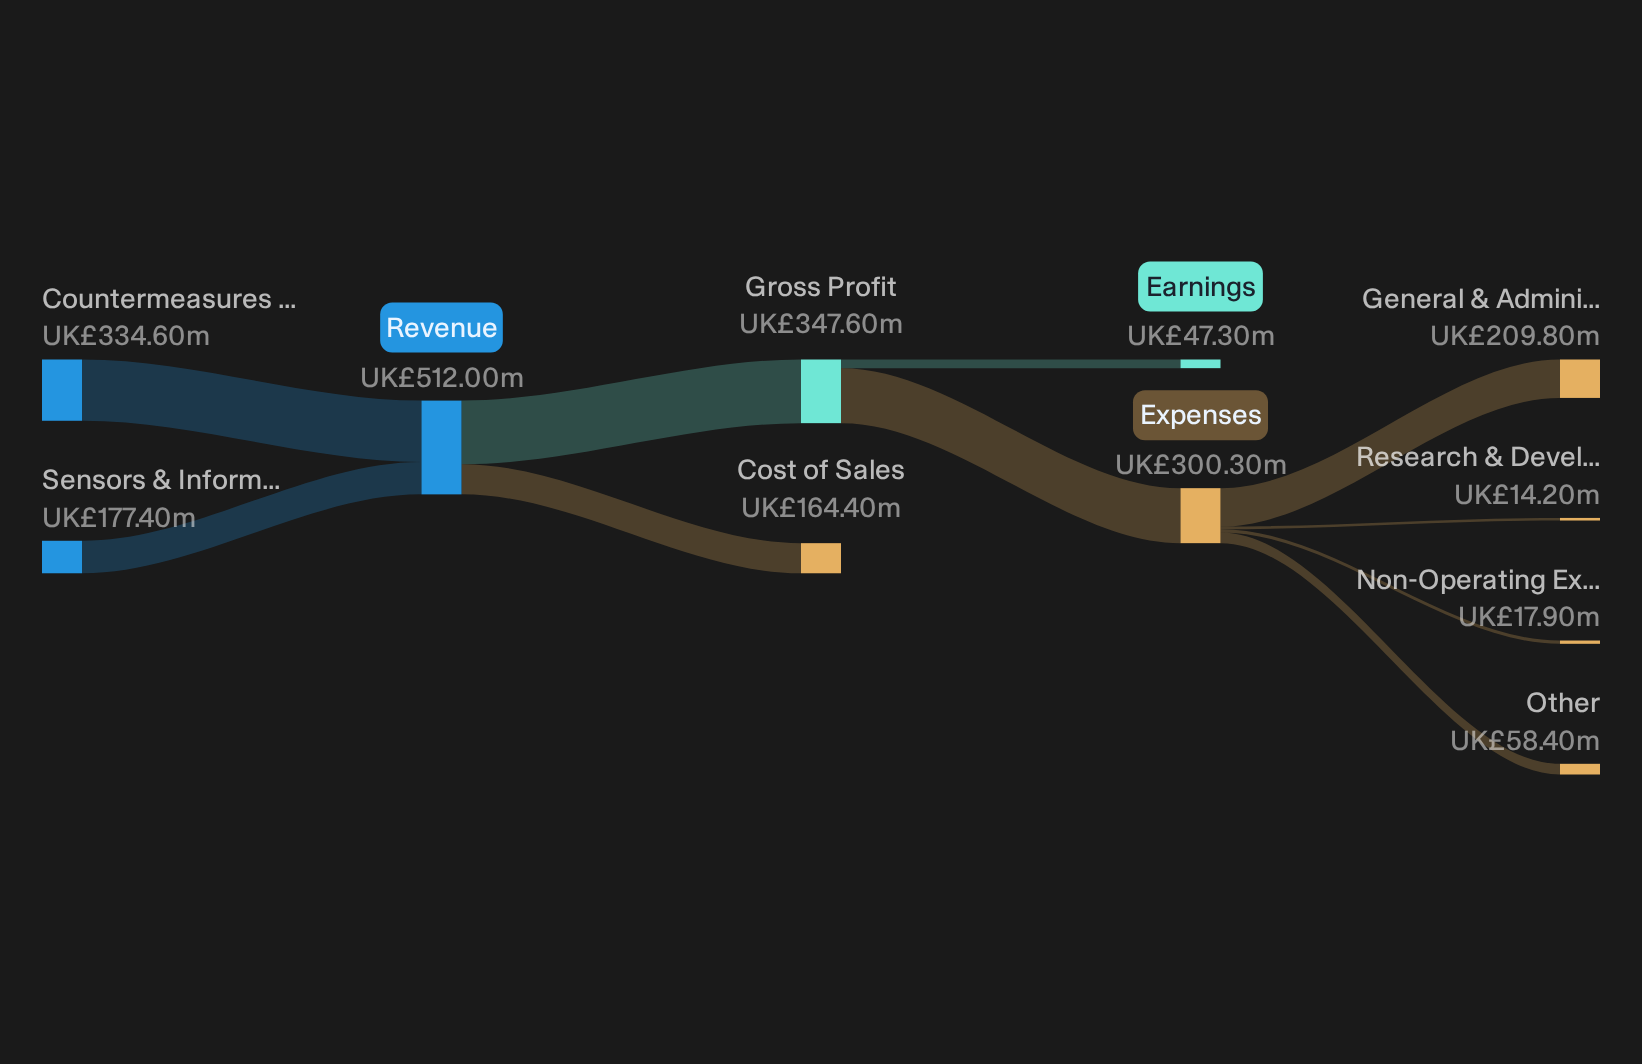
Chemring Group is a £1.39b defence contractor that supplies aircraft flare countermeasures, energetic materials and specialist sensors, with £334.6 million of revenue from Countermeasures & Energetics and £177.4 million from Sensors & Information, giving investors direct exposure to core Aerospace and Defense programmes.
Chemring Group’s appeal in this screener comes from its role supplying the unglamorous but essential hardware that keeps aircraft and crews alive. Its countermeasure flares, gas generators and actuation systems are tied directly to defence budgets rather than consumer cycles.
"The expansion of Chemring Nobel is a major growth opportunity, with plans to increase production capacity by up to 275% due to high demand for military energetic materials, which will enhance future revenue streams."
What ultimately matters for Chemring Group is how one unseen pressure shapes the balance between higher demand and the profitability of each contract.
To see how that pressure really plays out across contracts and cash flows, read the full narrative for Chemring Group to understand what demand, pricing and capacity expansions might be masking.
Babcock International Group (LSE:BAB)
Babcock International Group is a £4.48b defense contractor closely tied to the screener theme through its Marine and Aviation work building and supporting military platforms. It also runs sizeable Nuclear (£2.07b) and Land (£1.08b) operations alongside £1.59b from Marine and £431 million from Aviation.
Babcock International Group gives you exposure to the nuts and bolts of defense infrastructure, from warship construction to keeping fleets in service, with much of its workload linked to long-running government programs. In these programs, performance can influence how much extra work is awarded.
"Strong operational performance and delivery can drive future growth as Babcock has a lot of frame contracts where discretionary work is awarded based on performance, which could positively impact revenue."
What really matters next is how one quiet shift in those long-term defence frameworks affects margins and the timing of cash coming through.
That quiet shift is exactly what the full narrative for Babcock International Group unpacks, highlighting where accelerating frame work, risk and upside may be decoupling from headline contracts.

BAE Systems (LSE:BA.)
BAE Systems anchors this Aerospace and Defense screener through its Air and Platforms & Services operations, which build combat aircraft systems, vehicles, weapons and munitions alongside naval programs. The group also runs sizeable Electronic Systems, Maritime and Cyber & Intelligence units, together generating revenue in the tens of billions and supported by a £53.7b market value.
For investors focusing on defense exposure, BAE Systems offers a mix of large-scale platforms and higher value electronics that is closely linked to long-term military programs. This sets up the context for what matters most in its current order book.
"The company's order backlog has surged to £75 billion, with a pipeline of new opportunities partly fueled by higher defense spending commitments across NATO, the US, UK, Europe, and Indo-Pacific, providing visibility on future revenues and supporting topline growth over multiple years."
What could significantly affect BAE Systems now is how one unresolved bottleneck shapes the conversion of that backlog into margins and cash.
If that bottleneck is on your mind, the full narrative for BAE Systems walks through how backlog conversion, capital intensity, and contract risk could be accelerating or quietly stalling BAE Systems’ story.

Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time every headline chases the same tickers, the cleanest entry points are often gone. Scan these focused lists while it matters and consider acting before they become crowded.
- Spot potential income opportunities by reviewing 3 dividend fortresses, which combines higher yields with balance sheets built to keep paying when momentum in other areas is dropping.
- Track early AI momentum shifts through 39 profitable AI stocks that aren't just burning cash, where the focus is on businesses already producing cash rather than burning it while they are still under the radar.
- Scan quietly improving balance sheets using the list of solid balance sheet and fundamentals (9 results) so you can identify quality upgrades before the wider market fully recognizes the change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com