
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Graco (GGG) Heads Into Earnings With M And A In Focus While Valuation Debate Builds
Graco (GGG) heads into its September quarter earnings report on October 21 with expectations for higher profit and sales, and a recent shift in sentiment around those forecasts giving investors more to weigh.
Graco’s recent 7 day share price return of 3.93% and 30 day gain of 5.15% put the stock at $80.48. The year to date share price performance is still down 2.61%, and the 5 year total shareholder return of 17.18% points to steadier long run compounding despite the softer 1 year total shareholder return of 0.75% and cooler sentiment around earnings estimates.
Scan how Graco’s setup compares with other industrials by running your filters against our curated list of solid balance sheet and fundamentals (25 results) right after this earnings update.
After a quick rebound and a price of $80.48, Graco still trades below both analyst targets and intrinsic value estimates. How much of that gap reflects genuine upside versus a fair discount for risk?
Most Popular Narrative: 12% Undervalued
Graco’s most followed narrative puts fair value at $91.29, compared with the current $80.48 share price, so the story hinges on whether the business can keep translating its operating model into durable earnings and cash flow.
The main factor that must go right is continued execution on disciplined M&A and integration, so acquired businesses such as COROB, Color Service, Radia and Valco Melton contribute meaningfully alongside organic semiconductor and infrastructure demand.
The integration of COROB and other acquired businesses such as Color Service and Radia, which together are expected to generate about US$190 million of annual revenue, extends Graco into tinting and related niches and can add to revenue and earnings as these operations scale.
See why 10 investors see Graco as 12% undervalued.
Result: Fair Value of $91.29 (UNDERVALUED)
Still, this Graco story can break if tariff costs can no longer be passed through to customers, or if organic demand softens again while pricing power fades.
Find out about the key risks to this Graco narrative.
Another View: What Graco’s P/E Is Telling You
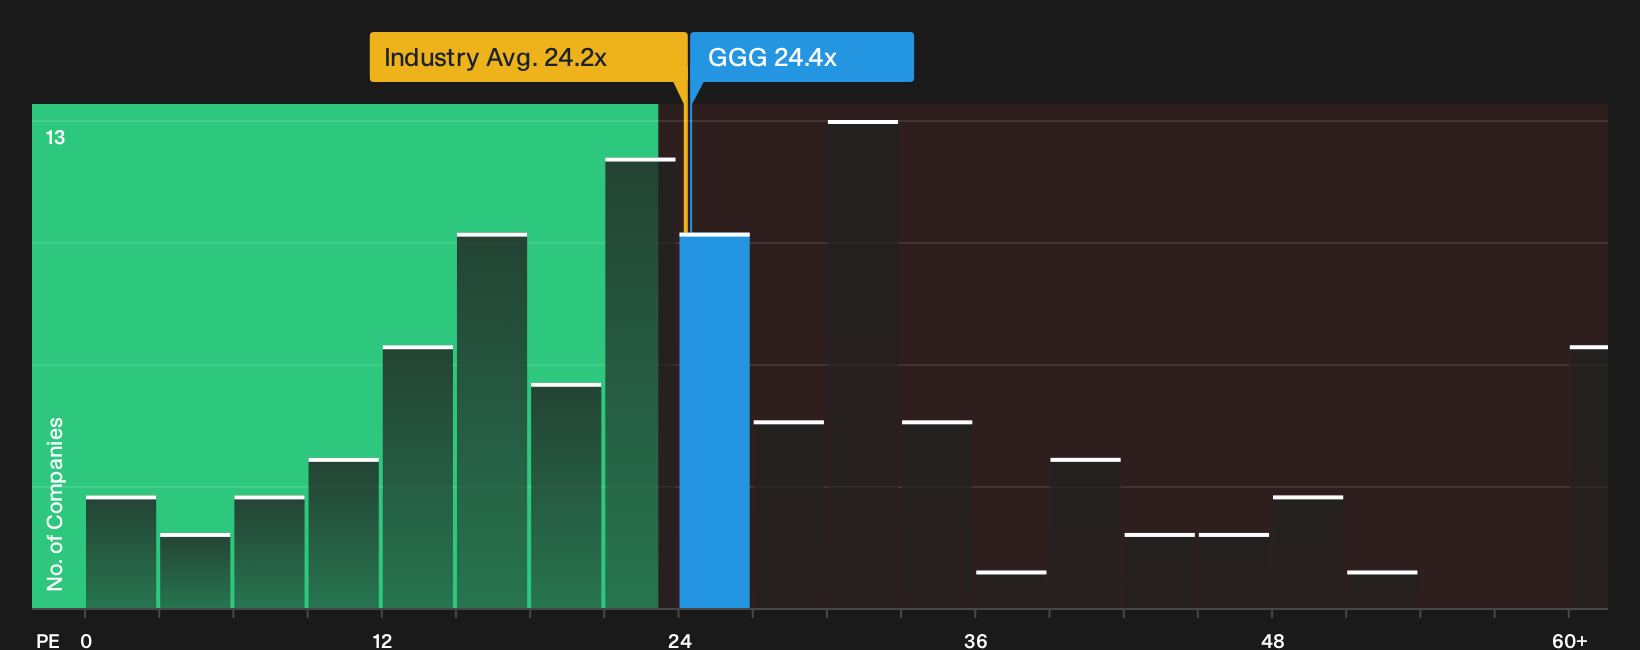
Graco also screens as expensive on earnings. The current P/E is 24.4x versus a 23.4x peer average, while the fair ratio for the stock is 19.6x. That gap points to valuation risk if growth or returns on equity land closer to the more cautious forecasts.
If you want a cleaner sense check based purely on earnings multiples, the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Graco is split, which is exactly when it helps most to test the numbers yourself instead of relying on the crowd. To see what optimistic investors are focused on, walk through the 4 key rewards
Looking For More Ideas Beyond Graco?
If you only focus on Graco, you might miss other setups that fit your style. Let the Simply Wall St Screener surface a few fresh candidates.
- Target resilient balance sheets and steady fundamentals by scanning our focused list of solid balance sheet and fundamentals (25 results) that filters for financial strength first.
- Hunt for potential value opportunities by running the screener on the 32 high quality undervalued stocks that match your comfort on risk and quality.
- Zero in on income potential by filtering for companies in the 7 dividend fortresses that may align with your cash flow goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com