
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SK hynix (KOSE:A000660) Shares Slide As AI Spending Fears Hit Chip Stocks
- SK hynix (KOSE:A000660) shares were hit during a broad sell off in South Korean chip stocks as AI spending worries escalated.
- Investors reacted to concerns that global AI infrastructure budgets are becoming stretched, pressuring expectations for high end memory demand.
- Fears over faster progress from Chinese memory producers such as CXMT raised questions about South Korean suppliers' future market share.
- The sharp pullback, tied to AI spending concerns and Chinese competition, should sit alongside other key factors in any SK hynix view. Check out 4 other big wins that SK hynix investors should know about.
To put the SK hynix move in context, compare it with a wider group of chip and hardware suppliers tied to AI infrastructure through 92 AI infrastructure stocks.
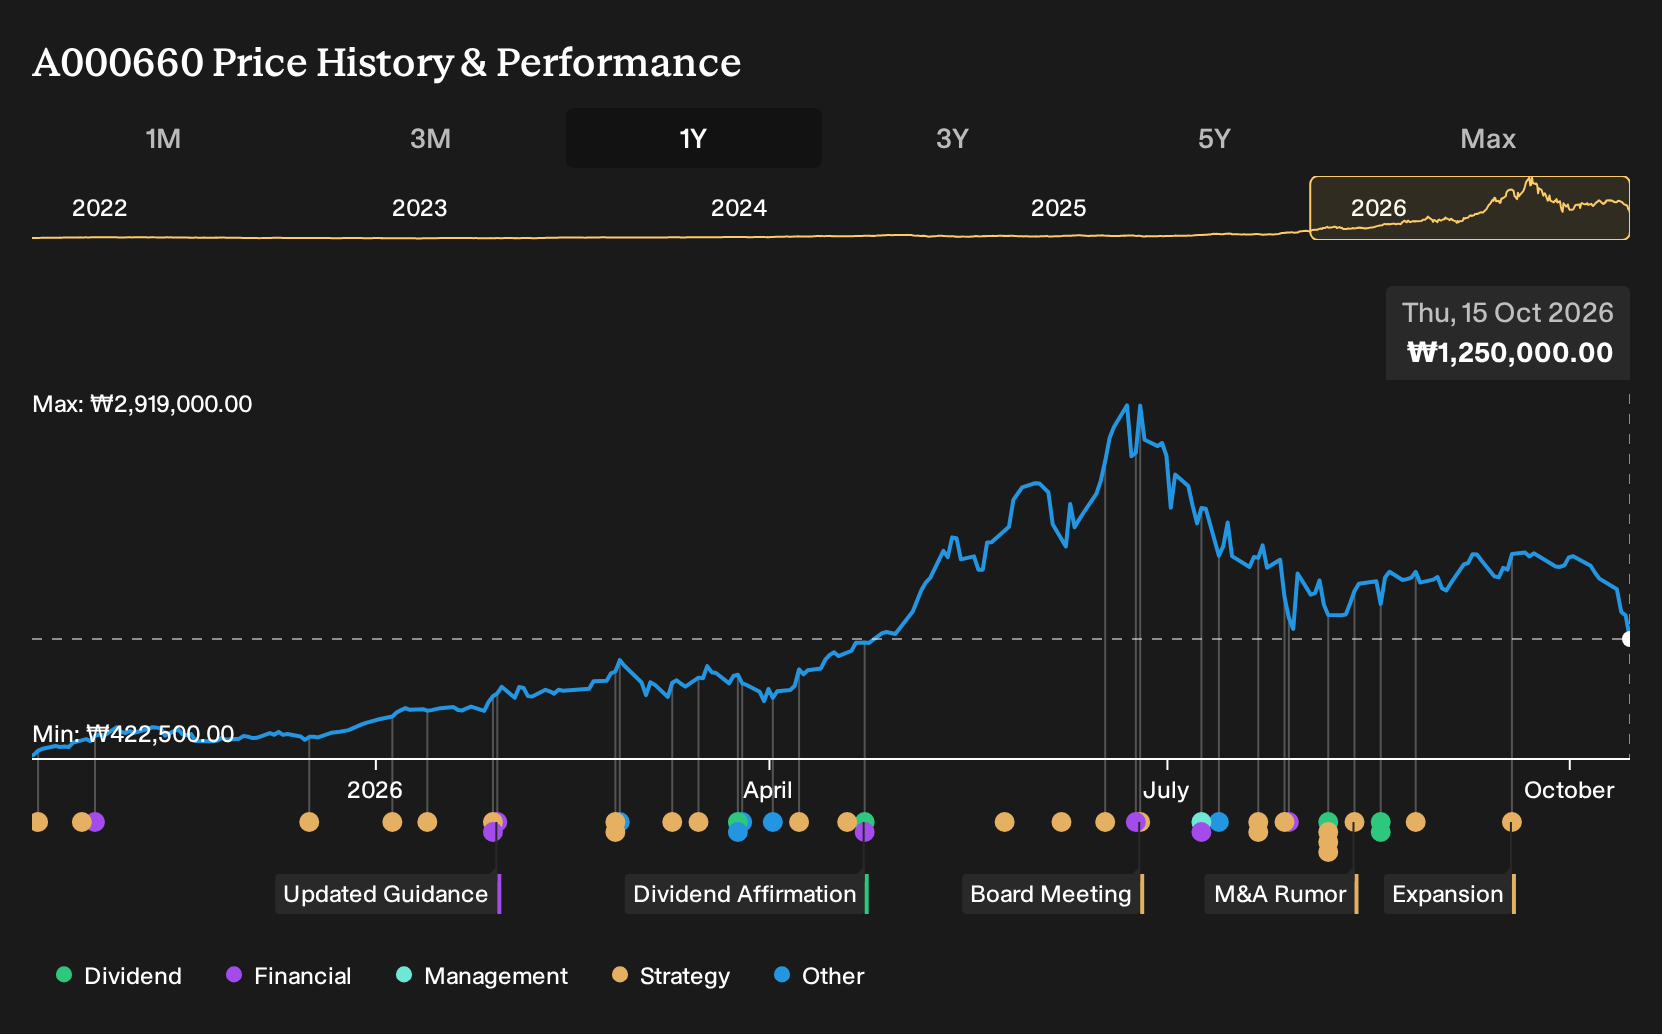
SK hynix develops and sells memory chips that underpin servers, data centers, and devices used in AI workloads, with operations stretching across Korea, China, the wider Asia region, the United States, and Europe. Because the company is exposed to these global infrastructure customers, shifts in AI spending and competitive pressure from Chinese manufacturers are especially important for its business outlook.
See which insiders are buying and selling SK hynix following this latest news.
What is this SK hynix drop really saying about AI sentiment?
The pullback in SK hynix alongside other chip stocks echoes worries seen in hardware suppliers where enterprise AI spending has lagged expectations and memory pricing has done more of the heavy lifting. It signals a market mood shift from blanket enthusiasm for AI infrastructure to a more selective focus on where revenue is already visible.
Does this change the SK hynix narrative around AI memory and capex?
The slide cuts into the central narrative for SK hynix, which is heavy AI focused capex in the high ₩40 trillion range and whether that spending stays matched to demand. Worries about Chinese progress and tighter AI budgets challenge the idea that capacity additions and long term HBM agreements will keep earnings on the path analysts have mapped out.
See how these catalysts shape SK hynix's path to a ₩3,141,025 fair value.
What is the next concrete data point to watch for SK hynix?
The next key checkpoint is SK hynix management’s upcoming guidance update, especially any revision to the outlook for DRAM demand growth in 2026 and capex plans in the high ₩40 trillion range. A change in either number would give a clear signal on how the business is recalibrating to the latest AI and competitive backdrop.
One unresolved question for SK hynix investors
There is a crucial angle still untouched: who actually sets SK hynix priorities in the boardroom, and what incentives guide those decisions over the next few years. See who is actually steering SK hynix, and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com