
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Undiscovered Gems in Global Markets October 2026
As global markets navigate through a landscape marked by mixed performances in major U.S. stock indexes, volatile oil prices due to Middle East tensions, and fluctuating Treasury yields, investors are increasingly turning their attention to small-cap stocks for potential opportunities. In this environment, identifying undiscovered gems involves seeking companies that demonstrate resilience amidst economic uncertainties and possess strong fundamentals that can withstand market volatility.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
| Bastide Le Confort Médical | 263.37% | 2.00% | -22.93% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
ITAB Group (OM:ITAB)
Simply Wall St Value Rating: ★★★★☆☆
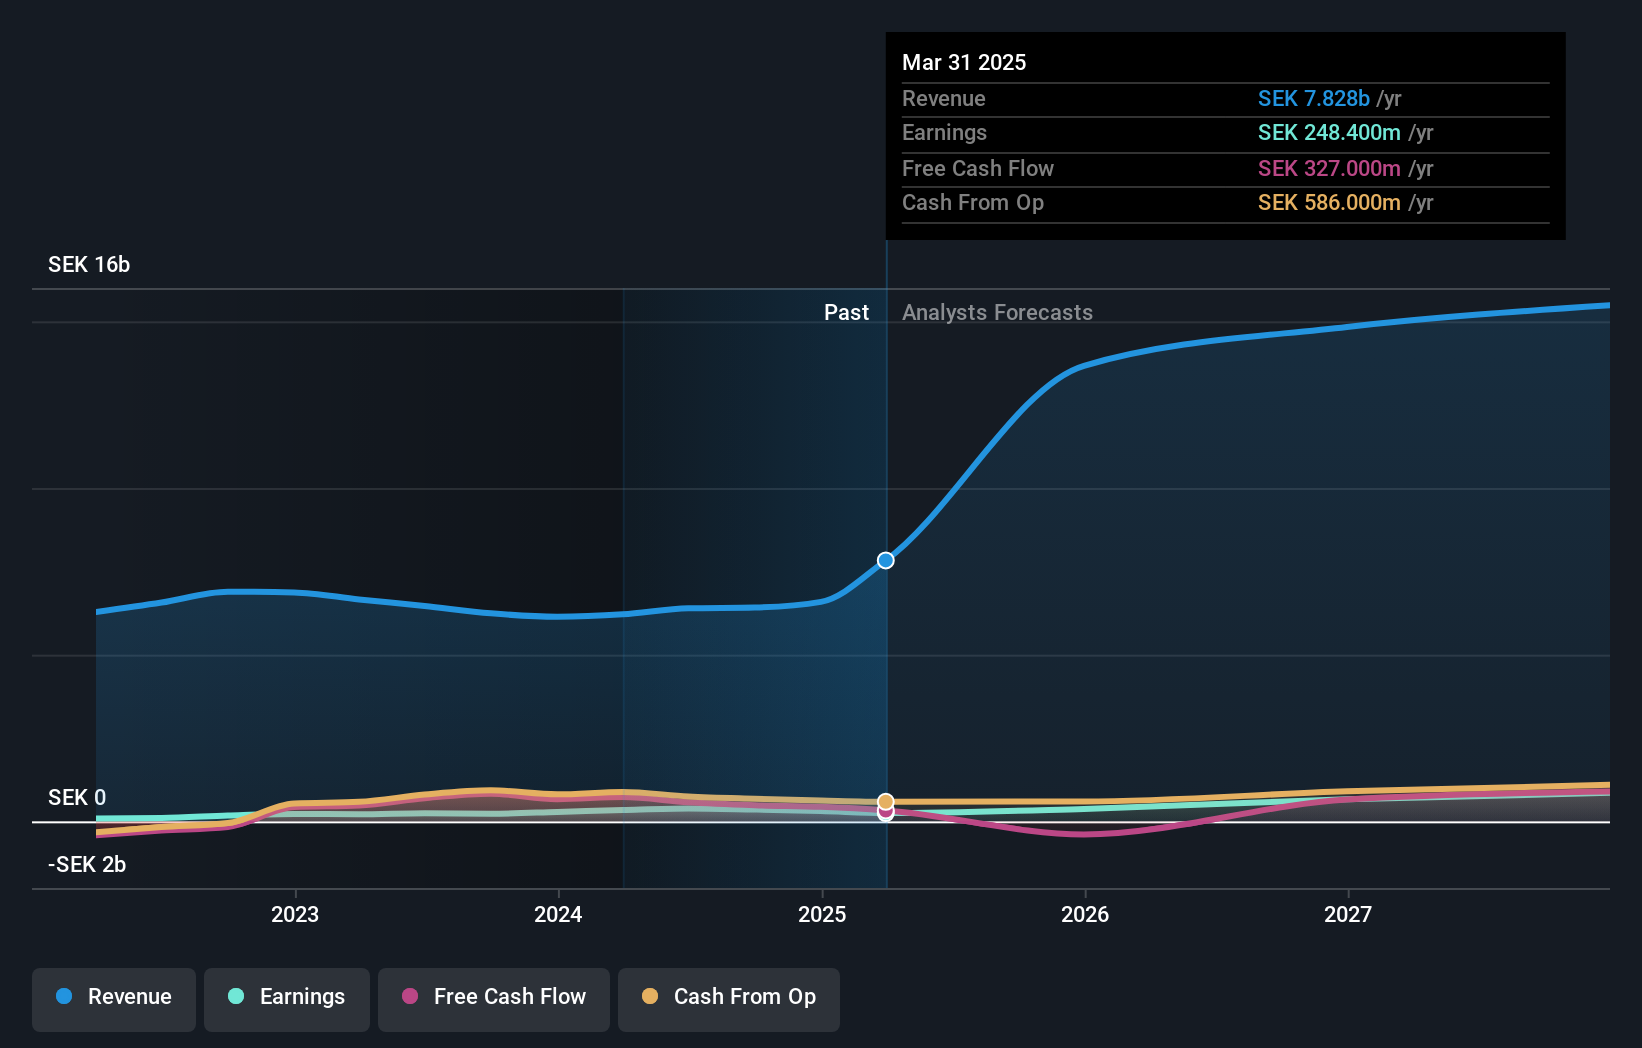
Overview: ITAB Group AB (publ) specializes in developing, manufacturing, selling, and installing store concepts for retail chain stores with a market capitalization of approximately SEK4.19 billion.
Operations: The primary revenue stream for ITAB Group comes from its Furniture & Fixtures segment, generating SEK12.84 billion. The company's financial performance is influenced by its cost structure and market demand in the retail sector.
ITAB Group, a smaller company in the commercial services sector, has shown consistent earnings growth of 17% annually over the past five years. Despite this, its recent 18% earnings increase lagged behind the industry average of 22%. The company's net debt to equity ratio stands at a high 53%, reflecting increased leverage from 32% five years ago. ITAB's interest payments are comfortably covered by EBIT at nearly five times, indicating strong operational performance. Recent developments include a significant NOK 320 million agreement with REMA 1000 and an SEK 244 million non-recurring charge due to an ERP project discontinuation.
- Navigate through the intricacies of ITAB Group with our comprehensive health report here.
Understand ITAB Group's track record by examining our Past report.
Alkhorayef Water and Power Technologies (SASE:2081)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Alkhorayef Water and Power Technologies Company focuses on designing, constructing, operating, maintaining, and managing water and wastewater projects in Saudi Arabia with a market cap of SAR2.92 billion.
Operations: The company's revenue streams are primarily derived from its wastewater segment at SAR958.77 million, followed by the water segment at SAR876.40 million, and integrated water solutions contributing SAR384.98 million.
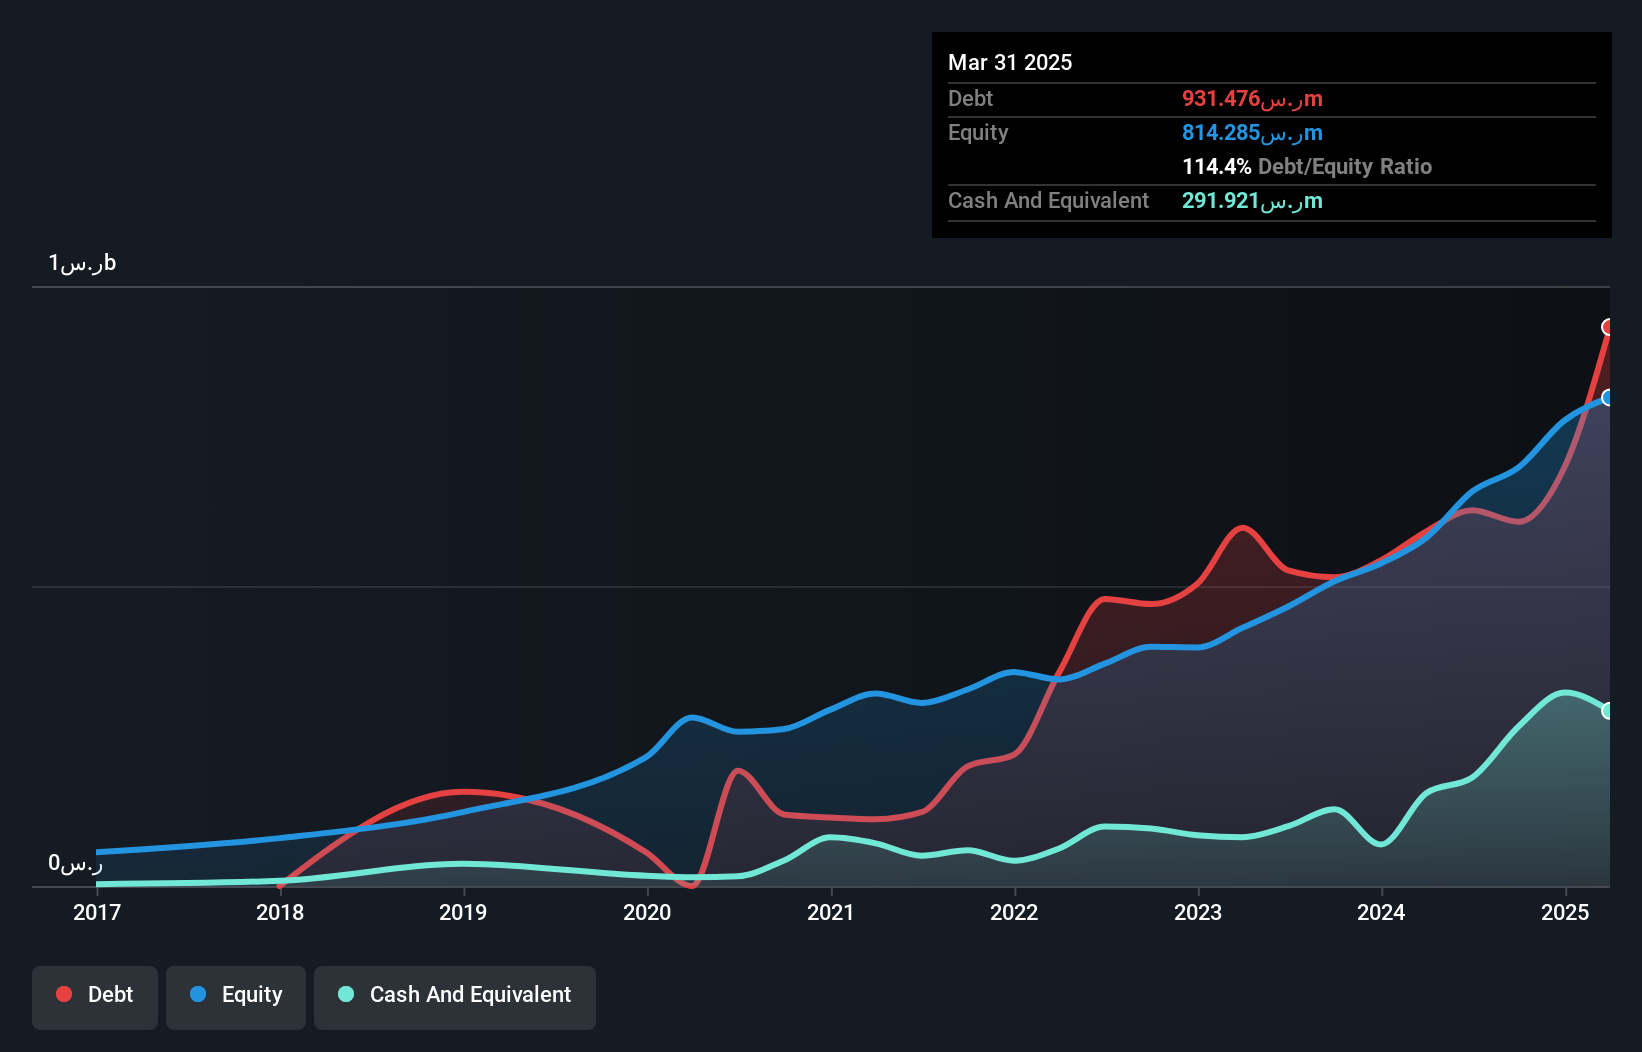
Alkhorayef Water and Power Technologies, a dynamic player in the water utilities sector, has shown impressive earnings growth of 14.9% over the past year, outpacing the industry’s 6.7%. Trading at 22.1% below its estimated fair value, it presents an attractive opportunity compared to peers. Despite a high net debt to equity ratio of 97.4%, interest payments are well covered by EBIT at 24.3x coverage, indicating strong financial management. Recent contracts for infrastructure projects worth SAR 79 million and SAR 101 million are likely to bolster future revenues as they begin impacting finances in Q4 2026.
Almasar Alshamil Education Company JSC (SASE:6019)
Simply Wall St Value Rating: ★★★★★☆
Overview: Almasar Alshamil Education Company JSC provides education services in Saudi Arabia and the United Arab Emirates, with a market capitalization of SAR2.15 billion.
Operations: The company generates revenue primarily from its education segment, totaling SAR596.77 million. The focus on education services in Saudi Arabia and the UAE is central to its financial operations.
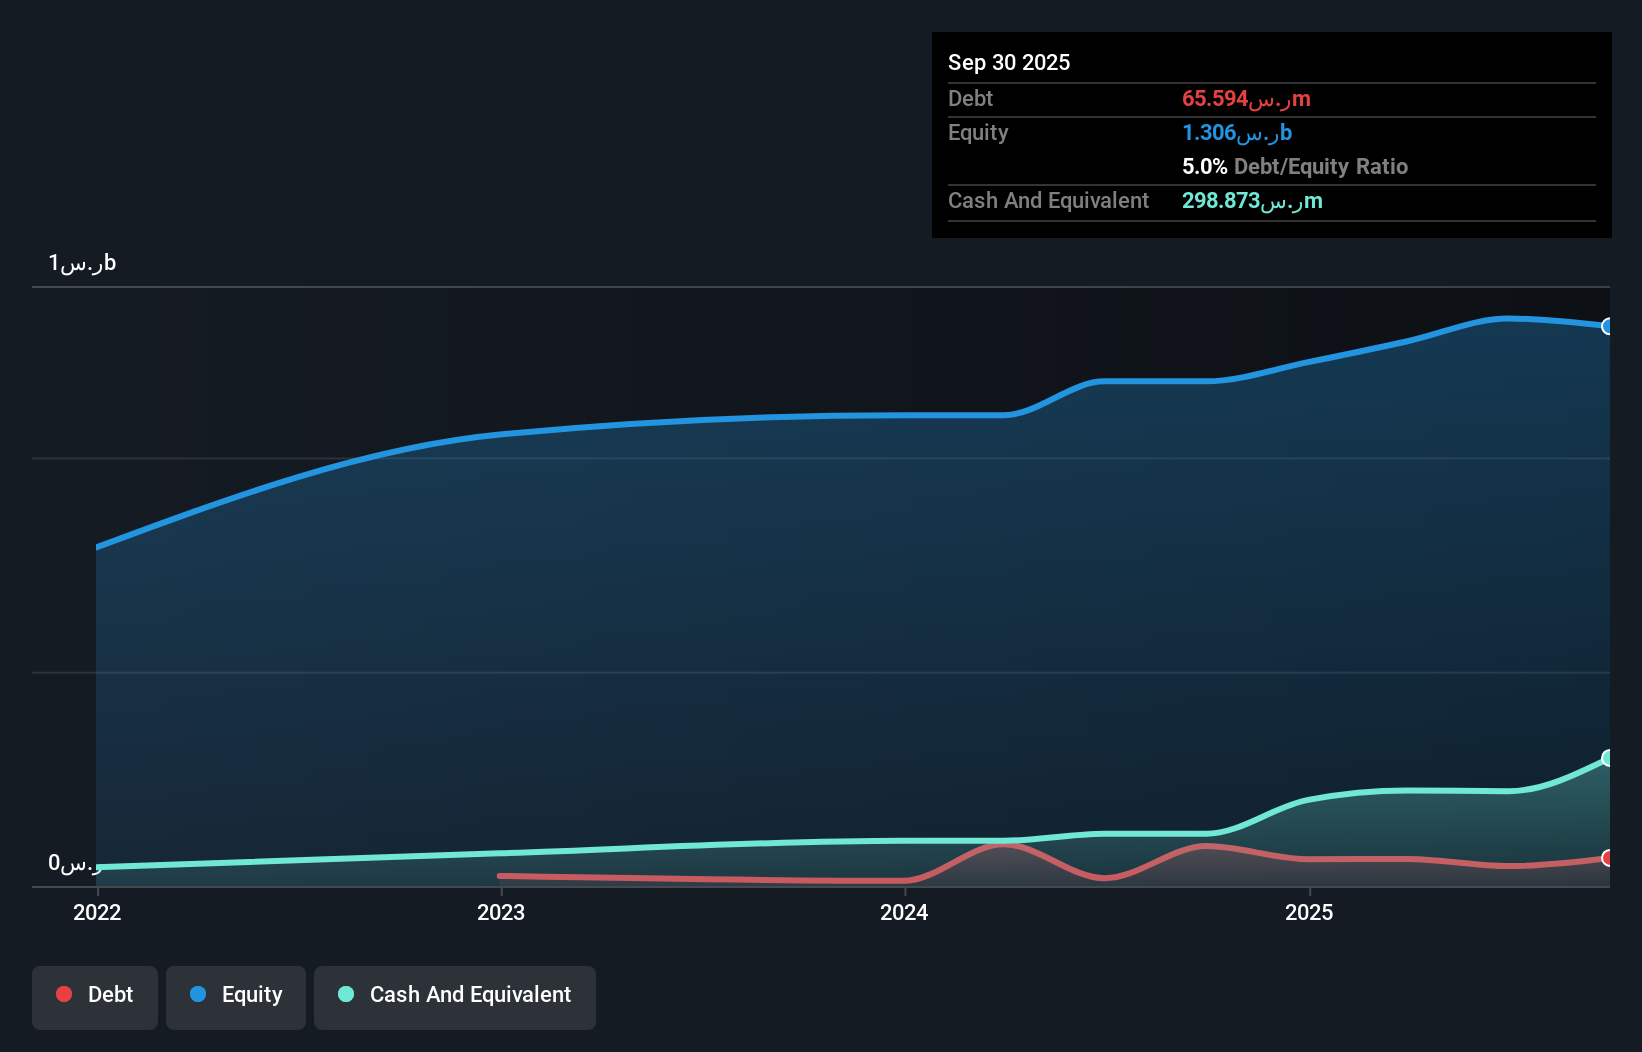
Almasar Alshamil Education Company JSC has shown promising growth, with sales reaching SAR 163.35 million in Q2 2026, up from SAR 134.31 million the previous year. Net income also rose to SAR 64.7 million compared to SAR 50.17 million a year prior, reflecting a positive trajectory in earnings per share at SAR 0.63 from continuing operations versus last year's SAR 0.49. The company trades at an attractive valuation, estimated to be trading at about half of its fair value and enjoys robust coverage of interest payments by EBIT at over sixty times, indicating strong financial health and operational efficiency within its sector.
Key Takeaways
- Click here to access our complete index of 174 Global Undiscovered Gems With Strong Fundamentals.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com