
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To ASML Holding (ENXTAM:ASML) Raised Sales Forecast
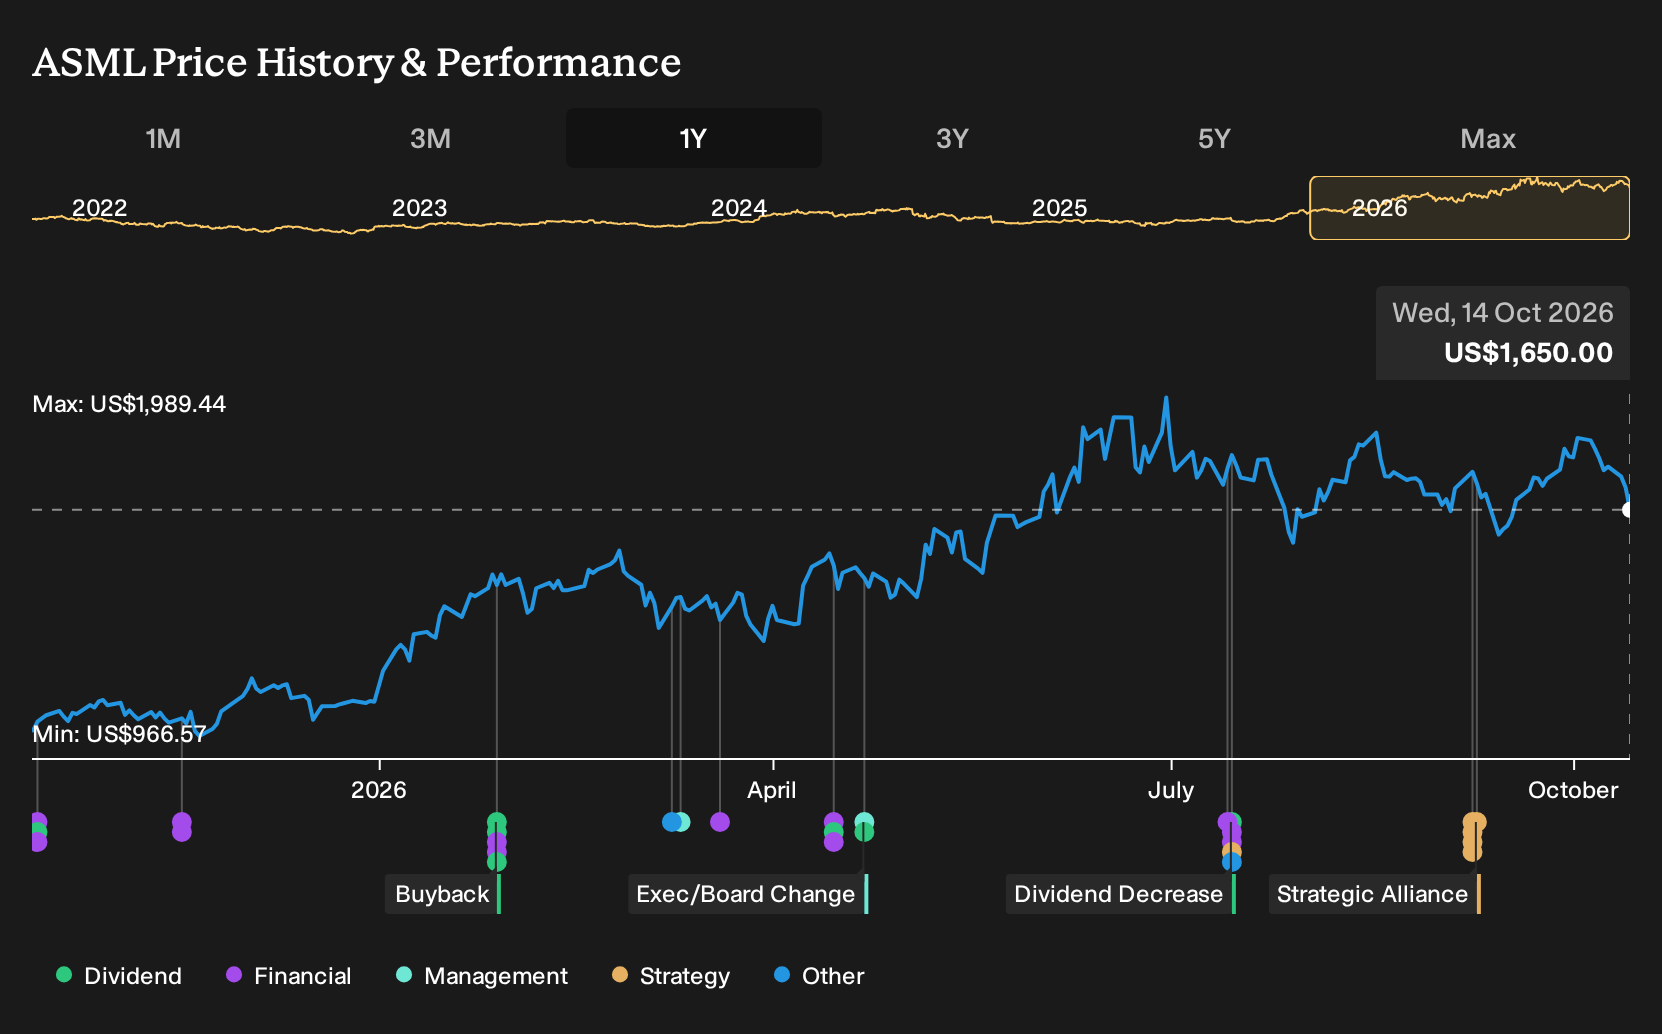
- ASML Holding reported record Q3 2026 net sales of €11.7b and guided Q4 net sales of €14.2b to €15.2b, while lifting full year 2026 sales expectations to a range of €44b to €45b with a gross margin around 56%.
- The group now expects demand for its advanced lithography tools to exceed planned capacity through at least 2028, with some customers already placing orders for 2029 and 2030. This development tightens the supply backdrop for AI focused chipmakers.
- Next, the focus shifts to how ASML Holding's stronger guidance and tight capacity outlook could reshape the longer term investment narrative.
Scan the AI supply chain beyond ASML Holding by reviewing our hand picked 92 AI infrastructure stocks.
ASML Holding Investment Narrative Recap
To own ASML Holding, you need to believe that demand for advanced EUV and High NA tools, plus growing installed base services, can absorb planned capacity increases and sustain high margins over time. The fresh 2026 guidance, with net sales of €44b to €45b and a gross margin around 56%, reinforces that operating backdrop rather than changing it.
Right now the key short term swing factor is execution on capacity ramp and High NA rollout, while order visibility stretches into 2029 and 2030. The biggest risk remains external, not operational, with export controls and broader AI related selloffs still capable of hitting orders or compressing valuation even if results track guidance.
The recent confirmation of an interim 2026 dividend of €1.88 per share lands alongside heavy reinvestment in EUV, High NA and installed base growth. That mix matters: it shows ASML Holding allocating cash both to shareholders and to the tools that underpin its long term order book, rather than pivoting sharply in either direction.
For investors watching catalysts, this dividend sits next to an active buyback programme and the updated outlook as part of one capital return and capacity story. The cash payout does not change the operational thesis on AI driven lithography demand. It does add another concrete data point on balance sheet strength and management confidence in the current guidance path.
ASML Holding's current analyst narrative points to forecast 2029 revenues of €66.5b and earnings of €25.9b, based on an assumed 23.5% yearly revenue growth rate and an earnings increase of about €15.3b from €10.6b today to the 2029 consensus level.
Uncover why ASML Holding's fair value indicates a 34% potential upside to its current price, which could be realized more quickly than many investors expect.
Exploring Other Perspectives
One alternate view zooms in on AI capacity as a catalyst. The most optimistic ASML Holding analysts were already pencilling in revenue of €85.0b and earnings of €36.7b by 2029 before this guidance, assuming 34% yearly top line growth. That is a far more aggressive story than consensus, and it may shift again after this update, so treat it as one of several viewpoints to explore rather than a script you must follow.
Explore 22 other ASML Holding fair value estimates, including one that suggests as much as 64% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ASML Holding research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ASML Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ASML Holding's overall financial health at a glance.
Looking for more investment ideas beyond ASML Holding?
Once you have formed a view on ASML Holding, it can help to cross check that thesis against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- If capital preservation ranks high for you, consider starting with a group of 222 resilient stocks with low risk scores that our models flag as having more resilient profiles.
- For investors hunting for quality at a reasonable price, compare ASML Holding with a 191 high quality undervalued stocks that combine stronger balance sheets and cash flows with more modest pricing.
- Income focused readers who want yield backed by fundamentals can scan a 219 dividend fortresses that pair higher payouts with robust financial support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com