
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Could Soft Credit Checks Change The Bull Case For Experian (LSE:EXPN)?
- Experian recently rolled out upgrades to its Power Profile Plus for Mortgage tool and launched Experian Cashflow Data Bureau, giving lenders deeper credit and cash flow insight through soft inquiries and consumer-permissioned data while managing credit assessment costs.
- Together with the expansion of Experian Agent Trust and new income and employment checks in healthcare, these moves show Experian leaning hard into data-rich, lower friction decisioning for both lenders and providers.
- Next, the focus is on how Experian's push into soft inquiry mortgage profiles reshapes the broader investment narrative around its data platforms.
Experian Investment Narrative Recap
To own Experian, you need to believe in a long runway for data-driven decisioning across lending, healthcare and fraud, with the group monetising richer datasets through its platforms. The short-term swing factor is how quickly demand recovers in lending-heavy markets where conditions have been subdued, especially unsecured credit volumes.
The biggest risk still sits outside Experian, in macro and credit cycles across North America and Latin America, as well as currency moves in Brazil. The new soft inquiry mortgage tools and cash flow bureau look additive, but do not materially change those near-term sensitivities on their own.
The Power Profile Plus for Mortgage upgrade looks most relevant for the near-term story. It aligns with Experian’s core strength by selling more granular data and scores into existing lender workflows while keeping acquisition costs in check. Unlimited eligible soft inquiries and score flexibility keep the product tied to origination volume without forcing lenders into higher upfront data spend.
For you as an investor, this matters because the credit cycle remains the primary catalyst. At the same time, execution on products like Power Profile Plus can influence how Experian captures that volume when it returns. The key watchpoints stay the same: lender adoption, pricing discipline, competitive pressure and whether subdued lending conditions ease in key geographies.
Experian's narrative projects US$10.6b revenue and US$2.1b earnings by 2029. This assumes 8.0% yearly revenue growth and an earnings increase of about US$600m from US$1.5b today.
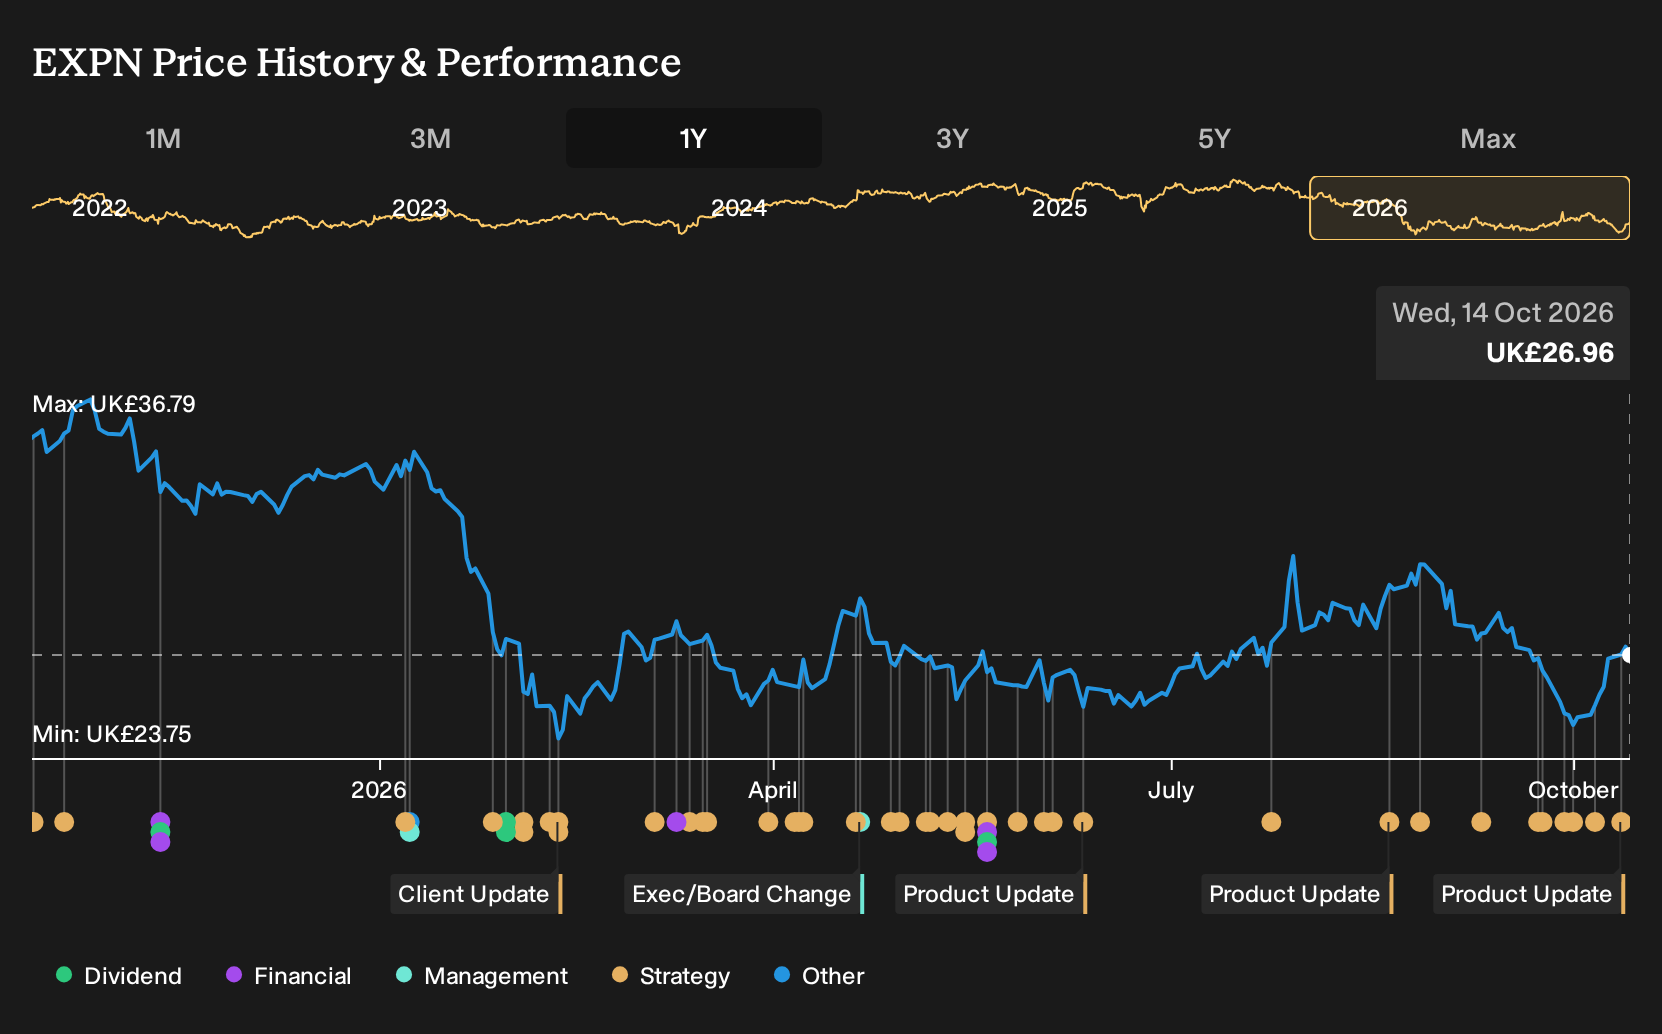
Explore how Experian's fair value indicates a 39% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts lean heavily on Experian’s AI led platforms as a catalyst, including Ascend and Agent Trust. They were already pencilling in revenue of about US$11.3b and earnings near US$2.2b by 2029. You can treat the new mortgage and cash flow launches as fresh information that might reshape those views.
Explore 4 other Experian fair value estimates, including one that suggests as much as 99% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Experian research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Experian. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Experian's overall financial health at a glance.
Looking For More Investment Ideas Beyond Experian?
Once you have a view on Experian, it can help to compare it with other stocks that share some of the same strengths or risk profiles. The Simply Wall St Screener lets you filter for themes that match your own style, whether you care more about balance sheets, dividends or underappreciated opportunities.
- If capital protection is high on your list, you can start with companies that score well on stability and financial resilience using the 4 resilient stocks with low risk scores.
- If value matters most to you, you can search for mispriced opportunities where quality and fundamentals still look solid by checking the 8 high quality undervalued stocks.
- If you want ideas that the wider market may be overlooking, you can focus on stocks with strong metrics but limited coverage through the 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com